What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Some links on this page are affiliate links: if you buy through them we may earn a commission, at no extra cost to you.
If you sell through multiple e-commerce platforms in India, decide your GST registration route before listing products, then keep one controlled invoicing and reconciliation process across every platform. Your checklist needs to connect each order to the correct GSTIN, invoice, dispatch or fulfillment location, return or credit note, marketplace settlement, and TCS entry. This India-focused guide reflects official material available on October 25, 2026; GST rules, thresholds, forms, and due dates can change, so confirm current notifications before acting.
Do I need GST registration to sell on multiple e-commerce platforms?
It depends on the kind of supply, the platform’s role under GST, and whether you qualify for a specific alternative route. The ordinary turnover-threshold exemption may not be available to a supplier making supplies through an electronic commerce operator (ECO) that is required to collect tax at source (TCS) under section 52 of the CGST Act.
As an Amazon Associate I earn from qualifying purchases.
CBIC’s sectoral FAQs qualify this rule: the requirement applies when the supply is made through an ECO that is required to collect section 52 TCS. Do not assume that every online listing or platform relationship has the same treatment. Confirm whether each platform is an ECO required to collect TCS for the particular supplies you make, and obtain advice on how the current rules apply to your products and business structure.
Check the available route before onboarding
- Regular GST registration: Determine whether your sales and platform arrangements require normal registration. If registration is needed, identify the state or states where registration and place-of-business details must be addressed.
- GSTN enrolment for eligible unregistered goods sellers: Eligible sellers of goods in one State or Union Territory may use the GSTN enrolment facility instead of regular registration, subject to the conditions that apply to that facility. Confirm eligibility before relying on it; it is not a general exemption for all online sellers.
- Simplified ECO registration scheme introduced in 2026: This optional route has additional conditions. The seller must meet the scheme’s exclusive-ECO-supplies condition and its specified monthly output-tax ceiling. Where a warehouse is declared as the principal place of business, ECO consent is required. Biometric Aadhaar authentication and physical verification requirements also apply. The applicable ceiling and detailed conditions must be checked against current official instructions.
These routes are not interchangeable shortcuts. A seller who selects a route without checking its conditions may create problems with platform onboarding, tax collection, invoice issuance, or return reporting. Keep a written record of why the chosen route applies, including the platform status, the seller’s supply type, the states involved, and any enrolment or scheme conditions relied on.
#1 Best Overall

- QUALITY INVOICES: Adams Order books provide a professional invoice or customer receipt; a great way to create and maintain a professional image for small businesses and service providers
- 50 TWO-PART CARBONLESS FORMS: Customers get the perforated white top copy; retain the canary and pink copies for your records
- WRAP-AROUND COVER: Fold the back cover between sets to keep invoices neat and legible
- ROOM FOR CUSTOMIZATION: A blank space at top leaves room for your company stamp; a big savings over custom-printed forms
- CONSECUTIVELY NUMBERED: Large 6-digit numbers in the upper right hand corner help you thumb through orders quickly
Apply and map the business footprint
- On the GST portal, use Services → Registration → New Registration for a new registration application.
- List every selling state, warehouse, fulfillment center, and platform account. Map each to the GSTIN responsible for the supply and its records.
- Configure the platform account, accounting system, and fulfillment workflow to use that mapping consistently. If the same stock is handled from more than one location, establish how dispatch records and invoices will identify the relevant fulfillment location.
- Save registration, enrolment, consent, authentication, and verification records alongside the business’s compliance files.
How should I manage invoices across multiple platforms?
Use one controlled invoice process that can handle every platform while keeping invoice numbering unique for each GSTIN and financial year. A platform order number is not a substitute for the seller’s tax invoice number.
GSTN’s GSTR-1 guidance states that, for a particular GSTIN, there cannot be duplicate invoice series in a particular financial year. This means a seller should not let separate marketplace accounts or staff create overlapping invoice numbers under the same GSTIN. A centrally controlled sequence—or a system that enforces the same rule—is safer than numbering invoices independently by platform.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errorsCapture the fields needed to trace each transaction
For each order, retain enough information to follow the transaction from sale through filing and settlement. The record should connect the platform order ID with the GSTIN, invoice, stock movement, payment and any later adjustment.
- Platform name and order ID; responsible GSTIN; invoice number and date.
- Customer status and customer GSTIN where applicable.
- Product or service description, HSN or SAC, taxable value, applicable GST rate, and tax components.
- Place of supply and the shipping, dispatch, or fulfillment location used for the transaction.
- Discounts and their treatment, shipping or fulfillment charges, and any other amount included in the transaction.
- Cancellation, return, refund, replacement, and credit-note details, linked to the original order and invoice.
- Where required, e-invoice reference details and the related QR information.
Keep the original invoice and any correction or credit note connected rather than overwriting the original transaction record. That makes it possible to explain why the reported taxable value, the goods dispatched, and the final settlement differ. Establish a process for replacement shipments as well: the team should be able to identify the original sale and determine which document supports the replacement movement.
Rank #2

- Two-Part Carbonless Invoice Book: Each invoice book has 50 sets of invoices, each with a white/light yellow section, with the yellow section retained in the invoice book to maintain detailed records.
- Consecutively Numbered: Enlarged red 6-digit numbers in the upper right corner of each invoice receipt book help you quickly navigate through your orders.
- Wraparound Divider Flap: A thick folded cardboard divider is integrated into the back of each invoice book for use between each two-part sales order to prevent the written content from rubbing off on subsequent copies of the invoice, resulting in wasted invoices.
- 2 Packs/50 Sets (100 Sets Total): Each invoice book provides 50 sequentially numbered carbonless sets of 2 invoice books for long-term use.
- Customizable Space: Each invoice book for small business has space at the top to add a company seal or sticker.
How do I reconcile TCS and settlements from several marketplaces?
Reconcile each platform’s settlement cycle separately, then consolidate the results by GSTIN and filing period. A bank deposit is a net amount after platform adjustments; it is not, by itself, a complete record of sales, fees, returns, or tax credits.
For every settlement, connect the platform’s order and transaction report to the seller’s invoices, dispatch records, refunds, charges, and TCS data. Keep platform commission, logistics, advertising, payment-gateway, and other charges distinct from taxable sales. This separation helps prevent a deduction from being mistaken for a reduction in the underlying sale.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Settlement-cycle reconciliation
- Start with gross orders. Match order lines and order IDs to invoices and dispatch or fulfillment evidence. Investigate orders with no invoice, invoices with no corresponding order, and timing differences.
- Account for cancellations and returns. Match each cancelled or returned order to the relevant platform refund record and the seller’s invoice adjustment or credit note, as applicable.
- Break out platform charges. Record commissions, logistics, advertising, payment-gateway deductions, and other charges in their appropriate accounts rather than netting them against sales without a trail.
- Match the settlement amount. Reconcile gross orders, refunds, other adjustments, platform charges, and the net amount paid. Retain the platform statement that explains the calculation.
- Match TCS. Compare the ECO’s TCS data with the seller’s GST records for the corresponding transactions and period. Record timing or amount differences for investigation rather than silently carrying them forward.
- Close the cycle by GSTIN. Confirm that each line has been assigned to the correct GSTIN and reporting period, then preserve the reconciliation and supporting statements.
When two ECOs participate in a transaction, do not assume that both are responsible for TCS—or that one platform’s report resolves the issue. Assess TCS responsibility transaction by transaction using the parties’ roles and current rules. Document the conclusion and the records used to support it.
What GST returns and records should an online seller prepare?
Build a filing calendar around the returns applicable to the seller’s registration and the current filing rules. At each periodic close, reconcile the books, inventory, platform reports, TCS information, invoices, and return data before submitting a return.
Rank #3
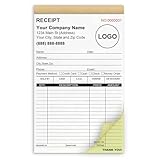
- Custom Receipt Book for Business: Custom receipt book designed for small business use, personalize with your company name, logo, address and contact details.Create a professional invoice book
- Receipt Book with Carbon Copies: This receipt book with carbon copies uses premium carbonless paper, allowing you to write once and get clean duplicate or triplicate copies. No messy carbon sheets, perfect for daily business operations
- Multiple Sizes & Sequential Numbering: Each set includes 2 books with 50 sets per book (100 sets total), all sequentially numbered for organized record keeping. Ideal invoice book for small business managing receipts, orders, and invoices efficiently
- Professional Design & Standard Sizes: Standard 5.5" x 8.5" size fits perfectly in hand or workspace. Strong binding with sturdy backing ensures durability, making this custom invoice book reliable for shops, contractors, and service professionals
- Versatile Use: Choose from two-part (white and yellow) or three-part (white, yellow, and pink) forms. Ideal for invoices, sales orders, purchase orders, work orders, and quotes. Perfect for small business owners, contractors, freelancers, retail stores, and restaurants. It also makes a thoughtful and practical gift for the entrepreneurs in your life
GSTR-1 reporting should reflect the seller’s taxable supplies through e-commerce channels in the applicable tables and in a way that agrees with the invoice records. Review the invoice series for duplicates for each GSTIN and financial year. The operational requirement is not just to upload figures: the reported figures should be traceable to documents, platform activity, and the business’s stock and accounting records.
Records to maintain
Section 35 of the CGST Act requires records relating to production or manufacture, inward and outward supplies, stock, input tax credit (ITC), and output tax. For a multi-platform seller, those statutory categories need a practical audit trail connecting marketplace transactions to inventory and accounting records.
- Invoices, credit notes, and relevant e-invoice data.
- Platform order, return, cancellation, refund, settlement, and TCS statements.
- Dispatch, shipping, and fulfillment records that identify the location involved.
- Stock and inventory records, including movements between relevant locations.
- Accounting records supporting taxable value, output tax, ITC, and platform charges.
- Warehouse and place-of-business documents, plus the platform-to-GSTIN mapping.
- Filed returns and reconciliations showing how the reported values were derived.
Annual-return obligations and deadlines depend on the current position under Rule 80. Check applicability and the relevant deadline for the filing year instead of assuming that every seller has the same obligation. For annual close, tie annual sales, returns, credit notes, tax paid, ITC, inventory, and TCS to the year-end books, then archive the underlying records according to applicable retention rules and internal controls.
When does e-invoicing apply to marketplace sales?
Check e-invoicing applicability against the current thresholds, notifications, and rules before relying on this checklist. The relevant requirements are notification-sensitive; a seller should not infer applicability—or an exemption—from using a particular marketplace or accounting workflow.
Rank #4

- EFFICIENT 2-PART CARBONLESS SYSTEM WITH 50 SETS – This contractor invoice book 2 part contains 50 sets of white and yellow carbonless forms, creating instant duplicates with no messy carbon paper. Perfect for on-the-job billing, it serves as a reliable invoice receipt book for small business owners who need clean, professional copies for customers and records.
- PROFESSIONAL SIZE & DURABLE COVER – Measuring 7.3" x 11", each page provides ample writing space for labor, materials, and job details. The 250g coated paper cover resists wear on job sites, making this contractors invoice book a durable choice for electricians, plumbers, and general contractors.
- SEQUENTIALLY NUMBERED & PERFORATED – Pre-numbered pages help track every transaction, while the top perforated tear line allows for clean, easy removal. Whether used as contractor invoice forms or work order receipt book pages, the organized layout reduces errors and saves time.
- STURDY CARDBOARD BACKING FOR ON-SITE USE – Built-in bottom cardboard backing provides a firm writing surface anywhere—no desk required. Ideal for work order estimate forms or contractor estimate book applications, this feature ensures legible copies even in trucks or trailers.
- VERSATILE FOR MULTIPLE BUSINESS TYPES – Works seamlessly as invoice receipt book 2 part for contractors, work order estimate forms for repair shops, or contractor estimate book for service professionals. From construction and landscaping to HVAC and handyman services, this invoice receipt book for small business adapts to any industry that needs professional on-site billing.
Where e-invoicing applies, the applicable invoice information must be authenticated through the Invoice Registration Portal (IRP), and the seller should retain the resulting reference and QR information with the transaction record. The National Informatics Centre’s e-invoice documentation says invoice information is transferred from the e-invoice portal to both the GST portal and e-way bill portal in real time. Treat that transfer as part of the system flow, not as a reason to stop maintaining the seller’s own records and reconciliation trail.
Operationally, make e-invoice checks part of invoice generation rather than a month-end afterthought. A workflow should identify which transactions need authentication, retain the IRN and QR details where required, and connect the resulting data to the original order, invoice, dispatch, and return records. If the applicability of a transaction is unclear, resolve it under the current rule before issuing or reporting documents.
Recommended Free Tools
How should I handle a warehouse shared by multiple online sellers?
Document each seller’s right to use the warehouse and treat the location deliberately in the GST and fulfillment records. Multiple ECO sellers may use the same facility as an additional place of business when each has documents supporting its use and maintains the required records.
A shared address alone does not establish that every seller has the same GST treatment or that one seller’s records cover another’s stock. Keep seller-specific evidence of the warehouse arrangement, inventory, inward and outward movements, and dispatches. Where the warehouse is proposed as the principal place of business under the optional 2026 simplified ECO scheme, the scheme’s ECO-consent condition is relevant and should be documented.
Best Value
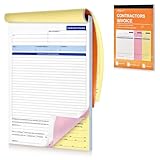
- Professional & Delicate Design: Our Professionally designed Contractor’s Invoice Books provide lots of room for descriptions, great for transaction documents. 3-part carbonless forms (white/canary-rose/yellow; 50 sheets each) are ideal for receipt books, and can help build sense of trust with your clients.
- Large Size, with Company Stamp Placement: The 11 x 8 inch large size provides ample room for your recording; and features with a blank space up top where you can customize your company stamp or memos to create personalized and professional invoice books.
- Sturdy Page Divider Included: Our Invoice Book comes with a cardboard backing that can help you write smoothly and folds out to be a page divider or separator to prevent imprinting onto the forms below.
- Quality and Trustworthy Paper Choice: Unlike traditional carbon paper, our carbonless invoice books are more eco-friendly and reliable which are stain-free, recyclable and smooth to write on.
- Easy to Tear-off & Versatile: with perforated line at the top of each invoice form, they are easy to tear-off neatly. They work also for work invoices, contractor estimate forms, construction projects, and sales orders.
Map each warehouse to the GSTINs and platform accounts that use it. Ensure that invoices and dispatch records can identify the location involved, and make stock records capable of distinguishing the goods of each seller. This is particularly important when several sellers’ products are stored or fulfilled by the same facility.
What should a monthly compliance close include?
A repeatable close reduces the chance that platform timing, refunds, or warehouse movements become unexplained differences at filing time. Assign an owner for each reconciliation and preserve the evidence used to resolve exceptions.
- Reconcile platform orders, invoices, dispatches, returns, cancellations, refunds, credit notes, and settlement amounts.
- Match platform TCS data to GST records, by platform, transaction, GSTIN, and period; document unresolved differences.
- Review taxable value, output tax, ITC, discounts, charges, and place-of-supply classification against the books and supporting documents.
- Review the GSTR-1 e-commerce reporting and confirm invoice numbering is not duplicated for the GSTIN in the financial year.
- Check e-invoice applicability and ensure required authentication details are retained.
- File the applicable periodic returns using the current portal instructions and filing calendar.
- Save invoices, e-invoice data, settlement and return reports, TCS statements, shipping records, warehouse documents, reconciliations, and filing acknowledgments in an organized evidence folder.
At annual close, extend the same control across the full year: tie sales, returns, credit notes, tax paid, ITC, inventory, and TCS to year-end books; review annual-return applicability under the current Rule 80 position; and apply the relevant retention rules. A software workflow can help with ingestion and matching, but compare systems on GSTIN and state coverage, multi-platform order and return handling, TCS reconciliation, e-invoice and e-way-bill integration, HSN/SAC and place-of-supply controls, warehouse mapping, audit trails, exports, user permissions, and support for current notifications.
What are the most common compliance gaps to prevent?
Most avoidable problems arise when platform operations and tax records are managed as separate systems. Use these checks to catch gaps before the return close.
- Assuming the turnover threshold settles the question: First determine whether the relevant ECO is required to collect section 52 TCS and whether a specific enrolment route or scheme is available to the seller.
- Using separate invoice sequences without control: Platform-specific numbering can conflict when multiple accounts share one GSTIN. Enforce uniqueness by GSTIN and financial year.
- Treating net deposits as sales: Rebuild the settlement from gross orders, returns, charges, adjustments, and TCS rather than using the bank amount as the sales figure.
- Leaving returns and replacements unlinked: Connect the adjustment document and refund to the original order and invoice so the reporting trail remains explainable.
- Ignoring the fulfillment location: Map warehouses and dispatch activity to the responsible GSTIN and retain evidence for each seller using a shared facility.
- Assuming portal data replaces books: Keep the seller’s own statutory records and reconciliations even when information flows electronically between GST systems.
- Using old thresholds or due dates: Confirm current notifications and filing instructions for the relevant period before filing or choosing a registration route.
Frequently Asked Questions
Can a paper GST invoice book replace GST filing or statutory records?
No. A physical invoice book can help maintain a sequential paper trail, but it does not submit returns, authenticate invoices through the IRP when required, or replace the records required under section 35.
Do I need a separate GST invoice sequence for each marketplace?
The key control is uniqueness for each GSTIN within the financial year, not a separate sequence for every platform. If you use platform-specific prefixes or series, make sure the combined system cannot create duplicate invoice numbers for that GSTIN.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchDoes real-time e-invoice data transfer mean I do not need to check my GST returns?
No. The system transfer described by NIC concerns invoice information moving to GST and e-way bill portals; the seller still needs to reconcile the records and verify that the applicable return data is complete and correct.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

