Freedom251 › Card Issuing Platforms
Wallester White Label
What Wallester White Label is
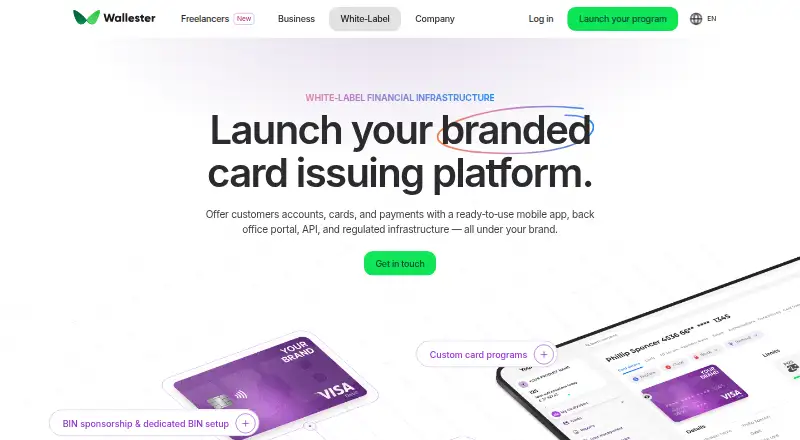
Wallester White Label provides branded accounts, card programs and payments through a mobile app, back-office portal, API and regulated infrastructure. Businesses can configure debit, prepaid or credit cards for consumer, business or corporate use. The portal includes controls for users, cards, balances, limits, spending rules, approval flows and program activity. Accounts and cards support EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON and USD, with global payments. An in-house REST API connects card programs, controls and payment workflows; the branded app supports Apple Pay and Google Pay with tokenized credentials. The platform includes KYC/KYB, AML, fraud monitoring and payment processing. Wallester identifies itself as a Visa Principal Member and an Authorized Payment Institution licensed by Estonia’s Finantsinspektsioon, and states that it is PCI DSS Level 1 certified for payment data. The service is described for the EEA and UK. Pricing is listed at €2,495 a month for non-financial institutions, €3,995 a month for financial institutions and €5,995 a month for VASP financial institutions.
Who it suits
The service is presented for regulated and non-regulated businesses, including banks, lenders, fintech companies, marketplaces, employers and digital asset platforms. It may suit organizations seeking branded card programs with account, payment and compliance controls.
What it does well
- Debit, prepaid and credit card programs
- Back-office controls for balances, limits and approvals
- Supports ten listed account and card currencies
- Branded app supports Apple Pay and Google Pay
- KYC/KYB, AML and fraud monitoring included
What to know first
- Monthly plans start at 2495.00 EUR
- Pricing differs by institution type
- Coverage is described for the EEA and UK
Limits
The listed monthly plans are 2495.00 EUR for non-financial institutions, 3995.00 EUR for financial institutions, and 5995.00 EUR for VASP financial institutions. Wallester says a first virtual card may be available in 30 days and physical cards can follow in up to two months.
Plans
| Plan | Billed and limits | Price |
|---|---|---|
| White-Label for non-financial institutions | €2,495 / month · No setup or hidden fees stated | €2,495 a month |
| White-Label for financial institutions | €3,995 / month · No setup or hidden fees stated | €3,995 a month |
| White-Label for VASP financial institutions | €5,995 / month · No setup or hidden fees stated | €5,995 a month |
As wallester.com lists them, read 5 Oct 2026. The maker's own page has the final word.
Getting started
- Visit https://wallester.com/white-label.
- Choose the plan for non-financial institutions, financial institutions, or VASP financial institutions.
- Use the mobile app, web portal, or API as appropriate for your program.
- Configure a debit, prepaid, or credit card program and its controls.
- Set up virtual cards first; Wallester says a first virtual card may be available in 30 days, with physical cards following in up to two months.
Wallester White Label is a configurable card-issuing and payments platform for organizations building a branded financial service. It is best suited to businesses that need their own card program and can support its regulatory and operating demands. Its breadth is compelling, but the monthly fees make it a poor fit for a small or unproven program.
Overview
Wallester brings branded accounts, cards and payments together in a mobile app, back-office portal and REST API. Businesses can shape debit, prepaid or credit programs for consumer, business or corporate use, then manage users, balances, limits, spending rules, approvals and activity from the portal. That combination gives a program operator meaningful control without requiring it to build every card workflow itself.
The platform combines payment processing with KYC/KYB, AML and fraud monitoring. Wallester identifies itself as a Visa Principal Member and an Authorized Payment Institution licensed by Estonia’s Finantsinspektsioon, and says it holds PCI DSS Level 1 certification for payment-data handling. Those credentials and controls support a regulated operating model; they do not remove the need for a business to assess its own compliance obligations.
Coverage is focused on the EEA and UK. Accounts and cards support EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON and USD, with global payments also supported. Wallester says a first virtual card can be available in 30 days and physical cards can follow in up to two months. That is a defined path to launch, but not an immediate rollout.
Key features
- Configurable card programs: Debit, prepaid and credit options serve consumer, business and corporate use cases. Multi-program support is useful to operators serving distinct customer or employee groups.
- Program controls: Teams can manage cards, users, balances, limits, spending rules, approval flows and program activity in the back-office portal. This suits organizations that need operational oversight; it also means there is more to configure and govern than a simple card product.
- Accounts and payments: Ten supported currencies, alongside global payments, help businesses serving customers across the EEA and UK. The coverage is not a claim of universal local account availability.
- REST API: Wallester’s in-house API connects card functions, program controls and payment workflows. It is the stronger fit for businesses embedding issuance into their own product than for teams seeking a standalone, off-the-shelf expense tool.
- Mobile wallets: The branded app supports Apple Pay and Google Pay through tokenized credentials, adding familiar wallet payments to a company’s card experience.
- Issuer framework and compliance: Programs can launch under Wallester’s issuer and scheme framework, with a dedicated BIN setup available when needed. KYC/KYB, AML, fraud monitoring and payment processing are included in the platform’s compliance capabilities.
Pricing
Wallester uses paid monthly plans, with no setup or hidden fees stated for the three priced options. The recurring commitment is significant, so the right tier depends on the institution type and program economics, not just the feature set.
| Plan | Price | Best fit |
|---|---|---|
| White-Label for non-financial institutions | €2,495 a month (billed €2,495 / month) | Marketplaces, employers and other non-financial businesses building a branded card program. |
| White-Label for financial institutions | €3,995 a month (billed €3,995 / month) | Financial institutions that need a branded program and the platform’s account, card and payment capabilities. |
| White-Label for VASP financial institutions | €5,995 a month (billed €5,995 / month) | VASP financial institutions whose use case calls for the dedicated tier. |
The lower-priced non-financial tier is the least costly route into the white-label platform, while financial institutions pay more for their applicable plan. The VASP tier carries the highest monthly fee. No seat counts, card quotas, trial or renewal terms are given for these plans, so organizations should weigh the recurring fee against their expected program scale before committing.
Platforms
Wallester supports Android, iOS and web access, as well as API integration. That mix covers branded mobile experiences, portal-based administration and custom connections to a business’s existing product or payment workflows.
Who it's for
The service is presented for regulated and non-regulated businesses, including banks, lenders, fintech companies, marketplaces, employers and digital asset platforms. It makes most sense for organizations that want to issue cards under their own brand, need centralized controls and can justify a substantial monthly platform cost. A business seeking a low-cost card tool, or one without the people and processes to operate a financial program, should look elsewhere.
Pros and cons
- Pro: Branded debit, prepaid and credit programs can serve consumer, business and corporate use cases, giving operators room to shape different products.
- Pro: The combination of portal controls, API access, payment workflows and compliance tooling covers much of the operating stack in one platform.
- Pro: Support for Apple Pay and Google Pay brings wallet payments into the branded app experience.
- Con: Monthly prices start at €2,495 a month, a material commitment for organizations still validating demand.
- Con: The stated rollout window—30 days for a first virtual card and up to two months for physical cards—requires planning rather than a rapid, same-day launch.
- Con: Coverage is described for the EEA and UK; businesses needing a broader regional card program should confirm that the footprint fits their target markets.
Alternatives
For a wider comparison, see Card Issuing Platforms.
- Extend is worth considering when a free starting tier and expense-oriented virtual-card limits matter more than a white-label issuing platform: its Starter plan is free for up to 5 users, 10 guests and 100 virtual cards per month, with one expense category and 15 category labels.
- Visa DPS Forward may suit teams that want to begin with a free API sandbox before discussing production fees.
- Conferma Pay is another paid option for organizations that want to discuss a platform through a demo.
- Paynetics Card Issuing is an option to compare when customizable programs and physical or virtual Visa and Mastercard cards are central requirements.
- Marqeta is a paid API-and-web alternative for organizations prepared to contact sales about enterprise platform pricing.
- Thredd is another paid API-and-web option.
- Enfuce Cards may fit teams that prefer program-scoped pricing, with implementation, monthly service, volume-based fees and possible add-ons.
- HPS PowerCARD is another paid option, with API, web and self-hosted platforms.
Verdict
Wallester White Label is a strong candidate for established businesses that want a branded, multi-currency card program with controls, payment workflows and compliance capabilities under one provider. Its central advantage is the breadth of the program stack; its clearest drawback is the high monthly entry price, compounded by a launch measured in weeks. Choose it when the program can support that commitment and its EEA/UK focus fits. Look elsewhere if you need a free starting point, broader confirmed coverage or a lighter-weight expense product.
Verdict
Wallester White Label combines branded card programs with account management, payment workflows and compliance tools. The listed monthly costs and EEA/UK coverage are key points for organizations assessing fit.
Questions
How much does Wallester White-Label cost?
The listed plans cost €2,495 a month for non-financial institutions, €3,995 a month for financial institutions, and €5,995 a month for VASP financial institutions.
Which platforms does it support?
Its listed platforms are Android, iOS, web, and API.
Can businesses issue physical and virtual cards?
Yes. Virtual cards, physical cards, and an issuing API are supported.
Which currencies are supported?
Accounts and cards support EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON, and USD.
Who is Wallester White-Label for?
It is presented for regulated and non-regulated businesses, including banks, lenders, fintech companies, marketplaces, employers, and digital asset platforms.
What compliance and security capabilities does it include?
The platform includes KYC/KYB, AML, fraud monitoring, and payment processing. Wallester states that it is PCI DSS Level 1 certified for handling payment data.
Facts from Wallester White Label's own pages
- Accounts and currencies
- The platform supports accounts and cards in EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON, and USD, plus global payments. · wallester.com, 5 Oct 2026
- API
- Wallester offers an in-house REST API for connecting cards, program controls, and payment workflows. · wallester.com, 5 Oct 2026
- Back-office controls
- The portal lets teams manage cards, users, balances, limits, spending rules, approval flows, and program activity. · wallester.com, 5 Oct 2026
- BIN sponsorship
- Programs can launch under Wallester’s issuer and scheme framework, with dedicated BIN setup available where needed. · wallester.com, 5 Oct 2026
- Card programs
- Businesses can configure branded debit, prepaid, or credit card programs for consumer, business, and corporate use cases. · wallester.com, 5 Oct 2026
- Company
- Wallester’s about page describes it as a fintech company providing a platform for digital payments and card issuance, with a Tallinn office; a Wallester article says it was founded in Tallinn in 2016. · wallester.com, 5 Oct 2026
- Compliance
- The platform includes KYC/KYB, AML, fraud monitoring, and payment processing, and identifies Wallester as a Visa Principal Member and an Authorized Payment Institution licensed by Estonia’s Finantsinspektsioon. · wallester.com, 5 Oct 2026
- Coverage
- The White-Label page describes multi-currency accounts, cards, and payments for the EEA and UK. · wallester.com, 5 Oct 2026
- Founded
- 2016 · wallester.com, 28 Sept 2026
- Headquarters
- Tallinn, Estonia · wallester.com, 28 Sept 2026
- Launch timing
- Wallester says a first virtual card can be available in 30 days and physical cards can follow in up to two months. · wallester.com, 5 Oct 2026
- Mobile wallets
- The branded mobile app supports Apple Pay and Google Pay, using tokenized credentials for wallet payments. · wallester.com, 5 Oct 2026
- Product
- Wallester White-Label provides branded accounts, cards, and payments through a mobile app, back-office portal, API, and regulated infrastructure. · wallester.com, 5 Oct 2026
- Security
- Wallester states that it is PCI DSS Level 1 certified for handling payment data. · wallester.com, 5 Oct 2026
- Target customers
- The service is presented for regulated and non-regulated businesses, including banks, lenders, fintech companies, marketplaces, employers, and digital asset platforms. · wallester.com, 5 Oct 2026
Where Wallester White Label stands on Freedom251
- Card Issuing Platforms#13 of 22