Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteA sudden Sensex rise is a reason to review your plan, not a signal to buy whatever has just gone up. Start by reconnecting each pool of money to its goal, time horizon, liquidity need and risk limits. Then measure your actual asset mix and concentration against the mix your plan requires. Rebalance only when that comparison shows a mismatch, and check taxes, charges and liquidity before placing any order.
The Sensex does not predict what an individual share, fund or personal portfolio will do next. The process below is general investor education, not a personal recommendation to buy or sell a security.

As an Amazon Associate I earn from qualifying purchases.
What a Sensex rally tells you—and what it does not
The S&P BSE Sensex is an index of 30 large, well-known companies from different sectors of the Indian economy, according to SEBI Investor. It is a market indicator, not a copy of every investor’s holdings. Your portfolio may contain other Indian companies, debt, cash, international assets or different weightings from the index.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
That difference matters after a sharp move. A portfolio heavily invested in Sensex constituents may have changed more than a portfolio holding bonds or cash, while a portfolio concentrated in companies outside the index may have behaved differently again. The index’s rise alone cannot establish that your portfolio is now too risky, too conservative or ready for another gain.
#1 Best Overall
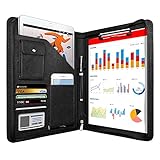
- 1. Multiple Compartments: This padfolio has 1 A4 clipboard, 1 A4 document sleeve, 1 mobile phone pockets, 5 card slots with a ID window, 1 gadget pocket with fastener and 1 pen holder
- 2. Practical Size: 34 × 25.5 × 3 cm / 13.3 × 10 × 1.1 inch, easy to carry in your suitcase or briefcase, a great companion for a business trip
- 3. Quality Material: made from PU Leather material, offering long-term durability, and super easy to clean up
- 4. Versatile Usage: Look confident and professional when using this stylish business portfolio at meetings, job interviews, or classrooms; give positive impression at all important occupations
- 5. Perfect Choice: Handy portfolio binder, suits both men and women; also a great gift choice for work colleagues, friends, or a recent college graduate
Index values can fluctuate greatly over short periods, and a past rise does not guarantee future performance. Treat the move as a calendar prompt to check your plan rather than as evidence that prices will continue higher. Buying solely because an asset has risen is price chasing; selling solely because a headline feels alarming is the opposite form of the same reaction.
First, define the job of each rupee
Before looking at returns, separate your money into identifiable goals. SEBI’s investor guidance puts goals and investment objectives at the start of the process because an investment can be suitable for one purpose and unsuitable for another.
Match holdings to a specific goal
Write down what each pool is intended to fund: a near-term bill, a home purchase, education, retirement or another objective. Give the goal a target date and an approximate amount in today’s rupees. If one account serves several purposes, split it into virtual buckets so a long-term retirement holding is not judged by the same standard as money needed next year.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Separate time horizon from market excitement
Time horizon is the period until the money must be available. A near-term obligation leaves less time to recover from a fall, regardless of how strong the market looked this week. SEBI advises avoiding volatile or illiquid investments for near-term needs when the investor cannot bear that risk. A long horizon may allow more fluctuation, but it does not make a loss impossible or guarantee a profit.
Check liquidity, not just expected return
Ask how quickly each holding can be converted to usable cash, what conditions could delay that conversion and whether selling at that moment could create a loss or a tax charge. Keep the amount needed for an imminent expense in an instrument whose liquidity and fluctuation are consistent with that deadline. Do not let a rally persuade you to put emergency or scheduled-expense money into an asset you may have to sell during a downturn.
Reassess both kinds of risk
A useful review distinguishes risk capacity from risk tolerance. Capacity is whether your finances can absorb a loss without jeopardising a goal. Tolerance is whether you can remain invested through fluctuations without abandoning the plan. They can point in different directions: a young investor may tolerate volatility emotionally but still have a short deadline for a house deposit, while a financially secure person may have capacity for risk but little willingness to see large swings.
Questions that test capacity
- Would a substantial fall force you to borrow, delay a required payment or sell an asset at an unfavourable time?
- How stable are your income, emergency reserves and other sources of cash?
- Is the goal flexible, or is the date fixed by a fee, contract or family obligation?
- Could a loss in one account affect another goal that you have not linked to that account?
Questions that test tolerance
- What did you do during a previous market decline: follow the plan, reduce risk or sell in panic?
- Would you still accept the current mix if prices moved sharply in either direction next month?
- Are you considering a trade because it fits a written rule, or because a recent gain feels safer than it did before?
If capacity and tolerance disagree, the more restrictive constraint generally deserves attention. A professional suitability assessment may be appropriate when you cannot determine a workable balance yourself; an index move is not a substitute for that assessment.
Rank #2

- 【Quality Material】FYY leather a5 journal binder is wear-resistant and comfortable to handle. The card slots and pockets inside can organize your cards, tickets, cash, etc. The pen holder can keep the pen in place. We care about climate change impacts. Our products are CLIMECO-certified, joining the "Climate Friendly Commitment" program to measure, reduce and offset carbon footprints.
- 【Convenient Structure】The 6 rings binder a5 is structured with a convenient metal snap closure, include A5 refill paper, binder pockets and dividers paper sheet inside, perfect for a school notebook, office notebook, travel journal, budget noteboook, sketchbook, notebook, personal organizer, a planner, etc.
- 【Sturdy 6-rings】Made of sturdy stainless steel, can hold the paper firmly and prevent papers from falling off. With 2cm inner diameter, the binder can keep 80-100 sheets paper, meeting your daily needs.
- 【Perfect Size】The size of the a5 journal binder cover is 23.5 x 17.8 x 2 cm (9.2 x 7 x 0.8 inches), perfect for your shoulder bags and backpacks. An ideal gift for Christmas, New Year, Valentine's Day, Birthday.
- 【Package Contain】The 6 rings binder a5 includes 1pcs 6 ring binder cover, 80 sheets of lined paper, 3pcs binder pockets with 3 styles, and 5pcs dividers paper sheet. Your 100% satisfaction is our mission. If there is any problem about our items, please feel free to contact us in e-mail, we will provide money-back or replacement service.
Measure the portfolio you actually own
Use current account statements, fund statements and contract notes to make one consolidated list. Record each holding’s value and classify it by broad asset type, such as equity, debt, cash or an international asset. Then calculate each category’s share of the total. Include holdings spread across brokers, demat accounts, workplace plans and family accounts if they fund the same objective.
Compare with an objective-based target
Asset allocation should relate to goals, risk tolerance, time horizon and the investor’s circumstances. Compare the current percentages with the target mix you established for each goal. The relevant question is not whether equity rose, but whether the resulting mix still gives that goal an acceptable combination of growth potential, fluctuation and liquidity.
Do not manufacture a universal trigger from a market headline. The cited SEBI guidance does not prescribe one percentage band or calendar schedule that applies to every individual portfolio. If your written plan has a range or review date, use that rule consistently; if it does not, define one deliberately rather than adopting a threshold presented as a SEBI requirement.
Look through funds and wrappers
Do not stop at the product label. An equity fund, retirement account or managed portfolio can contain overlapping companies or sectors. Identify the underlying exposure where statements provide it, and count that exposure once when evaluating concentration. If the composition is not clear, obtain the latest official factsheet or statement before deciding that you are diversified.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Inspect concentration and diversification
A rally can increase the portfolio share of a company, sector or asset category even when you made no new purchase. Measure the largest single holding, the largest sector exposure and the combined share of correlated holdings. Also check whether several funds own many of the same companies.
Diversification can reduce the impact of poor performance in one investment, but it cannot remove market-wide price volatility. Holding more names is not automatically diversified if they depend on the same sector, economic driver or geography. Conversely, a concentrated position may be intentional for a specific goal, but its size should be a conscious decision rather than an accidental result of appreciation.
Concentration questions to record
- Has one company become a much larger percentage of the goal’s assets?
- Are several holdings exposed to the same industry or economic factor?
- Does the portfolio rely on one market, currency or type of security for a goal with a fixed date?
- Would a poor result in the largest exposure materially delay the goal?
Answer these questions using your own statements and plan. The Sensex’s 30-company composition does not reveal the concentration in your personal account.
Rank #3

- PERFECT BUSINESS PORTFOLIO - Designed to fit either side bound letter size notebooks or top bound letter (8.5x11 inch) and legal (8.5x11.75 inch) notepads, our padfolio is ideal for taking notes in meetings, delivering presentations or acing the big job interview. It serves as a legal pad holder, providing a convenient option for those who need to take notes on legal pads.
- STYLISH, CLASSY, PROFESSIONAL PORTFOLIO - make a strong impression in every business meeting, show your confidence with our hand-crafted folio made from high quality faux leather. Be the envy of your office or conference with this leather legal pad holder.
- SLIM & LIGHTWEIGHT PORTFOLIO - holds everything you need for a conference meeting - pen, resume, writing pad & business cards; this portfolio has a hard sturdy base providing a stable platform for making notes. It also functions as a resume portfolio folder, allowing you to keep all your important documents in one place. Additionally, the clear inside pocket provides a handy spot for your business card and the 3 pocket business card holder helps you stay organized.
- SPECIAL GIFT FOR SOMEONE YOU LOVE - celebrate their success in getting that new job or landing the big client that only they could do. Our leather portfolio document holder comes in a beautiful, strong matt black box that needs no additional wrapping. They will love you for this stylish and functional leather notepad.
- 1 Year Replacement Warranty - We want you to be 100% happy with your new legal pad portfolio for women and men; please contact us if you have any issue at all with your padfolio and we will replace it immediately.
Re-examine why each individual investment is still there
For every security or fund, write a short holding thesis in plain language: what role it serves, what evidence supports that role and what would make the thesis no longer valid. Consider fundamentals and future potential rather than relying on a past return. SEBI explicitly warns that past performance does not guarantee future returns.
A price increase can be consistent with your thesis, inconsistent with it or unrelated to it. Do not upgrade an investment’s quality merely because its quotation rose, and do not discard a sound holding solely because it lagged the index for a short period. If you cannot explain an investment’s purpose, pause before adding to it and gather the information needed to make an informed decision.
Choose among holding, rebalancing and getting advice
Once goals, risk and concentration are documented, compare the available actions. The right choice depends on your plan; the table sets out the decision axes rather than prescribing an allocation.
| Option | When it can fit | Risk and concentration effect | Liquidity, tax and cost questions | Discipline check |
|---|---|---|---|---|
| Keep the current portfolio | The actual mix still matches the goal, horizon and risk limits. | Leaves current exposures unchanged; confirm no company or sector has become unacceptably large. | No new trade cost, but future liquidity and tax consequences of eventual sales still matter. | Document why no change is required instead of treating inaction as a forecast. |
| Rebalance toward an existing target | The mix has moved away from the objectives in your written plan. | Reduces an exposure that has become too large and restores the intended risk profile. | Check applicable tax treatment, brokerage and other charges, bid-ask effects, exit loads or restrictions, and cash needs before trading. | Use the plan’s rule or review date; do not invent a threshold from the Sensex move. |
| Seek individualized advice | You need a personal allocation, tax calculation, suitability assessment or help coordinating several goals. | A qualified adviser can assess circumstances that a general checklist cannot; no adviser can remove market risk. | Confirm the adviser’s registration and fees and understand what service is being provided. | Ask for reasoning tied to your goals rather than a reaction to a hot tip. |
SEBI’s securities-market guidance identifies consulting a SEBI-registered Investment Adviser as an option for investment needs. Verify registration status and current rules independently before engaging anyone; no particular provider is endorsed here.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Calculate the real cost before placing a trade
Tax treatment can differ by asset class and transaction. Before selling or switching, identify the applicable rules for that specific asset, account type, holding period and trade date. The general guidance available here does not provide a current personal tax calculation, so do not infer your liability from someone else’s example. If the amount is material or the rules are unclear, obtain appropriate tax advice.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →List every implementation cost: brokerage, exchange or statutory charges, fund expenses, exit loads, spreads and any account fee triggered by the transaction. Keep the estimate beside the proposed order. A trade that appears to restore an allocation can still undermine a goal if costs or taxes consume money needed for that goal.
Maintain statements, contract notes, charge records and payment records. SEBI recommends keeping such records, both for monitoring and for establishing the cost and date of a transaction when you later need them.
A step-by-step review you can repeat
- Set a review date. Record the date of the Sensex move that prompted your attention, but do not treat that date as a buy or sell deadline.
- List each goal. For every account or bucket, write the purpose, target amount, target date and acceptable liquidity.
- Record the current holdings. Use the latest statements and include all accounts serving the same goal.
- Classify the exposure. Group holdings by broad asset type, geography, sector and, where available, underlying company exposure.
- Test capacity and tolerance. Note the loss that would threaten the goal and the fluctuation you can realistically stay invested through.
- Compare actual and intended mix. Identify any mismatch with the allocation that fits the goal. If there is no written target, pause and define one rather than borrowing a rule from a headline.
- Check concentration. Flag oversized company, sector or correlated exposures and explain whether each is intentional.
- Revisit each holding thesis. Use fundamentals and future potential, not the recent return alone, to decide whether the original reason still applies.
- Price the proposed implementation. Estimate taxes, charges, liquidity effects and any restrictions before submitting an order.
- Choose and document the action. Keep, rebalance or seek advice. Write the reason, the rule used and the conditions that would trigger the next review.
- Schedule the next periodic review. Review financial needs and whether goals remain achievable at a deliberate interval, rather than reacting to every index headline.
Behavioral guardrails after a fast rise
SEBI’s SMART Investor material promotes a long-term mindset, diversification and periodic portfolio review. It also cautions investors not to panic and sell when markets turn down. The same principle applies after a rally: avoid letting urgency replace a written process.
Common traps
- Recency bias: assuming the latest move is the most likely next move.
- FOMO buying: adding an asset because a friend, message or social post says it is “hot.”
- Index substitution: treating the Sensex as if it were your complete portfolio.
- Performance chasing: replacing a diversified plan with last period’s winner.
- Tax blindness: ignoring the cost of selling while comparing only headline prices.
- False diversification: owning several products that hold the same companies or sector.
SEBI’s do’s and don’ts guidance warns against basing investment decisions on hot tips. Ask what role a proposed trade plays in a goal, what evidence supports it and what it costs. If those answers are missing, waiting is a valid decision.
Illustrative situations (not recommendations)
Long-term goal, allocation still within plan
An investor reviews a retirement bucket after the index rises and finds that its equity and debt proportions remain within the ranges established for that goal. No company or sector breaches the investor’s stated concentration limit, and there is no near-term cash need. The review can end with a written decision to keep the mix and a scheduled follow-up; the rally itself supplies no reason to add money.
Near-term payment, equity now too prominent
Another investor discovers that money earmarked for a scheduled payment is exposed to a volatile asset and could not be replaced if prices fell. The relevant issue is the deadline and liquidity, not whether the Sensex may rise again. The investor can compare an adjustment with the plan, estimate taxes and charges, and seek qualified advice if the consequences are unclear.
Several funds, one hidden sector bet
A third investor owns multiple products and initially believes the portfolio is diversified. Looking through the holdings reveals substantial overlap in one sector. The review should address that combined exposure and the goal’s risk limit, rather than counting product names as separate diversification.
When a professional review is warranted
General education cannot calculate a suitable allocation for a particular person. Consider a SEBI-registered Investment Adviser or another appropriately qualified professional when you need a personal risk assessment, must coordinate taxable and retirement accounts, face a complex or urgent tax question, or cannot determine whether a proposed change keeps a goal achievable.
Ask what the professional is authorised to do, how fees are charged, what conflicts are managed and whether advice is documented against your goals. A registration check and a clear written scope are more useful than a promise based on the latest index direction.
Keep a simple review record
A notebook is optional; a spreadsheet or digital folder works just as well. Record the goal, target date, holdings, allocation, concentration observations, estimated costs, decision and next review date. Attach statements and contract notes. This record makes it easier to distinguish a deliberate rebalance from an emotional reaction and helps you see whether your financial needs and goals remain achievable.
The practical conclusion is narrow but important: a Sensex rally is information about one market index, not a command for your portfolio. Review the purpose and constraints of your money, measure the mix you actually own, correct only a plan-defined mismatch, and account for taxes, charges and liquidity before acting.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Recommended Free Tools

