Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallNeither a revolving credit facility nor a term loan is universally better for a homebuilders. A revolving line can fit recurring or phased costs when draws and repayments follow a project or working-capital cycle. A term loan can fit a known amount for a defined purpose with scheduled repayment. The right choice depends on the written offer: when funds are available, what they can pay for, what controls apply, and how the debt will be repaid.
How to choose between a revolving facility and a term loan
Start with the shape of the cash need, not the product name. If costs recur across phases or projects, a revolving facility may let the builder draw as needed, subject to availability and lender controls. If the need is a fixed sum for a defined use, a term loan provides an agreed principal amount and repayment schedule.

As an Amazon Associate I earn from qualifying purchases.
Builder financing may be enterprise-level, project-specific, borrowing-base, or master/revolving. Lenders may assess the company, project collateral, inventory, construction progress, track record, and expected sale proceeds. For example, Wells Fargo describes entity or enterprise lines, project-specific financing, and borrowing-base facilities for experienced builders; Regions lists builder, master or revolving lines, borrowing-base facilities, land acquisition and development loans, and letters of credit. These examples show possible structures, not terms available to every builder.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Compare the mechanics in the offer
| Decision point | Revolving credit facility | Term loan | What to verify |
|---|---|---|---|
| Access to funds | Repeated draws may be available, subject to the line limit, borrowing-base calculations, and lender controls. A project line may be revolving or non-revolving. | A specified principal amount is advanced and repaid under agreed terms. | Draw notices and approvals, borrowing-base certificates, remaining availability, and whether repayment restores availability. |
| Cash-flow fit | Can align with working capital, project costs, or multiple phases. Interest generally relates to outstanding use, but fees and contract terms also affect cost. | Scheduled payments may suit a known one-time need, but payments can start before project proceeds arrive. | Map sales and customer receipts against construction costs, subcontractor payments, and debt service month by month. |
| Purpose | May cover cyclical or project working capital, depending on the program and lender. | May fund a fixed amount for a defined use; allowable terms can differ between real-estate financing and general working capital. | Confirm permitted use in the loan documents. Distinguish operating working capital from land acquisition and development, and from vertical construction. |
| Maturity and payoff | May require payoff or renewal at maturity; continued availability is not guaranteed. | Has a stated maturity and repayment schedule. | Check amortization, any balloon balance, extension terms and costs, renewal discretion, zero-balance or cleanup requirements, and the planned payoff source. |
| Collateral and oversight | May be secured by business assets, inventory, receivables, land, or project collateral; reporting and draw monitoring may apply. | May also be secured by project or other assets and include covenants and reporting. | Compare collateral scope, guarantees, advance rates, covenants, inspections, draw controls, reporting workload, and lender remedies. |
| Total cost | May include interest on outstanding draws plus commitment, unused-line, monitoring, origination, or other fees. | May include interest and origination or other charges over the agreed term. | Compare offers using the same rate assumptions, draw schedule and expected balance, fees, prepayment terms, extension costs, and payoff date. Do not assume either structure is cheaper. |
What project-sale risk means for repayment
A credit line can bridge project phases, but it does not remove the risk that completed homes take longer to sell or sell for less than expected. A term loan’s scheduled payments can create pressure when sales proceeds arrive late or fall short. In a 2025 SEC-filed annual report, one bank said repayment on its residential builder construction facilities depends on the underlying project’s performance. That bank’s disclosure is not a universal rule or a market-wide maturity standard.
#1 Best Overall

- EASY TO MANAGE - Use this accounting ledger book to track your payments, deposits, and balances, and develop good bookkeeping habits to meet your financial goals.
- UNDATED ACCOUNT TRACK - Use a ledger book to record every expense you make no matter what day it starts. The accounting book is plenty of space to record each transaction you make, and state its number, date, description, account, payment or deposit amount, and total balance.
- HIGH QUALITY - The A5 expense tracker notebook is used to high quality 100gsm pure white paper, brown elastic band and a back pocket for extra space. A total of 64 sheets(128 pages), it comes with 3480 entry lines (29 lines per page, 60sheets/120pages), 1 page Year Overview, 7 lined notes pages.
- MANAGE YOUR FINANCES & SUCCEED - Use this business expense tracker notebook, You will be able to easily analyze your financial activities and quickly prepare accurate financial statements. Use your records to regularly assess your spending and income and find any unnecessary expenses you can cut to improve your financial performance.
- THE PERFECT GIFT - Use account ledger book for your personal or business finances, give it to your friends, colleagues as a gift for Birthday| Easter|Children's Day|Halloween|Thanksgiving|Christmas|Back to school and New Year's Day.
Stress-test the repayment plan against slower sales, construction delays, cost overruns, and rate changes. Identify the actual source of payoff—such as sale proceeds, operating cash flow, or refinancing—and test whether it remains available in a downside scenario. A lender’s expected sale timeline is not a guarantee of sale or refinancing.
U.S. SBA options homebuilders may investigate
SBA does not lend 7(a) funds directly to borrowers; applicants work through participating lenders. Program details and lender participation can change, so confirm the current rules and written terms with SBA and a participating lender.
Rank #2

- AN EASY & EFFICIENT WAY TO CONTROL YOUR FINANCES: Created for both small business and personal use, this horizontal accounting ledger book has spacious pages to log payments and deposits, so that you can monitor your finances and spot errors easily.
- LARGE FORMAT LEDGER WITH PLENTY OF WRITING SPACE: This accounting book ledger comes in a large format, measures 10 by 7 inches, and has 129 pages with 3,100 entry lines total.
- TRACK ACTIVITY IN MULTIPLE ACCOUNTS WITH JUST ONE BOOK: This accounting log book will be perfect if you want to track activity in multiple accounts. To do so, use the dedicated column to add the bank account number every time you make a record.
- PREMIUM DESIGN FOR COMFORTABLE DAILY USE: This accounting journal book has a durable eco-leather hardcover, thick 120gsm paper, sturdy elastic closure, pen loop, ribbon bookmark, and back pocket for extra notes, checks, and receipts.
- 60-DAY MONEY-BACK GUARANTEE: We will exchange or refund your small business log book if you aren’t satisfied with your business bookkeeping ledger for any reason. Reach out to us via message to refund your monthly accounting ledger book.
7(a) Working Capital Pilot
The SBA’s Working Capital Pilot (WCP) page, reviewed October 4, 2026, describes a monitored line-of-credit pilot with a maximum loan amount of $5 million and maturity of up to 60 months. Its eligibility indicators include at least one year of operating history and the ability to produce timely financial statements, accounts-receivable and accounts-payable aging, and inventory reports. These are program indicators, not a guarantee of eligibility or approval.
A March 3, 2026 SBA release about homebuilders says WCP financing may be revolving or non-revolving, project-based, and suited to single- or multi-phase contracts. It identifies direct project costs such as labor, materials, and subcontractors; states a maximum of $5 million and maturity of up to 60 months; and gives a guarantee fee of 0.25% for the first 12 months and 0.275% for each additional 12-month period. Treat those fee figures as the release’s program-specific statement and verify the applicable current fee before acting. SBA Administrator Kelly Loeffler said the program offers builders access to flexible project financing to help them break ground sooner and build efficiently; that is promotional agency language, not an independently measured outcome.
Rank #3
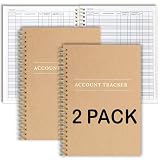
- PERFECT FOR RECORD KEEPING: The 2 Pack account ledger books are versatile and can be used to track finances, budgets, expenses, and other business or personal records. They are perfect for individuals, entrepreneurs, or small business owners who need a reliable and efficient way to keep track of their finances. With 100 pages, customers can record transactions over an extended period, making it a handy tool for financial planning and organization.
- COMPACT AND LIGHTWEIGHT: The account ledger books are compact and lightweight with each book weighing 7 ounces and measuring 8.5 x 6.25 inch, making them easy to carry around. You can take them with them in a bag or briefcase, making them ideal for on-the-go use. This feature ensures that you can access your records at any time, whether you are at work or on the move.
- DURABLE KRAFT COVER: The kraft cover is a distinguishing feature of these account ledger books. It provides a durable layer of protection that can withstand daily wear and tear, making it suitable for long-term use. Additionally, the classic, rustic appearance of the cover gives it a timeless and professional look that can fit in any setting.
- PREMIUM QUALITY: Elegant style with the words ''Account Tracker'' embossed in fancy Gold Foils. The gold coil ring binding is a practical design feature that enhances the functionality of the account ledger books. It allows pages to turn smoothly and easily, making it effortless to flip through the book while keeping pages in place. The ring binding also ensures that pages won't fall out, preventing the loss of vital information.
Builders CAPLine
The SBA’s 7(a) lender resource describes Builders CAPLine as financing for small general contractors constructing or rehabilitating residential or commercial property for resale. It states that maturity must not exceed 60 months plus the estimated time to complete construction or rehabilitation. This description does not establish that every homebuilder, land purchase, development, or project qualifies; ask a participating lender to assess the specific use and borrower.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Questions to take to a lender
- Is the facility project-specific or available across the business, and are draws revolving or non-revolving?
- What triggers draw approval, and what borrowing-base reports, inspections, or other documentation are required?
- Which costs are eligible, and are land, development, construction, and operating expenses treated differently?
- What collateral, guarantees, advance rates, covenants, and reporting obligations apply?
- When does principal repayment start, what is due at maturity, and can the lender require a zero-balance period?
- Are extensions or renewals available at the lender’s discretion, and what do they cost?
- What is the full cost under the builder’s expected draw pattern, including interest, fees, prepayment charges, and extension costs?
- What repayment assumptions are built into the lender’s analysis, and how does the plan hold up if sales or construction take longer than expected?
No reviewed source establishes a market-wide cost or approval-rate winner between revolving facilities and term loans for homebuilders. Rates, fees, eligibility, and terms are borrower- and lender-specific; obtain written offers and professional advice suited to the company and project.
Quick Recap
Best Value
Rank #4

- Easy To Track Your Finances: HAUTOCO accounting ledger book keeps you on top of your expenses and income! Help you keep your money organized, spend well, and set and achieve financial goals
- Premium Material: The A5 accounting ledger book has a total of 120 pages and 2040 lines of entries. It is made of 100gsm thick paper to reduce ink leakage; it is equipped with a waterproof and sturdy PP cover to protect the inner pages
- Practical Design: Compact 8.3 x 6.2'' expense tracker notebook is easy to carry and features information pages, 2025 calendar, yearly financial goals page, and PVC pocket for storing important tickets and loose items
- Manage Your Finances Effectively: Undated accounting books with number, date, description, account, payment or deposit amount, and total balance. You will be able to easily analyze your financial activities and quickly prepare accurate financial statements
- Ideal For Small Business or Personal Use: An accounting log journal can track your business or personal financial status. With a clear record of transactions, you can find unnecessary expenses or fraudulent charges
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Free tools Windows power users keep installed
One-click scans. No signup required.




