RAC Basic Contents Insurance is available to renters in Western Australia, but it is limited-event cover: its core protection is for fire and theft, not every common cause of damage to belongings. The stated maximum contents sum insured is $25,000, and category limits, exclusions, excesses and the policy schedule can reduce what a claim pays. Optional personal valuables cover is a separate extra for eligible items away from home.
What RAC Basic Contents Insurance covers
RAC describes Basic Contents Insurance as contents cover for fire and theft, with new-for-old repair or replacement for items covered by the policy. The applicable PDS defines insured events and conditions; the amount on your policy schedule is the amount insured. The current RAC product page lets renters request a quote online or by phone.
As an Amazon Associate I earn from qualifying purchases.
This is not broad all-events contents insurance. RAC’s Key Facts Sheet, prepared on 12 January 2021, lists flood, storm, accidental breakage, earthquake, lightning, malicious damage, impacts and escape of liquid as events not covered by the basic policy. The KFS is not an insurance contract, and its event summary is older than the current policy documents. Check the PDS and any applicable SPDS and schedule for the terms that govern your policy.
Cover at the insured address and in storage
The PDS describes cover for contents at the insured site when a specified insured event occurs. RAC advertises secure-storage contents cover against fire and theft up to $5,000. The TMD states that contents kept in the open air at the site are limited to $500. These are limits, not a promise that every stored item or theft scenario is covered; policy definitions and conditions still apply.
#1 Best Overall
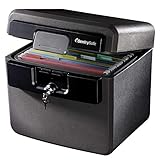
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
Limited cover for tenants’ fixtures and liability
The PDS includes limited cover for qualifying fixtures and structural improvements owned by a tenant, generally up to $5,000 and within the overall sum insured. That does not make this building or landlord insurance.
Tenants also have legal liability cover for qualifying incidents anywhere in Australia, subject to PDS exclusions. The PDS sets a maximum of $20 million for any one event, inclusive of legal costs. This can apply to qualifying damage to a landlord’s property used by the tenant, or bodily injury or damage to someone else’s property. The limit does not remove the need to check the policy’s exclusions and conditions.
Check whether the $25,000 cap and sublimits fit your belongings
RAC states a maximum Basic Contents sum insured of $25,000. The TMD describes four cover levels between $10,000 and $25,000. The maximum is not an estimate of your belongings’ replacement cost: make an inventory and consider what it would cost to replace items covered by the policy. If that value exceeds the available limit, RAC directs customers to consider its broader Contents Insurance.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Category limits can restrict payment even when your overall sum insured is higher. Examples in the PDS include:
- Bicycles and scooters: up to $1,000.
- Computers and associated equipment: up to $5,000 combined.
- Entertainment equipment: up to $7,500.
- Photographic equipment: up to $1,000.
- Tools of trade: up to $2,000.
- Watches and jewellery: up to $2,000 per item or set, and $5,000 in total.
These examples may not reflect the limits on your policy. Check the current PDS and your schedule, particularly if a few high-value items make up much of your contents.
Rank #2

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Personal valuables cover is optional
Personal valuables cover costs extra. RAC describes it as cover for accidental loss or damage to eligible valuables normally kept at the insured address, anywhere in Australia. The PDS identifies possible categories including clothing and luggage, glasses and personal medical equipment, jewellery and watches, portable electronic devices, and sporting or recreational items.
Unspecified and specified valuables
With unspecified cover, eligible items are covered under per-item or per-set limits and a total per-claim limit. The PDS lists options with maximums of $500, $600, $800 or $1,000 per item or set, and $2,000, $3,000, $4,000 or $5,000 per claim. Specified valuables are listed individually on the schedule for their recorded insured amounts. Check which options are currently available, what they cost, whether valuation evidence is required and which exclusions apply.
The PDS excludes some situations, including valuables intentionally left unattended in a public place or in an unlocked or unsecured vehicle. Personal valuables cover is not automatic, and listing an item does not override the policy’s conditions.
Factor in the excess and premium
RAC’s PED Guide, for policies first started on or after 4 October 2024 or renewed on or after 1 November 2024, lists a $200 basic excess for contents and a separate $200 basic excess for personal valuables. If one incident leads to claims under both sections, both excesses can apply.
The guide says premiums depend on factors including site location, sum insured, building construction and age, claims history, payment frequency, operating costs, government charges and discounts. The list is not exhaustive, and premiums are likely to change at renewal. RAC describes alarm and membership discounts, subject to eligibility and minimum-premium rules. Get a quote for your circumstances rather than relying on a typical renter price.
Rank #3

- FIREPROOF: The safe is UL Classified to endure 1/2 hour at 1550°F to protect irreplaceable documents, small valuables, DVDs, and USBs from fire
- WATERPROOF: The safe is ETL Verified for 72 hours of water submersion offering peace of mind in the event of a flood
- COLOR: Dark Gray Color offers a sleek and professional appearance
- MEASUREMENTS: Exterior: 16. 6 in. W x 13. 8 in. D x 14. 1 in. H; Interior: 12 in. W x 8. 1 in. H x 11. 6 in. H; large capacity 0. 66 cubic feet; weighs 41 pounds
- DURABLE: Fireproof lock box features a flat key lock to prevent the lid from opening in the event of a fire; includes two keys
Who may find the basic policy suitable?
RAC’s TMD describes the product as designed for private domestic buildings in Western Australia. Examples of potentially suitable customers include tenants in furnished dwellings, singles in small apartments, residents of self-contained retirement dwellings and strata dwelling owners. The TMD is an indication of intended market, not a substitute for checking eligibility or whether the cover suits your needs.
The TMD flags possible poor fit where contents are not reasonably protected, a home is unoccupied for more than 60 consecutive days, a building is primarily commercial or is undergoing inadequately protected renovation, or a rented house has more than three unrelated occupants. It also flags people seeking business-use valuables cover or cover for valuables left unattended in a public place. The TMD is effective 25 August 2021 and says it should be reviewed no later than every two years; confirm current eligibility and the current TMD with RAC.
How to decide whether it fits
- Estimate replacement value. List the contents you would need to replace and compare the total with your available sum insured, up to $25,000.
- Check item limits. Compare the PDS and schedule limits with the value of bicycles, electronics, jewellery, tools and other high-value categories.
- Match the cover to the events you need. If you want protection for events such as storm, flood or accidental damage, do not assume Basic Contents includes them. Compare the applicable wording with RAC’s broader Contents Insurance and other policies.
- Consider belongings taken away from home. If you need cover for eligible valuables outside the insured address, check the optional personal valuables section, its limits, exclusions and price.
- Work out the effect of the excess. Consider whether you could absorb the $200 contents excess and, if claiming for valuables as well, the separate $200 valuables excess.
- Check the policy documents and eligibility. Confirm occupancy and security requirements, insured events, settlement terms and exclusions in the PDS, applicable SPDS, PED Guide and schedule. Ask RAC about any uncertainty before buying.
RAC says its broader Contents Insurance offers a wider range of events and higher sum insured options. When comparing it or another policy, focus on event cover, replacement value versus limits, category sublimits, portable valuables, excesses, premium and payment conditions, eligibility and claims settlement terms.
Which RAC documents control?
Use the documents that apply to your policy, not a generic summary. RAC’s document index lists the Combined PDS/FSG for policies commencing on or after 25 February 2021, an SPDS for policies commencing or renewed on or after 14 November 2023, and a PED Guide for policies started on or after 4 October 2024 or renewed on or after 1 November 2024. The SPDS, prepared on 28 September 2023, amends the PDS, including provisions on taking reasonable care not to make a misrepresentation and the cooling-off period.
RAC’s insurance documents page is the place to identify the documents for your policy date. Read those documents alongside your schedule; the PDS and applicable SPDS set the contractual cover, while the PED Guide explains premium and excess details. The January 2021 KFS is not a contract and should not replace them.
Free tools Windows power users keep installed
One-click scans. No signup required.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




