Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Intel combines chip design with its own manufacturing operation and is trying to expand Intel Foundry’s external business. NVIDIA sells accelerated-computing platforms whose recent growth is heavily concentrated in Data Center. That gives Intel more direct exposure to factory execution and utilization, while NVIDIA is especially exposed to the pace of AI infrastructure spending, customers’ ability to deploy systems, and export controls. These differences help frame the risks; they do not establish which stock is the better buy.
How do Intel and NVIDIA make money?
Intel: product businesses plus manufacturing
Intel’s Intel Products group designs, develops, markets, sells, supports, and services processors and related products. Its Client Computing and Edge Group (CCPG) serves PCs, edge devices, and related consumer and commercial uses. Its Data Center and AI Group (DCAI) sells x86 workload-optimized products, including CPUs, AI accelerators, networking and infrastructure processors, and ASICs. Intel Foundry manufactures for Intel Products and is also pursuing external foundry customers; Intel uses third-party manufacturers to a lesser extent. Intel’s Q2 2026 Form 10-Q describes these businesses and their segment reporting.
As an Amazon Associate I earn from qualifying purchases.
That structure makes Intel’s investment case depend on two linked questions: whether its products can compete in their markets, and whether its manufacturing operation can execute economically while attracting outside customers. Success in one does not guarantee success in the other.
NVIDIA: accelerated-computing platforms
NVIDIA sells accelerated-computing platforms and products. Its fiscal Q2 2027 results show how much recent revenue growth is associated with Data Center: the company reported $89.0 billion of Data Center revenue out of $96.2 billion total revenue for the quarter ended July 26, 2026. That is about 93% of reported revenue, calculated from those figures. The company reported 75.0% GAAP gross margin for the quarter. NVIDIA’s results release reported these figures.
#1 Best Overall

- Start Your PC Gaming Story With RTX 5060 Performance: The NVIDIA GeForce RTX 5060 delivers smooth 1080p and 1440p gaming with ray tracing and DLSS 4 Multi-Frame Generation — serious hardware for a first PC that refuses to feel like one.
- A Platform Built to Perform and Scale: The Intel Core i7-14700F and 32GB DDR5 RAM keep the RTX 5070 running at peak performance — smooth, stutter-free gameplay whether you’re gaming, streaming, or multitasking at full load.
- The Prebuilt That Grows With You: Built on standard, off-the-shelf components, upgrading your storage, RAM or GPU down the line is always a straightforward next step — no tech expertise required.
- Four-Fan Cooling Built for Marathon Sessions: A dedicated RGB CPU Air Cooler and four-fan airflow system maintain consistent temperatures throughout every session, so your performance at hour one is identical to hour five.
- WiFi 6E, MSI Center and Windows 11 Home Included: WiFi 6E delivers lower latency on the less congested 6GHz band, while MSI Center puts full control of RGB, fan curves and performance profiles in one beginner-friendly dashboard.
NVIDIA’s quarterly growth is not, by itself, evidence that the same pace will continue. Its own filing describes constraints between customer demand and actual deployment: customers need data-center land, power, facilities, and capital to put systems to work.
What do the latest reported figures show?
The figures below come from different fiscal quarters and different segment structures, so they indicate scale and exposure rather than a like-for-like performance comparison. Intel’s quarter ended June 27, 2026; NVIDIA’s fiscal quarter ended July 26, 2026.
Rank #2
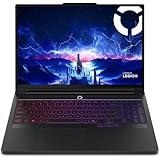
- Processor - Intel Ultra 9 275HX, 24C (8P + 16E) / 24T, P-core 2.7 / 5.4GHz, E-core 2.1 / 4.6GHz, 36MB
- Operating System - Windows 11 Pro 64
- Graphic Card - NVIDIA GeForce RTX 5090 24GB GDDR7, TGP 175W
- Memory - 64 GB DDR5-6400MHz (CSODIMM) - (2 x 32 GB)
- Storage - 2 TB SSD M.2 2280 PCIe Gen4 TLC (2 x 1 TB)
| Company and period | Reported results | How to read them |
|---|---|---|
| Intel, Q2 2026 | $16.128 billion consolidated revenue; $1.796 billion consolidated operating income | Company-wide results for the quarter ended June 27, 2026. Intel Form 10-Q. |
| Intel Products, Q2 2026 | $15.139 billion revenue before intersegment eliminations: $8.877 billion CCPG and $6.262 billion DCAI | These are segment figures before eliminations; do not add them to consolidated revenue as though they were separate external sales. Intel Form 10-Q. |
| Intel Foundry, Q2 2026 | $5.765 billion segment revenue and a $2.089 billion segment operating loss | Segment revenue includes intersegment activity, so it is not equivalent to external-customer foundry sales. Intel Form 10-Q. |
| NVIDIA, fiscal Q2 2027 | $96.2 billion total revenue, up 106% year over year; $89.0 billion Data Center revenue, up 117% year over year | Reported for the quarter ended July 26, 2026. NVIDIA results release. |
What is Intel’s main investor risk?
Manufacturing execution and foundry adoption
Intel’s manufacturing strategy requires it to develop process technology, bring capacity online, achieve useful yields and utilization, and secure customer demand sufficient to support the investment. A technology milestone matters, but it is not the same as proof of profitable external foundry scale. Investors can distinguish progress on the technology roadmap from evidence of customer design wins, production volumes, utilization, margins, and returns on capital.
Recommended Free Tools
Intel reported that 18A entered high-volume production at the start of 2026, that 18A-P entered risk production in June 2026, and that development of 14A continued. The company’s Q2 materials also identify external demand commitments, manufacturing expansion, and product design wins as uncertainties. These are milestones and plans, not a guarantee of customer adoption or acceptable economics. See the Q2 2026 Form 10-Q and Q2 2026 results release.
Rank #3

- [144Hz FHD anti-glare display]: 15.6" diagonal, FHD (1920 x 1080), 144 Hz, IPS, micro-edge, antiglare; Reduce frustrating lag and image ghosting with a display that combines a 144Hz refresh rate and 1080p Full High Definition resolution for smooth, crisp gameplay.
- [Gaming Processor]: Intel Core i5-13420H, 4 P-Cores, 4 E-Cores, Total 12 Threads, Up to 4.6GHz, Intel UHD Graphics; 13th Gen Intel Core processor distributes performance where you need it the most — saving you time and increasing your ability to do the things you actually want.
- [Memory& Hard drive]: 16GB high-bandwidth RAM to smoothly run multiple applications and browser tabs all at once, 512GB Solid State Drive ideal for faster bootup and data transfer.
- [Features]: w/256gb 9H docking station; Windows 11 Pro; Backlit Keyboard; NVIDIA GeForce RTX 4060 Laptop GPU, 8GB GDDR6, Up to 1470MHz Boost Clock 45W Maximum Graphics Power with Dynamic Boost.
- [Communications]: 1 x USB-C, 3 x USB-A, 1 x HDMI, 1 x RJ45, 1 x Headphone/Microphone combo; Intel Wi-Fi 6E, Bluetooth 5.3.
Manufacturing and research and development are capital-intensive, and capacity decisions have long lead times. If demand, product competitiveness, or external customer commitments fall short of what the business needs, investment can weigh on results rather than produce the intended scale benefits. Intel also faces product competition, demand and margin risks, supply constraints, and competition for foundry customers.
Global operations and supply exposure
Intel’s manufacturing footprint and suppliers create exposure to physical disruption as well as trade policy. Its filings identify supplier concentration in Taiwan and risks to Israeli manufacturing and development operations. Geopolitical conflict, tariffs, trade restrictions, export controls, or supply interruption could affect costs, production, or sales; no particular outcome is certain. The company discusses these exposures in its Q2 2026 filing and results release.
Rank #4

- GPU Memory Size: 16 GB GDDR6 with ECC
- Form Factor: 2.7"(H) x 6.6"(L), dual slot, half height.
- Thermal Solution: Blower Active Fan
What are NVIDIA’s main investor risks?
AI infrastructure demand has to become deployed demand
NVIDIA’s growth relies on customers continuing to spend on accelerated computing and building facilities where those systems can be installed. Its Q2 2027 Form 10-Q says customers may delay purchases when land, power, data-center facilities, or financing are unavailable, or when adoption is slower than anticipated.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Supply commitments are another part of this equation. NVIDIA reported $279 billion in supply and capacity commitments as of July 26, 2026, up from $119 billion in the prior quarter. Those commitments are intended to help meet expected demand, but the filing says commitments may be difficult to reduce if demand or customer plans change. A large commitment figure is therefore neither revenue already earned nor proof that expected purchases will materialize. NVIDIA’s fiscal Q2 2027 Form 10-Q discusses the commitments and deployment risks.
Best Value

- NVIDIA Blackwell Architecture The Ultimate Platform for Gamers and Creators Tensor Cores Max AI Performance with FP4 and DLSS 4 NVIDIA Reflex 2 with Frame Warp Full Ray Tracing with Neural Rendering
- VIDEO CARD
- NVIDIA
Export controls can change market access
Rules governing advanced-computing products can change, and their scope is not fixed. Restrictions may limit products or distribution, add compliance costs, create inventory or supply charges, or shift opportunities toward competitors whose alternatives are less likely to be restricted. NVIDIA’s Q3 fiscal 2027 revenue outlook was $108.0 billion, plus or minus 2%, and did not assume Data Center compute revenue from China. That is management guidance, not a realized result or a permanent statement about access to the market. The company’s results release and Form 10-Q describe the outlook and export-control risks.
How should investors compare the two risk profiles?
| Question to monitor | Intel | NVIDIA |
|---|---|---|
| What drives results? | Client and edge demand, data-center and AI products, product transitions, and manufacturing economics. | Accelerated-computing demand, with recent reported growth concentrated in Data Center. |
| What is the central execution test? | Progress on process nodes and competitive products, plus external foundry customers at viable economics. | Whether customers sustain spending and can deploy increasingly complex AI systems. |
| Where does capital and capacity risk sit? | In long-lead-time manufacturing investment, yields, utilization, and matching factory capacity to demand. | In supply and capacity commitments, alongside customers’ need to finance and build deployment infrastructure. |
| How can geopolitics affect the business? | Through global manufacturing and supplier exposure, trade restrictions, and potential physical disruption. | Through export licensing and restrictions that can constrain advanced-computing sales and market access. |
These are different channels of risk, not a ranking. Intel’s foundry activity makes factory execution a direct part of its business thesis; NVIDIA’s recent revenue mix makes AI infrastructure demand particularly consequential. Both face competition and can be affected by policy, supply, and demand changes.
Do these business differences say which stock is better?
No. Company performance and stock attractiveness are separate questions. A company can grow quickly and still be priced too optimistically; a business facing execution problems can still outperform if expectations are low enough. The figures and disclosures here do not establish a current valuation, comparative expected return, or investor-specific recommendation. For a stock decision, an investor would also need to assess price, future cash flows, risk tolerance, and portfolio context rather than infer a buy or sell conclusion from business models alone.
Free tools Windows power users keep installed
One-click scans. No signup required.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




