Build your emergency fund around what essential bills and likely emergencies cost now—not a fixed dollar figure that quietly loses buying power. Start with a reachable savings goal, add to it consistently, keep the core reserve accessible in an appropriately insured account, and revisit the target when your costs or circumstances change. A higher account rate may help, but it is not a promise that your savings will keep pace with inflation.
How much should your emergency fund hold?
There is no single reserve amount that fits every household. The Consumer Financial Protection Bureau (CFPB) recommends considering your own circumstances and the unexpected expenses you have faced; it also says starting with a small amount can help. Its emergency fund guide defines the fund as cash set aside for unplanned expenses or financial emergencies.
As an Amazon Associate I earn from qualifying purchases.
To set a practical starting target, total your essential monthly costs—such as housing, utilities, food, transportation, insurance, and minimum debt payments—then consider the size of plausible shocks. A car repair, medical bill, home repair, or period without income may call for a different cushion depending on your household. The target should reflect both the bills you must keep paying and the risks you need the reserve to absorb.
The FDIC advises considering a fund covering at least six months of living expenses. Treat that as a rule of thumb, not a universal requirement: CFPB guidance stresses that the appropriate amount depends on individual circumstances. If six months feels out of reach, choose a smaller first milestone and build from there.
#1 Best Overall

- Cash Envelopes System:1pcs PU leather money saving binder,8pcs A6 6-holes binder pockets,12pcs expense budget sheets,3 sheets of category sticker labels,Budget binder with cash envelopes perfect for you to save money.
- PU Leather Binder:Cash binder has attractive double-colors cover,Premium PU leather A6 binder has many hidden compartments and pen hoops,which is convenient for storing pen, passports, ID cards, bank cards.
- Binder Pockets:8PCS A6 zipper cash envelope made from superior material. It is resists tearing and acid-free which can protect your items from water and dust.As cash envelopes is convenient for storing money, cards, stamps, tickets, pens.
- Category Stickers & Budget Sheet: Money binder with category stickers and budget sheets can help you organize your expenses and track your deposits and withdrawals and achieve budget goals.
- Easy to Carry:A6 Binder Budget Envelopes System fits in your handbag, backpack,suitcase or desk;A6 ring binder suitable for all standard A6 size inner pages.
How to build the fund steadily
1. Set a first milestone and a larger target
Write down an initial amount you can realistically reach, followed by the fuller reserve you are working toward. A modest first cushion can provide some protection while you continue saving. If your income is irregular or your budget is tight, a small contribution still moves the balance in the right direction; difficulty saving is not a reason to abandon the goal.
2. Pick a contribution trigger that fits your income
For stable pay, consider a recurring transfer or splitting part of your paycheck into savings. With uneven income, choose an amount or percentage to move when money arrives, while leaving enough in checking for near-term bills. When you receive a tax refund or another lump sum, you may decide to direct a portion to the reserve.
Rank #2

- 【100 Envelopes Money Saving Challenge】100 Envelopes Money Saving Challenge Interesting Motivation to Complete 100 Day Challenge You Can Save $5050
- 【A5 Money Saving Binder】1Pcs PU leather a5 binder 25pcs 6-hole cash envelopes pre-printed with 1-100 1 sheet tracker of $1 to $100.Can help you establish an emergency savings fund
- 【100 Envelope Challenge Binder】100 Envelope Challenge Binder 1 to 100 waterproof tear resistant storage and protection for your money.A5 size can easily fit into backpacks and crossbody bags for easy carrying
- 【Savings Binder】Savings Binder is a practical gift that can help friends and family start their savings goals in a fashionable and convenient way
- 【Our Service】Thank you for your trust in NICOOTH Envelope Savings Challenge Book.
Before setting an automatic transfer, check your checking-account balance and bill schedule. A transfer that arrives before income—or leaves too little for a scheduled payment—can cause an overdraft fee. The CFPB recommends setting a specific goal, saving consistently, and monitoring progress; it discusses automatic transfers and one-time deposits in its guidance on starting small and saving up.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →3. Track progress and update the target
As prices rise, the same balance may cover fewer weeks of essential expenses. Recalculate your target using current bills and realistic emergency costs when those costs change, or when your household, income, or obligations shift. That review habit is a practical way to keep the fund aligned with its purpose; the CFPB does not prescribe a particular review schedule.
Rank #3

- Cash Envelopes System:1pcs PU leather money saving binder,8pcs A6 6-holes binder pockets,12pcs expense budget sheets,3 sheets of category sticker labels,Budget binder with cash envelopes perfect for you to save money.
- PU Leather Binder:Cash binder has attractive double-colors cover,Premium PU leather A6 binder has many hidden compartments and pen hoops,which is convenient for storing pen, passports, ID cards, bank cards.
- Binder Pockets:8PCS A6 zipper cash envelope made from superior material. It is resists tearing and acid-free which can protect your items from water and dust.As cash envelopes is convenient for storing money, cards, stamps, tickets, pens.
- Category Stickers & Budget Sheet: Money binder with category stickers and budget sheets can help you organize your expenses and track your deposits and withdrawals and achieve budget goals.
- Easy to Carry:A6 Binder Budget Envelopes System fits in your handbag, backpack,suitcase or desk;A6 ring binder suitable for all standard A6 size inner pages.
Where to keep emergency savings
The core reserve should be accessible when an urgent bill arrives. A dedicated bank or credit-union account can help keep the money separate from everyday spending; confirm how quickly you can withdraw or transfer funds, including any access restrictions. The CFPB describes bank and credit-union accounts as offering access such as ATM withdrawals in its savings account overview.
Compare an account’s practical terms, not just its advertised rate:
Rank #4
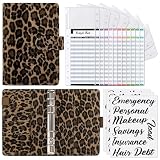
- What You Get: 1Pcs PU leather money saving binder,8pcs 6-hole A6 binder pockets,12pcs expense budget sheets, and 3 sheets of category sticker labels to ensure all your money is neatly organized and easily accessible.
- Stylish Budget Binder: This savings binder features a leopard print cover design that adds a touch of fashion to your financial planning. In addition, it has many hidden compartments and pen hoops, which are convenient for storing pens, receipts, and cards.
- Cash Envelopes for Budgeting: This budget binder with 8pcs cash envelopes that are made from durable material. It resists tearing and is acid-free which can protect your items from water and dust. Cash envelopes are convenient for storing money, stamps, tickets, and pens.
- Category Stickers & Budget Sheet: Money saving binder with category stickers and budget sheets can help you plan your expenses and track your deposits and withdrawals and achieve budget goals.
- Easy to Carry: A6 binder organizer fits in your handbag, backpack, or desk; the A6 ring binder is suitable for all standard A6 size inner pages. So, It is perfect for on-the-go financial planning.
- Access: Check withdrawal options and how long transfers take. Confirm the terms with the institution.
- Protection: Verify whether the institution and account are FDIC- or NCUA-insured and how your ownership category and balances affect coverage. The CFPB explains that FDIC insurance protects eligible deposits up to $250,000 per individual account holder if an insured bank fails; coverage rules apply, and not every financial product is an insured deposit.
- Costs and conditions: Review monthly fees, minimum balances, and withdrawal or transfer limits. Providers may charge fees for excessive transactions or for falling below balance requirements, as the CFPB notes in its withdrawal-limit explanation.
- Rate variability: Compare the current rate and how it can change, but do not assume a savings yield will reliably match inflation. Rates vary, and access and account terms matter alongside return.
Why I bonds are not a substitute for ready cash
Series I savings bonds adjust their rates every six months based on inflation, according to TreasuryDirect. For bonds issued from May 1 through October 31, 2026, TreasuryDirect lists a 4.26% composite rate, including a 0.90% fixed rate; that rate applies only to that issue window and may change afterward.
Recommended Free Tools
Liquidity is the key limitation for emergency planning: I bonds cannot be redeemed during their first 12 months. If redeemed before they have been held for five years, the last three months of interest are forfeited. They may suit a secondary holding for some savers, but they are not cash available on demand and should not replace the accessible core reserve.
Best Value

- Upgraded Envelope Savings System: The value pack Includes everything you need - an A6 binder, 8pcs cash envelopes, expense sheets, challenge game cards, yearly overview, labels and various custom stickers. By effortlessly managing your money, quickly pay off debt and save towards big purchases.
- Motivational & Gamified Challenge: Check out this money saving binder, you can set savings goals using the challenge game cards ( $1000 Savings Challenge, Vacation and Christmas Plan). It becomes more enjoyable to draw the corresponding number when you have saved that amount.
- Effective Cash Allocation: Provide one sheet of blank labels and category stickers to choose from. Stick a blank label or category sticker on the envelope, and push the cash and expense sheet in the corresponding envelope. Easy to allocate your money to different categories.
- Additional Budget Accessory: A yearly overview and instruction are included. The yearly summary helps you review progress monthly to compare financial health. Every step and practice tip are detailed in the instruction, which help you quickly understand how to use it, and enjoy the process of saving.
- All-In-One Savings Binder: Provides a location for organizing your finances, easily tracking your spending, identifying areas where you can cut back and save for a long-term budgeting plan. Organized but not bulky, easy to carry on the go.
When to use the fund—and what to do next
Use it for an unplanned, necessary expense or a financial shock, such as an urgent repair, medical bill, or loss of income—not a predictable cost that belongs in the regular budget. The CFPB cautions that borrowing to handle such shocks can add interest and fees. If you draw down the reserve, resume contributions when your cash flow allows so the fund can recover.
What the $400 emergency statistic does—and does not—say
In an August 2019 post, the CFPB reported Federal Reserve Board findings from the 2019 Survey of Household Economics and Decisionmaking: 39% of American adults would not have paid a $400 emergency expense from their own liquid savings; 27% would have sold something or borrowed, and 12% said they could not cover it at all. These are historical 2019 results, not an estimate of current conditions. They illustrate why even an initial reserve can matter, but they do not establish the right target for an individual household.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →



