Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsChina’s digital yuan, or e-CNY, is digital fiat issued by the People’s Bank of China (PBOC), not a privately issued cryptocurrency. It is designed to make digital payments more accessible and flexible, while its centralized issuance, wallet rules and legally permitted traceability give public authorities a substantial role in the payment system. The PBOC calls the privacy approach “managed anonymity”; that is not the same as unconditional anonymity.
What the digital yuan is
The e-CNY is the digital form of China’s fiat currency. The PBOC positions it principally as M0—the most liquid component of the money supply—and intends it to coexist with physical renminbi. Unlike a commercial-bank deposit, it is a central-bank liability. Unlike a cryptocurrency, it is not issued through a private network.

As an Amazon Associate I earn from qualifying purchases.
The PBOC issues e-CNY and sits at the center of a two-tier operating model. Authorized commercial banks and other institutions provide exchange and circulation services to the public. Its official design combines account-based, quasi-account-based and value-based forms, with a loose link to bank accounts. The PBOC has also described it as legal tender subject to cash-related management rules and applicable anti-money-laundering and counter-terrorist-financing requirements.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallCrashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWhat access and convenience the design aims to provide
The PBOC presents e-CNY as a way to support convenient, low-cost payments and reduce reliance on conventional bank-account access. Its design includes multiple wallet forms and tiers with different transaction and balance limits. Official materials also describe hardware wallets, including cards and wearables, as options for people for whom using a smartphone is inconvenient. These are design goals and documented pilot examples—not evidence that every user has gained better access or that every hardware form is currently available to buy.
#1 Best Overall

- Proven security at scale: Over 9 years and millions of cards issued with no known remote hacks, while military‑grade EAL6+ security keeps your private keys locked inside the chip. Your cryptocurrencies stay strongly protected from online attackers.
- Tap once to manage your entire crypto wallet across 90 blockchains - no USB cables or Bluetooth, no batteries, no setup. Access 14,100+ coins & tokens, DeFi, NFTs, and staking instantly from your phone
- Smart backup: Use your second Tangem Wallet as your Backup keys with end‑to‑end encryption; no more papers, pictures. If one card is lost, the remaining can still restore full access, with an optional seed phrase available for advanced users.
- Engineered to last up to 25 years: Waterproof (IP69K), shockproof and tested for extreme temperatures from −25°C to 50°C. A durable cold wallet with long‑term protection and independently audited security.
- Trusted by 6 million users worldwide - buy, sell, swap, stake, and spend cryptocurrency directly. The secure offline storage wallet designed for how people actually use crypto wallets
Reported pilot uses have included transport, retail, catering, utilities, government services, tax collection and subsidies. A Zhejiang regional report also described transport-code use, public-payment applications and elderly-care hardware-wallet scenarios. These examples illustrate the range of uses explored in pilots; they do not establish universal acceptance.
How e-CNY differs from cash and private payment apps
The most useful distinction is who issues the money and governs the payment instrument. The PBOC’s materials establish the e-CNY’s official design, but do not provide a current, comprehensive comparison of private payment apps, merchant acceptance, fees or consumer protections. The table therefore separates what is established about e-CNY from questions that cannot be answered generally from those materials.
Rank #2

- Proven security at scale: Over 9 years and millions of cards issued with no known remote hacks, while military‑grade EAL6+ security keeps your private keys locked inside the chip. Your cryptocurrencies stay strongly protected from online attackers.
- Tap once to manage your entire crypto wallet across 90 blockchains - no USB cables or Bluetooth, no batteries, no setup. Access 14,100+ coins & tokens, DeFi, NFTs, and staking instantly from your phone
- Smart backup: Use your second Tangem Wallet as your Backup keys with end‑to‑end encryption; no more papers, pictures. If one card is lost, the remaining can still restore full access, with an optional seed phrase available for advanced users.
- Engineered to last up to 25 years: Waterproof (IP69K), shockproof and tested for extreme temperatures from −25°C to 50°C. A durable cold wallet with long‑term protection and independently audited security.
- Trusted by 6 million users worldwide (4.9 App Store, 4.8 Google Play) - buy, sell, swap, stake, and spend cryptocurrency directly. The secure offline storage wallet designed for how people actually use crypto wallets
| Comparison point | e-CNY | Cash | Private payment apps |
|---|---|---|---|
| Issuer or instrument | Digital fiat issued by the PBOC; principally positioned as M0. | Physical renminbi, which the e-CNY is intended to complement. | Not established by the PBOC e-CNY materials as a class; provider and underlying payment arrangement vary. |
| Account dependence | Designed with loose linkage to bank accounts and multiple wallet forms. | No digital account is needed to hand over banknotes or coins. | Not established as a general comparison in the cited official materials. |
| Privacy and traceability | The PBOC describes “managed anonymity”: small-value anonymity and large-value traceability according to law, with wallet tiers and financial-crime controls. | The cited e-CNY materials do not provide a full comparison of cash privacy in practice. | Not established as a general comparison in the cited official materials. |
| Offline or hardware options | Official materials describe hardware-wallet forms and online and offline use cases; availability for every user is not established. | Can be exchanged directly without a digital payment device. | Not established as a general comparison in the cited official materials. |
| Acceptance, fees and protections | Pilot examples cover several sectors, but current comprehensive acceptance, fee and protection comparisons are not established. | Not quantified in the e-CNY materials. | Not established as a general comparison in the cited official materials. |
Is the digital yuan anonymous?
No—not in every transaction. The PBOC describes the policy as “managed anonymity,” summarized as “small-value anonymity, large-value traceability according to law.” Wallet categories have different limits, and the official policy materials describe anti-money-laundering rules, risk monitoring, and registration or reporting requirements for large-value or suspicious activity.
The PBOC’s 2021 white paper says the system was designed with personal-information protection in mind and describes safeguards and data minimization. It also says the bank was working to improve institutional arrangements and explore rules to strengthen personal-information protection. These are official descriptions and plans, not independent audits of how every data-access decision works in practice. The public materials cited here do not fully establish who can access each type of transaction information, under what operational process, or how that access is reviewed.
Where state control enters the design
The PBOC’s role in issuance, together with authorized distribution, wallet governance and regulatory reporting, gives public authorities a formal place in the payment infrastructure. That concentration of governance follows from the official architecture; it is not a claim that every transaction is personally inspected. The PBOC frames its approach in terms of monetary sovereignty, legal-tender integrity, security and orderly circulation.
The practical trade-off is that the same central coordination intended to support consistent rules and compliance also places the system’s core governance within public institutions. How that balance affects an individual depends on wallet tier, transaction and applicable legal controls; the official materials do not settle every operational privacy question.
Rank #4

- EAL5+ CERTIFIED SECURE ELEMENT + FINGERPRINT PROTECTION — Your private keys stay encrypted offline on a certified EAL5+ chip, the same security tier used in EMV bank cards. Built by DCENT, securing crypto since 2018. Fingerprint authentication adds a second layer no PIN-only wallet can match.
- 10,000+ ASSETS NATIVE ON 100+ BLOCKCHAINS — Hold Bitcoin, Ethereum, XRP, Solana, Cardano, popular stablecoins (USDT, USDC), and NFTs in one wallet. No third-party apps, no fragmented setup — every supported asset works straight out of the box.
- TAP-TO-SIGN MOBILE EXPERIENCE — Pair your wallet with the DCENT mobile app over Bluetooth. Manage tokens, review transactions, and access in-app swap features directly from your phone — no cables, no desktop required.
- WEB3 & dAPP ACCESS VIA METAMASK — Connect to MetaMask and other browser extension wallets to manage NFTs, claim airdrops, and access dApps. A large screen and intuitive 4-button interface keep every transaction clearly visible before you sign.
- SEAMLESS FIRMWARE UPDATES & 30-DAY MONEY-BACK GUARANTEE — Apply security updates without resetting your wallet or migrating funds. Backed by Amazon's 30-day money-back guarantee — your purchase is risk-free.
What adoption figures do—and do not—show
Reported figures need their date, geography and measurement attached. Wallets opened are not the same thing as unique active users, and transaction amount is not necessarily consumer spending.
Recommended Free Tools
| Report and scope | Reported figures | How to read them |
|---|---|---|
| PBOC pilot figures as of June 30, 2021 | More than 1.32 million scenarios; more than 20.87 million personal wallets and 3.51 million corporate wallets opened; 70.75 million transactions; approximately RMB 34.5 billion in transaction value. | A dated nationwide pilot snapshot, not a current national adoption total or a count of unique active users. |
| PBOC Zhejiang branch report for 2023, published in 2024 | 35.26 million wallets; 183 million transactions; RMB 647.8 billion in transaction amount; separately, RMB 50.9 billion in consumer spending. | A regional report. Transaction amount and consumer spending are distinct measures, and these figures are not directly comparable with the nationwide 2021 pilot snapshot. |
These figures document pilot activity and specific regional use. They do not show that e-CNY has displaced cash or become China’s dominant national payment method.
Best Value
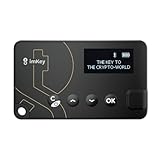
- Top-Tier Security Chip, Bank-Grade Asset Protection: Equipped with an industry-leading Infineon CC EAL 6+ certified security chip, also certified by EMVCo, this chip is widely used in bank payment and identity verification systems. Your private keys are generated and stored entirely offline within the chip, ensuring they never touch the internet. This physically blocks remote hacker attacks and eliminates the risk of private key leakage, building an impregnable first line of defense for your digital assets.
- What You See Is What You Sign, Hardware Button Protection: Every transaction requires manual confirmation via physical buttons on the imKey Pro's clear display. The device intuitively shows key transaction details like the amount and address, ensuring the data hasn't been tampered with during transmission—truly achieving "What You See Is What You Sign." It also features secure PIN code protection and a self-destruct mechanism after multiple incorrect attempts (the private key is wiped after 5 consecutive wrong entries), effectively preventing brute-force attacks even if the device is lost.
- Comprehensive Multi-Chain Asset Support, Access the Web3 Ecosystem: Fully supports major mainnets and Layer 2 networks, including Bitcoin (BTC), Ethereum (ETH), LTC, ATOM, FIL, TRX and more. By adding custom RPCs, you can easily access all EVM-compatible chains like BSC, Polygon, and Avalanche. Furthermore, imKey Pro perfectly supports Layer 2 solutions such as zkSync and Arbitrum, as well as the display and storage of NFTs, meeting all your diverse on-chain needs.
- Cold & Hot Wallet Separation, A Seamless Experience: Utilizing Bluetooth 4.1 wireless technology, it pairs seamlessly with the imToken App on your mobile phone or browser extension wallets on your PC without needing any cables. It combines the ultimate security of a cold wallet (offline private key storage) with the convenience of a hot wallet (online interaction). When a transaction is needed, you sign it offline with your imKey, and the app broadcasts it to the chain. This guarantees asset security without sacrificing the fluidity of use.
- Extremely Thin and Light, A Portable Digital Vault: The device is smaller than a credit card, measuring just 2.3mm thick and weighing approximately 17g. Crafted with a zinc alloy body and a PC panel, it offers a premium feel and is extremely portable. The built-in 33mAh lithium-polymer battery provides a battery life of up to approximately four weeks on a single charge. The package includes the hardware wallet, a USB cable, and mnemonic cards, making it ready to use right out of the box—a secure and reliable gateway to the crypto world.
What the current policy direction says
A 2025 PBOC-led Action Plan calls for e-CNY to be promoted actively and prudently. It also sets out priorities for efficient and secure payment infrastructure, data and network security, supervision, financial-consumer protection and the continued availability of necessary cash services. The plan sets broader digital-finance objectives through the end of 2027. It signals continued policy development and promotion; it does not, by itself, establish a nationwide launch date or confirm that rollout is complete.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




