Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errorsYes—changing CVVs can make stolen card details less useful for online purchases, but they do not prevent every kind of card fraud. A dynamic CVV (also called a dynamic CVC or dCVV2) is a security code that changes according to an issuer’s schedule or after a qualifying transaction. During authorization, the issuer checks whether the submitted code is currently valid. An exposed, expired code should then fail when a criminal tries to reuse it.
What a changing CVV actually protects
CVV2/CVC2 is primarily used to verify card-not-present transactions, such as online and telephone purchases. In Visa’s model, a cardholder receives a current code from the issuer and enters it in the same field used for an ordinary CVV2. The issuer stores the dynamic values and validates the submitted code when the transaction is authorized. Visa’s dCVV2 service lets an issuer request between one and 24 codes at a time.
As an Amazon Associate I earn from qualifying purchases.
The security benefit is limited but concrete: stealing a card number, expiration date and one code does not necessarily give an attacker a permanently reusable CVV. A code that has expired or has already been replaced is intended to lose its value.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →“Dynamic” does not always mean every few minutes
There is no single change interval. Westpac says the CVC on its digital cards changed every 24 hours. The Secure Technology Alliance’s July 2020 technical paper describes time-based designs with intervals from 15 minutes to 24 hours, depending on issuer policy.
#1 Best Overall

- SECURE YOUR WALLET FROM e-PICKPOCKETING: Prevent potential identity and financial theft through your contactless cards. This is the simplest and most effective prevention solution! Block RFID and NFC signals, protect your personal information, and enjoy peace of mind wherever your travels or business take you.
- JAMMING CHIP: An antenna and jamming chip makes up the main components of the card. The antenna will sense incoming radio waves and draw power for the chip to create a jamming signal. Lifetime usage as the card does not require battery.
- BROAD WORKING DISTANCE: With a 2.4” working distance, your entire wallet stays protected. The premium RFID blocking card helps secure cards within 1.2” on either side, providing reliable protection against electronic pickpocketing.
- ULTRA-THIN & COMPACT: At the size of a standard credit card and at only 0.03” thick, the card will fit into any wallet, purse or card case. Keep your wallet compact with no added bulk from this card. Best for travel, business, and everyday use.
- TEST THE CARD: Test the card is working at your local supermarket. At the self-service checkout machines, combine the card and a contactless card on the payment reader. Payment with the contactless card will be blocked and an error message should occur on the reader.
Some designs use a physical card with a battery and real-time clock that must remain synchronized with a verification service. Another approach integrates the update with an EMV chip transaction: the card-present terminal supplies power and the code changes after an eligible chip transaction. These are technical architectures, not proof that a particular card is currently sold or available to consumers.
How an issuer-delivered dynamic code works
- The issuer generates codes. A bank requests a set of dynamic CVV2 values through its payment-network service; Visa documents requests for one to 24 values.
- The customer receives the current value. The issuer may show a valid code in its mobile-banking app or digital-card interface.
- The shopper enters it normally. Visa says the code is used in the same way as a standard CVV2 during a card-not-present checkout.
- Authorization checks the value. The issuer validates the code associated with the transaction. Older or expired values are designed to fail.
Visa describes the service as globally available to issuer banks, but that does not mean every bank, country or card product supports it. Availability is an issuer and product decision.
Rank #2

- Advanced RFID secure sleeve designed to protect credit cards, money cards, identification cards from electronic fraud or theft; RFID shields are a superb debit card protector, RFID blocking to provide superior travel security.
- Made from special RFID blocking material, this credit cards holder is thin and lightweight. certified secure sleeves for credit cards protect against scanning of digital and electronic chips by thieves, tear- and water-resistant
- RFID sleeve with electronic armor is the identity theft protection for your bank cards. this credit card and ID holder prevents electronic access to your cards. valuable credit card protection, an ID card protector. RFID to block scanning and skimming
- Credit card protection sleeve designed with color coding system to find each card easily and quickly. RFID credit card holder have different colors for superior convenience. the special high quality rigid aluminum foil coating of these tiny slim RFID blocking wallets ensures you will never be a victim of high-tech crime
- Includes 12x RFID credit card protector sleeves for ultimate fraud prevention and travel safety
What the available fraud evidence shows
Westpac reported that its digital-card feature reduced fraud incidence for the average customer using the feature by 80 percent. The bank announced that result on June 24, 2022, after introducing the feature in early 2020. Westpac also said about 10,000 customers used the digital security tool daily and that it appeared in roughly five percent of eligible transactions at that time.
Those figures are a bank-reported outcome, not an independent controlled estimate. The release does not establish how much of the reduction came from the changing CVC itself rather than other fraud controls, customer behavior or changes in the fraud environment. It should not be generalized to every issuer, market, cardholder or fraud category.
Rank #3
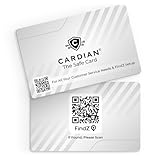
- Stop Digital Theft Instantly: Protect your credit cards, debit cards, passports, and IDs with Cardian’s advanced smart NFC and RFID card blocking technology—keeping hackers and skimmers out of your wallet
Westpac Chief Digital Officer Jason Hair called the feature “another layer of protection” and said it had been “a game changer” for the bank’s customers. Head of Fraud Ben Young said customers could use a digital card “in all the same places” as traditional cards, including recurring payments, while changing codes made stolen details harder to use. Both statements appear in Westpac’s June 24, 2022 press release and represent the bank’s promotional description of its product.
Dynamic CVV versus EMV 3-D Secure
A changing security code and EMV 3-D Secure solve related but different problems. EMV 3-D Secure is a protocol in which merchants and issuers exchange transaction, payment-method and device information so the issuer can authenticate the shopper and assess the transaction.
Rank #4

- RFID Protection: An electromagnetically opaque layer helps block unauthorized scans, protecting credit card, debit card, and passport information from nearby readers; This RFID blocking card helps prevent digital skimming by shielding your wallet from electronic theft
- Threats Stay Outside: Digital pickpockets use hidden readers to skim contactless cards in crowds, transit and checkout lines; This credit card protector works as an RFID blocker the moment it's placed in your purse or wallet, stopping electronic theft before it occurs
- Invisible Yet Active: Ultra-thin and sized to fit any wallet slot, this rfid blocking card adds no bulk; Invisible protection helps shield your debit cards and IDs from electronic skimming without changing the way you carry your wallet
- One Card Protects All: Forget slipping every card into a separate RFID sleeve, just one RFID blocking card protects every contactless card, passport, and license all at once; Carry it in a purse, travel pouch or cardholder and stay shielded at airports, transit hubs and during daily commutes
- Drop and Defend: Keep the RFID blocking card in your wallet or travel bag, or save it as a backup; Simply insert it alongside your credit and debit cards for immediate protection against identity theft — no charging, no setup
| Control | What it verifies | Who must implement it | What happens if card details are exposed |
|---|---|---|---|
| Dynamic CVV/CVC | Whether the submitted security code is currently valid | The card issuer, with payment-network support; merchants must accept the resulting authorization | An old code may become unusable, reducing the value of copied card credentials |
| EMV 3-D Secure | Transaction, payment and device signals used to authenticate the shopper and evaluate risk | Merchant, issuer and their 3-D Secure systems | The issuer can request additional authentication or decline a risky transaction; it does not itself rotate the CVV |
Issuers can use both controls. A dynamic CVV targets replay of an exposed security code, while 3-D Secure adds transaction-level authentication and risk assessment.
What changing CVVs cannot guarantee
- It is not a universal fraud blocker. The mechanism addresses misuse of card-not-present credentials, not every form of payment fraud.
- It does not make a stolen card harmless. Criminals may still exploit other data, account takeover, social engineering, compromised merchant systems or transactions that do not require the same verification.
- It does not replace issuer controls. Banks still need monitoring, transaction risk rules, customer alerts, dispute handling and other security measures.
- Support is not automatic. Visa’s service is offered to issuer banks; consumers cannot assume their existing card has a dynamic code.
How to find out whether your card supports one
- Open your bank’s mobile app and look for a digital-card, virtual-card or security-code option.
- Check whether the displayed CVC is labeled dynamic, changing or temporary, and note the stated expiration or refresh behavior.
- Ask the issuer whether your exact card and payment network support a dynamic CVV/CVC for online purchases.
- Continue using the issuer’s normal fraud alerts and account-locking tools; a changing code is an additional layer, not a reason to disable them.
If your issuer does not offer the feature, an RFID-blocking wallet will not provide an equivalent benefit: it does not generate or refresh a card-not-present security code. Specialist dynamic-code cards described in technical literature are issuer-deployed payment instruments, not a generic retail add-on.
Best Value

- ONE CARD PROTECTS YOUR WHOLE WALLET: Drop a single KF-Premium card into your wallet, purse, or card holder and every card sitting near it is shielded from contactless RFID and NFC scans, so you do not need a separate sleeve on each card. This 2-pack covers a second wallet, a passport holder, or a family member.
- ULTRA THIN AT 0.9MM, BARELY THERE: Each blocking card is only 0.9mm thick, about as slim as one of your bank cards, so it slides into any wallet slot without the bulk of foil sleeves or switching to a new wallet. Slim enough that you forget it is working.
- STOPS FRAUD BEFORE IT STARTS: The armoured shield design sends out an interfering counter-signal that blocks unauthorized RFID and NFC readers from skimming your debit cards, credit cards, and IDs. It guards against contactless payment fraud, identity theft, and digital pickpocketing in crowds, on transit, and while you travel.
- WORKS THE MOMENT IT IS IN YOUR WALLET: No batteries, no charging, no app, and nothing to switch on. Protection is automatic and continuous for the life of the card, and the durable, high-quality build holds up to daily wear in a back pocket or bag.
- A PRACTICAL GIFT THEY WILL ACTUALLY USE: The sleek black finish gives it a premium look that suits travelers, students, parents, and anyone who carries contactless cards. Boxed as a 2-pack, it works for birthdays, holidays, or a stocking filler that quietly protects the people you care about.
The practical answer for online shoppers
A changing CVV can reduce the usefulness of a stolen static security code and therefore may lower some online fraud. The strongest documented result is Westpac’s own 2022 report, which should be read as evidence from one bank rather than a universal 80-percent promise. Whether you receive that protection depends on your issuer, card product and the way the dynamic code is implemented.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




