Freedom251 › Direct Debit Processing Software
Cashfree eNACH
What Cashfree eNACH is
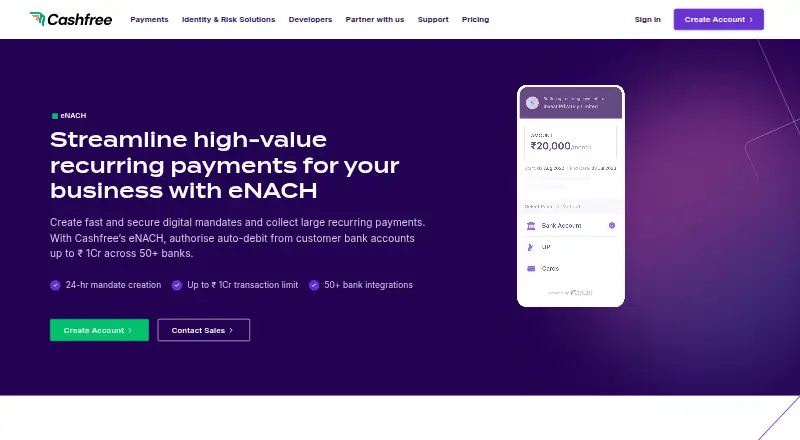
Cashfree eNACH automates recurring payments by debiting customer bank accounts under e-Mandates. Cashfree says businesses can authorize debits up to ₹1 Crore across more than 50 banks supported for e-Mandate registration. The maker states that mandate creation takes 24 hours and activation takes 1 to 2 days. Merchants can retry failed payments, view subscription and payment reports in a dashboard, and import mandates from an existing payment provider. Checkout can use Cashfree's hosted page or a branded experience built with Seamless APIs. Third Party Validation checks whether a bank account is KYC-verified when a mandate is created. Cashfree also lists e-commerce plugins and developer integration kits for connecting the service. It is intended for domestic recurring payment use cases, including lending, investments, insurance, education technology, software services, and rentals. The product offers API access and mandate management on web. Pricing is available on request; the listed plan charges for mandate creation or presentation, with a separate platform fee.
Who it suits
Cashfree eNACH suits businesses collecting recurring domestic payments, including lenders, insurers, investment platforms, education technology, SaaS, and rental services. It may fit teams that need mandate management, payment retries, or migration from another provider.
What it does well
- Supports e-Mandates across 50+ banks
- Mandate creation is stated as 24 hours
- Supports failed-payment retries and mandate migration
- Offers hosted checkout and branded API checkout
- Dashboard includes subscription and payment reports
What to know first
- Pricing is available only on request
- Platform fee applies separately to mandate or presentation charges
Limits
The eNACH / E-mandate plan charges per mandate creation or presentation, and a platform fee applies separately. The listed pricing is on request.
Plans
| Plan | Billed and limits | Price |
|---|---|---|
| eNACH / E-mandate | mandate creation / per presentation · platform fee applies separately | On request |
As cashfree.com lists them, read 2 Oct 2026. The maker's own page has the final word.
Getting started
- Visit the Cashfree eNACH website.
- Choose the hosted checkout page or build a branded checkout with Seamless APIs.
- Use the listed e-commerce plugins or developer integration kits to connect the platform.
- Request pricing for the eNACH / E-mandate plan.
Cashfree eNACH is a domestic India service for collecting recurring payments by automatically debiting customers’ bank accounts. It suits lenders, insurers, subscription businesses and other organisations that need mandate administration around an API. The main decision is whether its custom, volume-sensitive commercial terms fit your collection model.
Overview
Cashfree eNACH turns periodic bank-account payments into electronic mandates that a business can manage and collect against. Mandates can cover amounts up to ₹1 Crore, and registration spans all 50+ banks supported by NPCI for e-Mandates. Cashfree says mandate creation takes 24 hours and activation one to two days, a practical timetable for onboarding customers into recurring collections.
This is a domestic solution, not a general international direct-debit service. Its combination of migration, retries and reporting is most useful when an Indian operation is replacing or consolidating an existing recurring-payment process.
Key features
Mandates and payment recovery
Businesses can authorise automatic debits and retry failed payments. Retries give merchants a way to pursue a missed collection instead of treating the first failure as the end of the billing cycle. The ₹1 Crore ceiling supports both high-value obligations and ordinary subscriptions, while coverage across 50+ NPCI-supported banks reduces bank-availability gaps during registration.
Activation, migration and oversight
Cashfree provides a subscription dashboard with subscription and payment reports, so teams can follow recurring arrangements and their collection activity in one place. Mandates can be imported from an existing payment provider, which makes the service more suitable for a migration than a completely new build. Third Party Validation checks whether the bank account is KYC-verified when a mandate is created, adding an account-validation step to enrolment.
Checkout and integration
Businesses can use Cashfree’s hosted checkout page or create a branded flow through Seamless APIs. E-commerce plugins and developer-focused integration kits give both plugin-led and API-led teams an entry point. API access is included in the eNACH plan, so organisations wanting their own billing logic are not limited to the hosted page.
Security and support
Cashfree states that authentication and auto-debits follow current government guidelines and cites RBI Payment Aggregator Certificate No. 266/2025. Cashfree Payments India Private Limited also holds ISO/IEC 27001:2022 certification covering its payment-aggregator and payment-service-provider activities. Existing customers can raise dashboard tickets, email support or contact an account manager.
Pricing
The eNACH / E-mandate plan has custom pricing. It is billed for mandate creation or per presentation, and a separate platform fee applies. Payment frequency is recurring, scheme coverage is domestic, and the plan includes mandate management, API access and a hosted payment page.
This structure fits businesses that can negotiate terms around their mandate and presentation volumes, especially lenders, NBFCs, mutual-fund and SIP platforms, insurers, ed-tech providers, SaaS companies and rental services. It is less convenient for a small business seeking a published, predictable subscription price: the platform fee and usage charges need to be agreed before costs can be compared.
Platforms
Cashfree eNACH is offered through web and API access. The web experience covers hosted checkout and dashboard work; the API supports branded checkout and integration with a business’s own systems.
Who it's for
Choose it for Indian recurring-revenue operations that collect from bank accounts, need mandates up to ₹1 Crore, or are moving mandates from another provider. It is particularly aligned with regulated or scheduled-payment models such as lending, insurance, investments, education, software subscriptions and rent. Organisations collecting internationally, or those that require a transparent self-serve price, should look elsewhere.
Pros and cons
Pros
- Broad domestic bank reach: registration covers all 50+ NPCI-supported banks, improving customer choice.
- High mandate ceiling: authorisations up to ₹1 Crore accommodate substantial obligations as well as subscriptions.
- Operational continuity: payment retries, migration tools and subscription reports address recurring-collection work beyond initial checkout.
- Flexible implementation: hosted checkout, branded Seamless APIs, plugins and integration kits support different technical teams.
- Validation and assurance: KYC-status checking and stated RBI-aligned processing add controls for mandate creation and debits.
Cons
- Custom commercial terms: mandate or presentation billing plus a separate platform fee makes budgeting harder without a negotiated quote.
- Domestic scope: businesses needing international direct-debit coverage will need another service.
- Activation is not instant: even with 24-hour creation, Cashfree quotes one to two days for activation.
Alternatives
Browse the Direct Debit Processing Software list when you want to compare more collection products by workflow and platform.
Paystack is the better comparison for a business operating in Nigeria that values a free plan and published local transaction pricing: its Nigerian plan has no subscription charge, with local transactions at 1.5% plus NGN 100 (the NGN 100 is waived below NGN 2,500). Powens suits teams wanting a broader API product with a free trial and enterprise options such as dedicated hosting and support, with terms set in a purchase order.
Razorpay e-Mandate is a nearby India-focused alternative to evaluate when you prefer another provider’s e-mandate stack. AccessPay is aimed at organisations prepared for a flat annual subscription priced around transaction volumes, users and data or submission workflows. Bottomline Internal Threat Management is an enterprise fraud and insider-risk product rather than a recurring bank-debit service.
BRIAPI AutoDebit is an API from BRI for integrating third-party applications with BRI services. ClearDebit and Debit Success are paid API-and-web alternatives to consider alongside Cashfree.
Verdict
Cashfree eNACH is a strong fit for Indian lenders, insurers, investment platforms, subscription businesses and similar operators that need high-value mandates, broad NPCI bank coverage, migration support and recurring-payment reporting. Choose it for that end-to-end domestic mandate workflow and its hosted-or-API checkout choice. Look elsewhere if international collection or a clearly published, all-in price matters more than those controls.
Verdict
Cashfree eNACH offers recurring bank-debit workflows with mandate management, reporting, and checkout options. Ask the maker for pricing details, including the separate platform fee.
Questions
How much does Cashfree eNACH cost?
Pricing is on request. The listed eNACH / E-mandate plan charges for mandate creation or per presentation, with a separate platform fee.
Which platforms does Cashfree eNACH support?
The listed platforms are API and web.
Does Cashfree eNACH support recurring payments?
Yes. It automates recurring domestic payments through automatic bank-account debits and includes mandate management.
Which banks can use e-Mandate registration?
Cashfree supports all 50+ banks supported by NPCI for e-Mandate registration.
Can a business use an existing mandate?
Cashfree lets businesses import mandates from an existing payment provider.
Who makes Cashfree eNACH?
Cashfree provides the eNACH service. Cashfree Payments India Private Limited has ISO/IEC 27001:2022 certification for payment aggregator and payment service provider activities.
Facts from Cashfree eNACH's own pages
- Bank coverage
- Cashfree supports all 50+ banks supported by NPCI for e-Mandate registration. · cashfree.com, 2 Oct 2026
- Checkout options
- Businesses can use Cashfree's checkout page or build a branded checkout with Seamless APIs. · cashfree.com, 2 Oct 2026
- Compliance validation
- Third Party Validation checks whether a bank account is KYC-verified when a mandate is created. · cashfree.com, 2 Oct 2026
- Founded
- 2015 · cashfree.com, 28 Sept 2026
- Headquarters
- Bengaluru, Karnataka, India · cashfree.com, 28 Sept 2026
- Integrations
- Cashfree lists e-commerce plugins and developer-friendly integration kits for its eNACH platform. · cashfree.com, 2 Oct 2026
- Mandate activation
- Cashfree states that e-Mandates are activated within 1 to 2 days, with 24-hour mandate creation. · cashfree.com, 2 Oct 2026
- Mandate limit
- Cashfree states that businesses can authorise auto-debits from customer bank accounts up to ₹1 Crore across 50+ banks. · cashfree.com, 2 Oct 2026
- Mandate migration
- Cashfree lets businesses import mandates from an existing payment provider. · cashfree.com, 2 Oct 2026
- Payment retries
- Merchants can retry failed payments to help maintain recurring collections. · cashfree.com, 2 Oct 2026
- Security and regulation
- Cashfree states that its payment authentications and auto-debits follow current government guidelines and lists RBI Payment Aggregator Certificate No. 266/2025. · cashfree.com, 2 Oct 2026
- Security certification
- Cashfree Payments India Private Limited has an ISO/IEC 27001:2022 information security management certification covering payment aggregator and payment service provider activities. · cashfreelogo.cashfree.com, 2 Oct 2026
- Subscription management
- The product includes a subscription dashboard with subscription and payment reports. · cashfree.com, 2 Oct 2026
- Support
- Existing customers can raise dashboard tickets, email Cashfree support, or contact their account manager. · cashfree.com, 2 Oct 2026
- Target customers
- Cashfree identifies NBFCs, digital lenders, mutual funds, SIP platforms, insurers, ed-tech, SaaS, and rental services as eNACH use cases. · cashfree.com, 2 Oct 2026
- What it does
- Cashfree eNACH automates periodic or recurring payments through automatic debits from customer bank accounts. · cashfree.com, 2 Oct 2026
Where Cashfree eNACH stands on Freedom251
- Direct Debit Processing Software#8 of 22