Machine learning has become a practical engine for value creation across finance, turning large volumes of transactions, market data, customer behavior, and operational signals into faster decisions and more precise predictions. Banks, insurers, asset managers, payment networks, and fintech companies use it to spot patterns that traditional rules or manual analysis often miss.
Its applications range from fraud detection and credit risk scoring to algorithmic trading, portfolio analytics, customer personalization, and automated compliance monitoring. When implemented well, machine learning can reduce losses, improve efficiency, strengthen decision-making, and create more responsive financial products.
As an Amazon Associate I earn from qualifying purchases.
At the same time, financial machine learning is only as reliable as the data, controls, governance, and human oversight behind it. Model bias, explainability, regulatory pressure, cybersecurity, and operational risk all shape whether these systems generate sustainable value or introduce new vulnerabilities.
How Machine Learning Creates Value in Finance
Machine learning creates value in finance by turning large volumes of transactions, market data, customer interactions, documents, and behavioral signals into predictions or automated decisions. Banks, insurers, payment networks, asset managers, and fintech companies use these predictions to reduce losses, increase revenue, improve customer experience, and operate more efficiently. The value usually comes from making decisions faster, more consistently, and with a finer level of segmentation than traditional rule-based systems allow.
#1 Best Overall

- 【Professional and Precise Detection】Multiple detection modes can be used individually or simultaneously. When the cash is fake/broken/non-magnetic/normal size banknotes, the LCD display of Aneken money counter will show red error code and sound an alarm.
- 【Multiple Functions】Count-Count the number of bills. Add-Multiple bill counting batches can be added together. Batch-The money counter stops each time the set number of bills to be counted is reached. The bill counter can also be selected in manual or automatic mode.
- 【Count Value】The money counting machine can identify banknote denominations by manually setting the "Value". In conjunction with the “Add” mode, the sum of the values of bills can be calculated. PLEASE NOTE: The bill counter does not automatically recognize the denomination of the bills.
- 【Reliable & Efficient】The high efficiency motor of the bill counter can count 1000 bills per minute. The noise level is less than 60 decibels.PLEASE NOTE: This product operates on 110V ONLY.
- 【Security Protection】For your privacy and security, there is no information about the cash counting machine on the outer box, ensuring the safety of your cash business. We provide lifetime technical support for the cash counting machine. And will reply and provide the best service within 12 hours.
One major source of value is better prediction. A lender can estimate default probability using repayment history, income patterns, cash-flow data, employment signals, and macroeconomic indicators. An insurer can price policies more accurately by analyzing claims history, property characteristics, driving behavior, or health-related data where permitted. A payment company can score transactions in milliseconds to decide whether to approve, challenge, or block them. In each case, the model helps allocate capital, set prices, and manage exposure with greater precision.
Machine learning also improves operational efficiency. Financial institutions still process huge amounts of unstructured information, including loan applications, invoices, earnings reports, contracts, customer emails, and regulatory filings. Natural language processing can classify documents, extract entities, summarize disclosures, and route requests to the right team. Computer vision can help verify identity documents or inspect damage evidence in insurance claims. These systems do not remove the need for human judgment, but they can reduce manual review time and let specialists focus on exceptions, complex cases, and customer-facing work.
Common value drivers
- Revenue growth: identifying cross-sell opportunities, improving pricing, increasing approval rates for creditworthy customers, and supporting better investment decisions.
- Loss reduction: detecting fraud, predicting defaults, flagging suspicious activity, and reducing operational errors.
- Customer retention: personalizing offers, anticipating churn, improving service response times, and tailoring financial guidance.
- Capital efficiency: improving risk measurement, stress testing, portfolio construction, and liquidity forecasting.
- Compliance productivity: prioritizing alerts, monitoring communications, reviewing documents, and supporting audit trails.
The strongest applications typically combine machine learning with well-designed business processes. A fraud model is valuable only if its alerts are delivered quickly to the authorization system or investigation team. A credit model is useful only if it fits underwriting policy, regulatory requirements, and portfolio objectives. A personalization model needs accurate customer consent, clean product data, and channels that can act on recommendations. In practice, financial firms create value when model outputs are embedded into workflows, measured against business outcomes, and monitored after deployment.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Machine learning is not valuable simply because it is complex. Many successful financial models are focused, narrow, and measurable: predicting which mortgage applicants are likely to upload missing documents, estimating cash demand at ATMs, forecasting call-center volume, or ranking collection strategies by expected recovery. These use cases may be less visible than trading algorithms, but they can produce steady gains at scale. The core pattern is the same: use historical data to learn relationships, apply those patterns to current decisions, and continuously compare predictions with actual results.
Value creation also depends on trust. Finance is highly regulated and deeply personal, so institutions must be able to explain decisions, control model risk, protect customer data, and avoid unfair treatment. The most effective machine learning programs balance automation with governance: clear ownership, validation, monitoring, documentation, and escalation paths for unusual outcomes. When that balance is in place, machine learning becomes more than an analytics tool; it becomes part of the financial institution’s decision-making infrastructure.
Fraud Detection and Risk Management
Fraud detection is one of the most established uses of machine learning in finance because transaction data is high-volume, fast-moving, and rich in behavioral signals. Banks, card networks, payment processors, insurers, and fintech platforms use models to assess whether a payment, login, account opening, claim, or transfer appears legitimate. Instead of relying only on fixed rules such as blocking every purchase above a certain amount, machine learning systems compare each event with patterns learned from millions or billions of prior interactions.
Common fraud models evaluate features such as transaction amount, merchant category, device fingerprint, IP location, time of day, account age, velocity of recent activity, failed login attempts, and historical customer behavior. A card purchase in a familiar grocery store may receive a low-risk score, while a large cross-border purchase from a new device shortly after a password reset may be escalated. These systems usually produce a probability score, which is then used to approve the transaction, request step-up authentication, send an alert, or route the case to an analyst.
Free tools Windows power users keep installed
One-click scans. No signup required.
Rank #2

- Precise Detection - The money counter adopts UV/MG/IR/MT/DD detection technology, when the cash is fake or broken, the LCD display of the currency counter will show red error code and sound an alarm. After you take out the defective bill, the machine will continue to work.
- 2026New Value Counting Mode - In ADD mode, you can select different currency denominations first and then the counting machine calculates the total number and total value of different denominations of currency. (Note: you cannot calculate the total of a mixed bunch of banknotes!)
- Efficient and Smooth - The dispenser uses the latest roller technology to quickly count not only new banknotes, but also old, creased banknotes. The efficient motor counts up to 1200 notes per minute without jams, which saves you a lot of time and ensures that you can quickly complete your daily financial counting tasks.
- PONNOR Special Design - To minimise the impact on others when using the money counter, we have added a silent setting. Simple to operate, just keep the ST/CL button pressed, switch off the on/off button at the rear of the machine and switch it on again to enter silent mode. In the same way you can go back to sound mode and the machine noise is below 60 dB.
- Multiple modes - The money machine supports COUNT, ADD, BATCH, AUTO, MANUAL and other modes, easy to use, easy to operate, beginners can also quickly use.
Typical fraud and risk use cases
- Payment fraud: identifying stolen-card usage, account takeover, mule accounts, and suspicious transfers before funds leave the institution.
- Identity fraud: detecting synthetic identities, forged documents, mismatched application data, and abnormal onboarding behavior.
- Insurance fraud: flagging inflated claims, staged accidents, duplicate submissions, and suspicious provider networks.
- Anti-money laundering: finding unusual transaction flows, structuring, circular payments, and links between accounts that may indicate laundering activity.
- Credit risk: estimating the probability that a borrower will default and adjusting limits, pricing, or approval decisions accordingly.
Risk management extends beyond fraud prevention. Machine learning can help lenders estimate creditworthiness, detect early signs of loan deterioration, forecast liquidity stress, and monitor market or counterparty exposure. For example, a small-business lending model may combine bank account cash-flow data, invoice behavior, repayment history, sector trends, and macroeconomic indicators to estimate default risk more dynamically than a traditional scorecard. In portfolio management, models can search for concentrations of exposure that may not be visible through manual review, such as clusters of borrowers dependent on the same supplier, region, or commodity price.
A major advantage of machine learning is its ability to detect subtle, nonlinear patterns. Fraudsters often adapt quickly when institutions publish or operationalize simple rules. If a payment processor blocks transactions above a fixed threshold, criminals may split purchases into smaller amounts. Machine learning models can incorporate velocity, sequence, relationships between entities, and deviations from personal behavior, making evasion more difficult. Graph-based techniques are especially useful for finding connected accounts, shared devices, repeated addresses, or coordinated activity across seemingly unrelated customers.
Still, these systems must be carefully managed because false positives create real costs. Blocking a legitimate rent payment, travel purchase, or business transfer can frustrate customers and damage trust. False negatives, on the other hand, allow financial loss and regulatory exposure. Financial institutions typically tune models according to risk appetite, customer segment, transaction type, and legal requirements. A high-value wire transfer may justify more friction, while a low-value routine purchase may be approved unless the risk score is extreme.
Effective deployment usually combines machine learning with human review, business rules, and audit trails. Analysts need clear case information, such as which factors contributed to a high-risk score and how similar cases were resolved. Model monitoring is also essential because fraud patterns shift, economic conditions change, and customer behavior evolves. Institutions track metrics such as precision, recall, chargeback rates, approval rates, customer complaints, and investigation outcomes. In regulated environments, they must also document data sources, validation methods, model limitations, and controls that prevent unfair or discriminatory outcomes.
Recommended Free Tools
Algorithmic Trading and Investment Insights
Machine learning supports investment teams by finding patterns in market, economic, and company data that are too large or fast-moving for humans to review manually. In algorithmic trading, models may analyze price movements, order book activity, volatility, news sentiment, earnings transcripts, macroeconomic releases, and alternative data such as web traffic or satellite imagery. The goal is not simply to “predict the market,” but to estimate probabilities, rank opportunities, manage execution, and adjust portfolios as conditions change.
At the trading level, machine learning is often used for signal generation, trade execution, and portfolio construction. A signal model might rank stocks by expected short-term return, identify currencies likely to move after a central bank announcement, or detect when a commodity price has diverged from related supply indicators. Execution models help decide how to split a large order into smaller trades to reduce market impact and avoid unfavorable pricing. Portfolio models can combine expected return, volatility, correlation, liquidity, and transaction costs to select positions that fit a fund’s risk limits.
Common applications in investment workflows
- Price and return forecasting: Models estimate the likelihood of future price changes across equities, bonds, currencies, commodities, or digital assets.
- Sentiment analysis: Natural language processing extracts signals from news articles, analyst reports, earnings calls, regulatory filings, and social media.
- Factor discovery: Machine learning can test relationships between returns and variables such as valuation, momentum, quality, credit spreads, or macroeconomic indicators.
- Risk-aware portfolio optimization: Models help balance expected performance against drawdown risk, concentration, liquidity, and changing correlations.
- Trade execution optimization: Algorithms choose timing, venue, and order type to reduce slippage and transaction costs.
Investment insights also come from combining structured financial data with unstructured information. For example, a model might compare management language in quarterly calls with historical patterns of earnings revisions, or connect supply-chain shipping data with revenue trends for retailers and manufacturers. In fixed income, machine learning can support credit scoring by monitoring issuer fundamentals, sector exposure, covenant language, and market-implied default risk. In wealth management, similar techniques can help advisors identify portfolio drift, tax-loss harvesting opportunities, or clients whose allocations no longer match their goals.
Rank #3
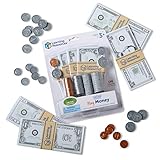
- GAME FOR KIDS: Use the realistic play money to teach lessons in making change, identifying value, and adding and subtracting.
- REALISTIC MONEY: Made from heavy-duty paper and printed on both sides, each pretend bill is ready for countless pretend cash transaction
- PLAY MONEY FOR KIDS: The play money is a 3/4 scale of actual American Dollars. Includes 60 pretend bills include 20 $1s, 20 $5s, 10 $10s, and 10 $20s.
- GREAT VALUE: The set also includes a full assortment of 90 plastic coins, including 30 pennies, 20 nickels, 20 dimes, and 20 quarters. Pretend bills measure 6.25" x 2.625", pretend coins range from .80" (penny) - .995" (quarter
- GIVE THE GIFT OF LEARNING: Whether you’re shopping for holidays, birthdays, or just because, toys from Learning Resources help you discover new learning fun every time you give a gift! Ideal gift for Halloween, Christmas, Stocking Stuffers, Easter Baskets Stuffers or even for Homeschool.
Practical use requires rigorous testing. Financial markets are noisy, adaptive, and affected by events that may not appear in historical data. A strategy that performs well in backtesting can fail in live trading if it overfits past conditions, ignores transaction costs, or depends on data that would not have been available at the time of the decision. Teams typically use walk-forward validation, out-of-sample testing, stress scenarios, and paper trading before committing capital. They also monitor live performance for signal decay, changing liquidity, model drift, and operational failures.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Machine learning can improve investment decision-making, but it does not remove uncertainty. The strongest applications often combine quantitative models with domain expertise, clear risk controls, and disciplined governance. Human portfolio managers, traders, compliance teams, and risk officers still play a central role in deciding which signals are credible, how much capital to allocate, and when market conditions make a model unreliable. Used carefully, machine learning becomes a decision-support engine rather than an automatic guarantee of superior returns.
Personalized Banking and Customer Analytics
Machine learning helps banks, fintech apps, insurers, and wealth platforms move from broad customer segments to highly individualized services. Instead of treating all checking-account holders, card users, or mortgage applicants alike, models can analyze transaction histories, balances, income patterns, channel behavior, life events, and product usage to predict what a customer may need next. This creates value through better product recommendations, more relevant communications, lower servicing costs, and stronger retention.
A common use case is next-best-action modeling. For example, a bank might identify that a customer with rising monthly savings, stable payroll deposits, and repeated visits to mortgage calculators is likely to respond to a first-time homebuyer offer. Another customer with frequent overdrafts, irregular income, and high short-term credit usage may benefit more from cash-flow alerts, a lower-fee account, or a budgeting tool than from a new credit product. The goal is not simply to sell more, but to match services to financial context in a way that improves both customer outcomes and institutional performance.
Common applications in customer analytics
- Product recommendations: Suggesting credit cards, savings accounts, insurance, loans, or investment products based on demonstrated needs and eligibility.
- Churn prediction: Identifying customers likely to close accounts, reduce deposits, or move assets to competitors, then triggering retention offers or outreach.
- Customer lifetime value: Estimating the long-term profitability and service needs of different relationships to guide acquisition and support strategies.
- Personal financial management: Categorizing spending, forecasting bills, detecting subscription changes, and warning customers before potential overdrafts.
- Service routing: Directing customers to the right digital workflow, chatbot, specialist, or branch staff based on intent and urgency.
These systems rely heavily on behavioral signals. Transaction categorization models can distinguish rent, payroll, utilities, travel, grocery spending, loan payments, and recurring subscriptions. Clustering models can group customers by financial behavior, such as high-income low-savers, gig-economy earners, frequent travelers, small-business owners, or retirement-focused investors. Predictive models can estimate the probability of a customer accepting an offer, missing a payment, needing human support, or increasing deposits after a specific intervention.
Personalization also plays a growing role in digital banking interfaces. Mobile apps can prioritize the most useful features for each user: spending insights for one person, investment performance for another, credit-score monitoring for a third, and small-business cash-flow tools for another. Natural language processing can improve chatbots and call-center systems by interpreting customer intent, summarizing prior interactions, and suggesting responses to service agents. When implemented well, this reduces friction and makes financial services feel more timely and less generic.
However, customer analytics must be handled carefully because financial personalization can easily cross into manipulation or unfair treatment. A model that targets high-fee products to financially vulnerable customers may increase revenue while harming trust and inviting regulatory scrutiny. Similarly, personalization based on proxies for age, race, gender, disability, or neighborhood can create discriminatory outcomes even when those attributes are not directly used. Strong governance requires clear consent practices, explainable recommendations, bias testing, data minimization, and controls that distinguish helpful guidance from exploitative targeting.
Rank #4

- LEARN THROUGH PLAY – AGES 4 + Interactive 165-piece set teaches kids how to identify coins, count change, and understand basic math skills through hands-on practice.
- CLASSROOM & HOME LEARNING SET Includes colorful paper bills and durable plastic coins organized for easy sorting and group activities.
- SAFE & CPSIA TESTED Complies with ASTM F963 toy safety standards and CPSIA requirements; non-toxic materials and rounded edges for child safety.
- EASY STORAGE & ORGANIZATION Comes with a reusable storage tray and teacher-designed counting cards to keep lessons organized.
- FUN WAY TO LEARN MONEY SKILLS Ideal for teachers, homeschooling parents, and play-based learning centers; great gift for boys and girls.
The most effective institutions combine machine learning with human judgment, compliance oversight, and customer control. Customers should be able to understand they are seeing a recommendation, opt out of certain data uses, correct inaccurate information, and access human support for significant financial decisions. In that model, personalization becomes more than a marketing tactic: it becomes a way to deliver banking experiences that are proactive, contextual, and aligned with a customer’s real financial needs.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Data, Models, and Infrastructure Requirements
Machine learning in finance depends on reliable data pipelines, carefully selected models, and infrastructure that can support both experimentation and regulated production use. Financial data is often fragmented across core banking systems, payment processors, market data feeds, customer relationship platforms, credit bureaus, call centers, and external providers. Before a model can produce value, teams must define the business problem, identify the right target variable, establish a clean observation window, and confirm that the data available at prediction time matches the data used during training.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Data quality is especially critical because small errors can create large financial consequences. Missing income fields, duplicated transactions, stale account balances, incorrect merchant labels, or delayed market prices can distort model outputs. Strong data governance usually includes lineage tracking, access controls, validation rules, consent management, and retention policies. In regulated environments, teams also need reproducible datasets so that a credit decision, fraud alert, or investment signal can be reviewed months or years later.
Common data and modeling components
- Structured data: account balances, repayment history, trade records, transaction amounts, credit utilization, claims data, and customer demographics.
- Unstructured data: support transcripts, emails, news articles, earnings call text, social signals, and document images processed with natural language processing or computer vision.
- Real-time streams: card swipes, login events, device fingerprints, order book movements, and payment authorization requests that require low-latency scoring.
- Feature stores: shared repositories that provide consistent variables, such as average transaction value over 30 days or number of failed logins in one hour, across training and production.
Model choice should match the use case, latency needs, interpretability requirements, and cost of errors. Logistic regression and decision trees remain useful for credit scoring and compliance-sensitive applications because they are easier to explain. Gradient boosting models often perform well on tabular financial data and are widely used for fraud detection, churn prediction, and risk ranking. Deep learning can help with document processing, behavioral biometrics, and complex sequence patterns, while time-series and probabilistic models are common in forecasting, liquidity planning, and portfolio analysis.
| Requirement | Finance Example | Practical Concern |
|---|---|---|
| Low latency | Card fraud scoring at checkout | Predictions may need to return in milliseconds without blocking legitimate customers. |
| Explainability | Loan approval or pricing | Customers, auditors, and regulators may require clear factors behind decisions. |
| Scalability | Daily risk calculations across portfolios | Infrastructure must handle spikes, batch workloads, and large historical datasets. |
| Monitoring | Fraud model drift after a new scam pattern | Performance, bias, data freshness, and false positives must be tracked continuously. |
The infrastructure layer typically includes cloud or hybrid compute, secure data lakes or warehouses, model training environments, orchestration tools, application programming interfaces, and monitoring dashboards. Many institutions also need a model registry to track versions, approval status, training data, metrics, and owners. Deployment should support staged releases, champion-challenger testing, rollback procedures, and human review workflows for high-impact decisions. Without these controls, even accurate models can become operational risks.
Successful implementation also requires collaboration between data scientists, engineers, risk officers, compliance teams, cybersecurity specialists, product managers, and frontline business users. A model that performs well in a book is only a starting point. To work in finance, it must be secure, explainable, monitored, documented, and connected to a decision process that employees and customers can trust.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallChallenges, Regulations, and Ethical Risks
Machine learning in finance operates under stricter constraints than many other industries because model decisions can affect credit access, insurance pricing, fraud investigations, investment outcomes, and customer privacy. A model that performs well in testing can still create losses or customer harm if market conditions change, data quality deteriorates, or users misunderstand its outputs. Financial institutions therefore need controls that cover the full model life cycle: data sourcing, feature engineering, validation, deployment, monitoring, and retirement.
Best Value
- 100 $1 BILLS INCLUDED -- This set of one-dollar bills is perfect for solitary or group play. It’s ideal pretend money for kids to learn about currency in homes, centers, classrooms or playrooms.
- REALISTIC PLAY BILLS -- This learning money is life-sized to match U.S. currency. The bills are all double-sided with detailed artwork - just like real cash!
- TEACH MONEY MATH -- This play money $1 bill set can help introduce addition and subtraction of money values.
- A WEALTH OF PRETEND PLAY -- Use this pretend money for learning or imaginary adventures! This set of 100 prop bills is perfect for role play or purchasing hugs from Mom!
- ENCOURAGE MONEY MANAGEMENT -- Use this realistic fake cash set to teach kids the importance of budgeting and saving. Or, use it as rewards for chores and good grades.
Regulation is a central implementation challenge. Banks, lenders, insurers, brokerages, and payment firms may need to comply with rules covering fair lending, consumer protection, anti-money laundering, securities markets, operational resilience, and data privacy. In practice, this means teams must be able to document how models are built, what data they use, how decisions are reviewed, and how customers can challenge adverse outcomes. Black-box systems can be difficult to justify when regulators, auditors, or internal risk committees ask for evidence that a decision was lawful, consistent, and not discriminatory.
Common risk areas
- Bias and discrimination: Historical data may reflect unequal access to credit, different fraud investigation rates, or biased pricing decisions. If these patterns are learned by a model, automated systems can reinforce them at scale.
- Explainability: Complex models such as gradient-boosted trees, deep learning networks, and large language model components may produce accurate predictions but limited human-readable explanations.
- Model drift: Customer behavior, fraud tactics, interest rates, inflation, and market volatility change over time. Models trained on old patterns may become less reliable without continuous monitoring.
- Data privacy: Financial data is highly sensitive. Combining transaction histories, device identifiers, location signals, and third-party data increases the risk of over-collection or misuse.
- Cybersecurity and adversarial behavior: Fraudsters and market participants may probe automated systems, adapt to detection patterns, or attempt data poisoning attacks.
Ethical concerns often arise when a model is technically accurate but socially questionable. For example, a lending model might predict default risk using variables that correlate strongly with income, geography, education, or employment history. Even if protected attributes are removed, proxy variables can still create unfair outcomes. Similarly, personalized pricing and product recommendations can improve relevance, but they may also steer vulnerable customers toward expensive credit, excessive trading, or products that are profitable for the institution rather than suitable for the customer.
Strong governance reduces these risks. Institutions should maintain model inventories, independent validation processes, approval workflows, and clear accountability for automated decisions. Testing should include performance metrics, stress scenarios, fairness analysis, privacy review, and operational impact assessments. For high-stakes use cases such as credit denial, fraud account freezes, or investment advice, human review channels and customer appeal processes are essential. The goal is not to avoid machine learning, but to use it in ways that are measurable, auditable, secure, and aligned with customer interests as well as business value.
Frequently Asked Questions
How is machine learning actually used by banks and financial firms?
Machine learning is used to score credit applications, detect suspicious transactions, forecast cash flow, personalize product offers, automate customer support, and support portfolio analysis. In many firms, it works alongside traditional rules and human review rather than replacing them entirely. The biggest value often comes from faster decisions, better risk signals, and lower operational costs.
Can machine learning really stop financial fraud?
Machine learning can reduce fraud by spotting unusual transaction patterns, device behavior, location changes, and account activity in real time. It is especially useful because fraud tactics change quickly, and models can adapt as new data becomes available. However, it cannot eliminate fraud completely, so firms still need manual investigation, strong authentication, and clear escalation processes.
Is machine learning better than human investors at picking stocks?
Machine learning can analyze large datasets faster than humans, including price history, earnings data, news sentiment, and alternative data such as web traffic or satellite signals. That does not guarantee better returns, because markets are noisy, competitive, and affected by events that models may not anticipate. In practice, many investment teams use machine learning to generate signals, test strategies, manage risk, and support human decision-making.
What data does a financial institution need to build useful machine learning models?
Useful models usually require clean historical data, consistent labels, reliable customer or transaction records, and strong controls around privacy and access. For fraud detection, that may include transaction amounts, merchant categories, login patterns, device fingerprints, and confirmed fraud outcomes. For lending or personalization, data quality, fairness, consent, and regulatory compliance are just as as model accuracy.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsWhat are the main risks of using machine learning in finance?
The main risks include biased decisions, poor model explainability, data privacy failures, overfitting, cyberattacks, and models degrading as market or customer behavior changes. Financial firms also need to satisfy regulators, document model decisions, monitor performance, and provide fair treatment to customers. A strong governance process should include human oversight, audit trails, stress testing, and regular model reviews.
Bottom Line
Machine learning is reshaping finance by helping institutions uncover patterns, price risk more accurately, detect fraud faster, personalize customer experiences, and support smarter investment decisions. Its value comes not from replacing human judgment, but from giving teams better signals, faster analysis, and more scalable decision-making.
To use it well, financial organizations should start with clear business goals, high-quality data, strong governance, and continuous monitoring for bias, drift, security, and regulatory compliance. The next step is to identify one high-impact use case, test it responsibly, and scale only when the model proves reliable, explainable, and aligned with customer trust.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




