Free tools Windows power users keep installed
One-click scans. No signup required.
A missing or incorrect e-invoice can create a tax-compliance defect, but the consequence depends on the country, transaction type and nature of the problem. The usual outcomes are a request for a corrected invoice, weaker evidence for an input-VAT deduction, rejected invoices in some cases, and potentially administrative fines. There is no single European penalty and an error does not automatically cancel every deduction.
Start by identifying the issuing and receiving countries, whether the transaction is B2B, B2C, B2G, domestic or cross-border, and whether the problem is a missing invoice, a wrong field, an incorrect VAT calculation, a wrong recipient or a failed structured format. Then follow the correction and reporting procedure required by the relevant national law.
As an Amazon Associate I earn from qualifying purchases.
Why the country and transaction matter first
The European Union has a shared baseline for VAT invoicing, while each member state adds national rules, deadlines, penalties and technical mandates. The European Commission describes common requirements for taxable persons doing business in the EU, but explicitly notes that national rules apply in several areas.
Invoices are generally required for most business-to-business supplies, although exceptions exist. Depending on the transaction, an invoice may need the issue date, a unique sequential number, supplier and customer identification, a description and quantity of the goods or services, prices, the VAT rate and amount, and wording such as “reverse charge.” Rules can differ for domestic, cross-border, consumer, public-sector and exempt transactions.
#1 Best Overall

- Two-Part Carbonless Invoice Book: Each invoice book has 50 sets of invoices, each with a white/light yellow section, with the yellow section retained in the invoice book to maintain detailed records.
- Consecutively Numbered: Enlarged red 6-digit numbers in the upper right corner of each invoice receipt book help you quickly navigate through your orders.
- Wraparound Divider Flap: A thick folded cardboard divider is integrated into the back of each invoice book for use between each two-part sales order to prevent the written content from rubbing off on subsequent copies of the invoice, resulting in wasted invoices.
- 2 Packs/50 Sets (100 Sets Total): Each invoice book provides 50 sequentially numbered carbonless sets of 2 invoice books for long-term use.
- Customizable Space: Each invoice book for small business has space at the top to add a company seal or sticker.
Before deciding what to do, record:
- the country whose VAT law governs the supply and, where relevant, the customer’s country;
- whether the customer is a business, consumer or public body;
- the date of supply, invoice date and any reporting deadline;
- which field, amount, recipient or file format is wrong; and
- whether the invoice has already been used for a VAT return, accounts or payment.
This information determines whether you need a replacement invoice, a corrective document, a credit note, a technical resubmission or a separate VAT-return adjustment.
What counts as a defective e-invoice?
Missing invoice
A supplier may have failed to issue an invoice at all, issued it after a statutory deadline, or sent it through a channel that does not satisfy a mandatory e-invoicing rule. A PDF attached to email is not automatically a compliant structured e-invoice. Where a jurisdiction requires machine-readable data, the file may need to follow a prescribed model and national implementation.
Missing or inaccurate content
Common content defects include an absent invoice number, incorrect legal name or tax identification number, an incomplete description, the wrong supply date, an omitted reverse-charge statement, or a VAT rate or amount that does not match the taxable base. A typo with no tax or identification effect may be treated differently from an error that changes liability or prevents the customer from identifying the supply.
Wrong recipient
An invoice addressed to a business that did not receive the goods or services is a separate and serious problem. It can misstate both parties’ records and create an unjustified deduction claim. The recipient should not book or deduct an invoice for a supply it did not receive.
Rank #2

- QUALITY INVOICES: Adams Order books provide a professional invoice or customer receipt; a great way to create and maintain a professional image for small businesses and service providers
- 50 TWO-PART CARBONLESS FORMS: Customers get the perforated white top copy; retain the canary and pink copies for your records
- WRAP-AROUND COVER: Fold the back cover between sets to keep invoices neat and legible
- ROOM FOR CUSTOMIZATION: A blank space at top leaves room for your company stamp; a big savings over custom-printed forms
- CONSECUTIVELY NUMBERED: Large 6-digit numbers in the upper right hand corner help you thumb through orders quickly
Structured-format failure
Under the European Commission’s EN 16931 guidance, compliance is more than putting familiar fields on an electronic document. The invoice must contain mandatory information, use correctly structured data, calculate amounts correctly and use permitted values. A receiving system that is required to accept compliant invoices must be able to process the applicable CORE model or national CIUS (Core Invoice Usage Specification). National restrictions and implementation rules still control the practical result.
What can happen to the customer
Input-VAT deduction may be delayed or challenged
An invoice is normally important evidence for the buyer’s input-VAT deduction. The EU Commission explains that, once the required information is present for the relevant case and member state, the invoice acts as proof supporting deduction in that member state. That does not mean every defect automatically destroys the deduction, nor that an invoice alone proves that a supply occurred.
Tax authorities can ask the buyer to establish the material conditions: that the goods or services were actually supplied, the buyer used them for taxable activities, the VAT was correctly charged and the supplier can be identified. If the document is incomplete or inconsistent, the buyer may need to obtain a correction, provide contracts and delivery evidence, or amend a VAT return. The available remedy and any deadline are national questions.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsBelgian structured-invoice example
Belgian guidance illustrates how a national mandate can add a technical condition. For transactions covered by Belgium’s structured e-invoicing obligation, the buyer needs a structured electronic invoice to exercise deduction. The same guidance describes a conditional “substance over form” route where the material conditions for deduction are met, but it is not a blanket exemption from the electronic requirement.
Rank #3
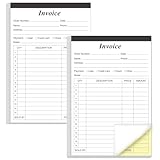
- PACKAGE INCLUDES - Our invoice book per pack has 50 sets sheets, total in 2 pack, Total of 200 sheets. red code printed on each page with consecutive numbers
- Material - Receipt book is excellent quality carbonless paper is used in their production, tears off easily along the perforation.
- A5 Size - Sales invoice book size of 5.5" x 8.5", and forms are 2 part carbonless white/yellow sets on a sturdy chipboard backing
- WIDE APPLICATION - Sales reciepts/invoice book for small business is ideal for restaurants, food trucks, vendors, service provider, photographers, caterers, florists, bakeries, cafes, boutiques and salons
Belgium also states that a buyer may face an administrative fine for lacking the technical means to receive a structured e-invoice. These are Belgian outcomes, not an EU-wide rule.
Reject an invoice for a supply you did not receive
If an invoice was sent to the wrong Belgian recipient, the recipient should reject it. The referenced Belgian guidance says that recipient does not qualify for the tax deduction and should not include the invoice in its accounts. Other countries may prescribe a different workflow, but the safe control is to prevent an invoice for someone else’s supply from entering the ledger.
What can happen to the supplier
Correction, assessment and fines
A supplier that omits mandatory information, charges the wrong VAT, fails to issue an invoice or misses a required structured channel may have to issue a correction and adjust its VAT reporting. Depending on national law, authorities can impose proportional fines for the defective invoice and separate penalties for late issuance, non-filing or technical non-compliance.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Belgium’s Federal Public Service Finance says existing fines for failure to issue invoices and for non-compliant invoices also apply to structured e-invoices. Its FAQ describes a proportional tax fine for a structured invoice that was not issued, lacks mandatory information or contains inaccuracies, under Table C of the annex to Royal Decree No. 41 of 30 January 1987. The same page distinguishes non-proportional fines for late issuance and certain other legal or technical failures.
Rank #4

- QUALITY INVOICES: Adams Invoice books provide a professional invoice or customer receipt; easily customize by using the extra space at the top and your company stamp
- 50-TWO PART CARBONLESS FORMS: Customers get the perforated white top copy; retain the yellow copy for your records
- WRAP-AROUND COVER: Fold the back cover between sets to keep invoices neat and legible
- CONSECUTIVELY NUMBERED: Large 6-digit numbers help you thumb through invoices quickly
- STOCK UP: Each book includes 50 white/canary sets; order several to keep your favorite forms on hand
A Belgian Royal Decree of 8 July 2025, summarized in the authority’s guidance, sets fines for a first failure to have the technical means to issue and receive structured invoices at €1,500, €3,000 for a second offence and €5,000 for subsequent offences, subject to the decree’s recurrence conditions. These amounts apply to Belgium and should be checked against the current law before relying on them.
VAT underpayment can be a separate issue
If an incorrect rate or taxable amount caused too little VAT to be declared, correcting the invoice may not be enough. The supplier may need to amend the relevant VAT return, pay the shortfall and calculate interest or penalties under local procedure. If too much VAT was charged, the customer may be unable to deduct the excess until a valid correction is issued. The exact treatment depends on the country and the type of error.
How to correct an incorrect e-invoice
Use a document that refers unambiguously to the original
The EU VAT Directive treats a document or message that amends an original invoice and refers to it specifically and unambiguously as an invoice. In practice, that may be a corrective invoice, credit note, debit note or another legally recognized document. The Directive does not impose one universal workflow: national rules determine the document type, numbering, tax treatment and reporting period.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →General correction workflow
- Stop using the defective document. Tell the customer and accounting team whether it should be rejected, held or excluded from the next VAT return.
- Identify the original. Capture the original invoice number and date, customer identity, supply date and the reason for correction.
- Classify the error. Separate a clerical field error from a wrong recipient, wrong VAT rate, wrong taxable base, duplicate invoice or format failure.
- Issue the permitted correction document. State that it is corrective, identify the original invoice or invoices and show the corrected values. Follow local numbering and electronic-delivery rules.
- Reconcile tax reporting. Determine whether the supplier, buyer or both must amend a VAT return, recapitulative statement, sales listing or e-invoice transmission.
- Retain the audit trail. Keep the original, correction, rejection or cancellation record, delivery evidence and approval history together.
Spanish example
Spain’s Tax Agency says a corrective invoice is mandatory when an invoice omits one or more required elements or when VAT amounts were calculated incorrectly, among other listed cases. Correction should be made as soon as the issuer becomes aware of the circumstance, provided four years have not elapsed in the situations covered by that guidance.
Best Value

- PACKAGE INCLUDES - Our invoice book per pack has 50 sets sheets, Total of 100 sheets. red code printed on each page with consecutive numbers
- Material - Receipt book is excellent quality carbonless paper is used in their production, tears off easily along the perforation.
- A5 Size - Sales invoice book size of 5.5" x 8.5", and forms are 2 part carbonless white/yellow sets on a sturdy chipboard backing
- WIDE APPLICATION - Sales reciepts/invoice book for small business is ideal for restaurants, food trucks, vendors, service provider, photographers, caterers, florists, bakeries, cafes, boutiques and salons
The Spanish corrective invoice must identify its corrective status, explain the reason, identify the original invoice or invoices, state the correction and meet the general invoice requirements. This is a Spanish procedure, not a timetable that can be applied throughout the EU.
Belgian wrong-recipient example
For an invoice sent to the wrong Belgian recipient, the authority’s guidance says the issuer must account for the mistake and include the wrongly invoiced amounts in a corrective document, in practice a credit note. The unintended recipient should reject the invoice rather than record it as a purchase.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Preserve authenticity, integrity and readability
The consolidated VAT Directive defines an electronic invoice as one containing the required information and issued and received in any electronic format. From issuance through the end of the storage period, businesses must be able to ensure authenticity of origin, integrity of content and legibility. Internal business controls that create a reliable audit trail can be used.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
For practical purposes, preserve the original electronic file rather than only a rendered printout. Link every correction to the original, restrict silent edits, retain transmission and rejection logs, and keep contracts, purchase orders, delivery records and payment evidence that explain the transaction. A corrected invoice should show what changed, not overwrite history.
Situation-by-situation decision table
| Situation | Immediate risk | Typical next action | What varies by country |
|---|---|---|---|
| No invoice issued | Supplier non-compliance; buyer lacks primary evidence | Issue the required invoice promptly and check late-reporting rules | Issuance deadline, fine and reporting correction |
| Missing mandatory field | Deduction evidence or invoice validity may be challenged | Issue a corrective document referring to the original | Permitted format, deadline and whether a minor error can be remedied |
| Wrong VAT rate or amount | Under- or over-declared VAT; buyer’s deduction may not match | Correct invoice and reconcile VAT returns | Interest, penalties and adjustment period |
| Wrong recipient | Unjustified deduction and inaccurate accounts | Recipient rejects; issuer cancels or credits and reissues to the right party | Credit-note and cancellation mechanics |
| PDF or file fails structured mandate | Technical non-compliance; invoice may not be processable | Resend in the required model or CIUS and preserve transmission evidence | Mandated network, schema, validation and sanctions |
| Late invoice | Separate timing offence even if content is correct | Issue immediately and assess late-issuance reporting | Statutory deadline and non-proportional fine |
How to prevent repeat failures
Validate before sending
- Check legal names, tax numbers, addresses, invoice sequence and supply date against master data.
- Recalculate taxable base, VAT rate, VAT amount, rounding and totals automatically.
- Require reverse-charge, exemption and other special wording when applicable.
- Validate the required structured schema, code lists and national CIUS before transmission.
- Block duplicate numbers and invoices addressed to inactive or mismatched customers.
Control receipt as well as issuance
Businesses subject to a structured mandate need a way to receive, validate, route and archive incoming invoices. Assign an owner for rejected files, monitor failed transmissions and ensure the accounting system does not post an invoice before validation. If a customer disputes an invoice, preserve the rejection reason and the replacement document.
Reconcile tax data
Compare invoice totals with VAT returns, sales or purchase ledgers, payment records and any mandated transaction reporting. Investigate differences before filing rather than waiting for an authority query. Keep a calendar for invoice, correction, VAT-return and record-retention deadlines in every country where the business operates.
What to do when you discover an error
- Quarantine the invoice in the accounting workflow.
- Confirm the governing country and transaction category.
- Decide whether the document is missing, inaccurate, misaddressed, duplicated or technically invalid.
- Ask the issuer or customer for the legally correct correction, not simply an edited PDF.
- Check whether a VAT return, sales listing or e-invoice report already included the error.
- Document the decision, correction date, original reference and supporting evidence.
- Escalate to a local tax adviser when the error affects a large amount, a cross-border supply, a reverse charge, an audit or a statutory deadline.
Because national rules change, verify current deadlines and penalties with the relevant tax authority before filing or quoting a fine. The EU overview reflects common rules and national variation; the Directive text cited here is consolidated through 20 March 2025, and national guidance may be updated later.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallQuick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

