Free tools Windows power users keep installed
One-click scans. No signup required.
Short answer: For many Indian merchants, bank-account UPI and RuPay debit have the lowest statutory merchant discount rate (MDR) under the policy baseline that took effect on 1 January 2020. That does not prove they are always the cheapest way to accept a payment. Your all-in cost can include an acquirer or gateway charge, tax on service fees, a terminal rental or purchase, and contract-specific settlement charges. Card category, merchant eligibility and transaction type also change the result. “Wallet” is not a single fee class, so you must identify the underlying instrument and read your provider agreement before comparing prices.
Start with the cost you actually want to compare
Merchants often compare a headline MDR percentage when the real question is: How much does one successful payment reduce my settlement? MDR is only one component. A useful comparison separates the following:
As an Amazon Associate I earn from qualifying purchases.
- Statutory or contracted MDR: the percentage or fixed amount charged on the transaction value for a particular instrument.
- Gateway or acquirer service charges: processing, platform, risk, reconciliation or other fees in the merchant agreement.
- Tax on services: applicable tax charged on a provider’s service fee, where the agreement makes the merchant responsible.
- Acceptance equipment: terminal purchase, rental, maintenance or connectivity costs for in-person card acceptance.
- Settlement terms: timing, reserves, refunds, chargebacks and other deductions shown on the settlement statement.
Compare the same transaction value, instrument, merchant category and settlement period. A zero-MDR line does not automatically mean zero cost if a separate provider fee remains. Conversely, a quoted card MDR may already include services that another provider bills separately.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →India’s UPI and RuPay debit baseline
No MDR direction effective 1 January 2020
The Reserve Bank of India’s Benchmarking India’s Payment Systems report records the government direction that MDR was not to be collected for UPI and RuPay debit-card transactions from 1 January 2020. This is the key reason these two rails are commonly treated as the low-cost starting point for merchant acceptance. The direction concerns MDR; it does not erase every possible gateway, acquirer, equipment or settlement charge in a commercial contract.
#1 Best Overall

- Use the, easy-to-use, and customizable POS to get started.
- Accept contactless payments, chip cards, Apple Pay, and Google Pay from anywhere, with improved connectivity, extended battery life, and enhanced security. Pay one low rate for every tap or dip.
- No long-term commitments or contracts, no monthly fees- and with offline payments, keep taking payments for up to 24 hours.
- Safely and securely accepts payments anywhere. Plus, get data security, 24/7 fraud prevention, and payment-dispute management at no extra cost.
- Use the, easy-to-use, and customizable POS to get started.
What the August 2026 government statement does—and does not—say
A Ministry of Finance statement published by the Press Information Bureau on 8 August 2026 says consumers will not face transaction charges and that person-to-person (P2P) transactions will remain free. It also says any MDR introduced for merchants would be limited, apply above a threshold and be lower than debit- or credit-card MDR. The statement describes an enabling legislative change and says the UPI and Services Steering Committee headed by NPCI would decide MDR, if any, after the bill passes.
That language does not establish a rate, a threshold amount, exempt merchant categories or an effective date. Do not enter a future UPI percentage into your pricing model until the enacted provision and implementation circulars specify those details.
The September 2026 select-UPI FAQ remains a point to verify
The Department of Financial Services lists an FAQ titled “Merchant Discount Rate (MDR) on Select UPI (P2M) Transactions,” dated 15 September 2026. The operational scope and effective date cannot be confirmed from the accessible official listing alone. Before relying on a new select-transaction rule, ask your acquiring bank or gateway for the written implementation notice and confirm it against the complete official FAQ or NPCI material.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Cards must be split into their actual categories
“Card” is not one price. RBI directed acquirers in 2016 to ensure that MDR are clearly unbundled for different categories of cards
, specifically requiring separate treatment for debit, credit and prepaid cards. A merchant statement that combines them hides the comparison you need.
| Instrument | What the official material establishes | How to use it in a current comparison |
|---|---|---|
| RuPay debit | The RBI report records no MDR collection from 1 January 2020 under the government direction. | Check whether your provider adds gateway, terminal, tax or settlement charges despite the MDR treatment. |
| Other debit cards | The RBI report describes a historical benchmark for businesses with annual turnover of at least ₹2 million: 0.9% of transaction value or ₹1,000, whichever was lower. | Treat this as a dated benchmark, not an automatic 2026 quote. Confirm the current rule, eligibility and contract. |
| Credit cards | The reviewed official material does not establish one universal current credit-card rate. | Require a separate credit-card line in the provider quote; do not infer it from debit or UPI pricing. |
| Prepaid cards | RBI’s unbundling direction identifies prepaid as a separate category. | Ask whether prepaid cards are priced with debit, credit or their own schedule. |
Understanding the historical debit benchmark
For an illustrative ₹1,000 transaction, 0.9% would equal ₹9, while the ₹1,000 cap would not bind. On a very large transaction, the “whichever is lower” condition matters. This arithmetic illustrates the old benchmark only; it is not evidence that every merchant currently receives that price. The report’s turnover condition, the age of the underlying rule and any later notifications all matter.
Why “wallet” has no single universal merchant fee
A wallet label can conceal different payment paths. A customer may pay from a stored wallet balance, a linked bank account, a card balance or a credit instrument presented through a UPI interface. Those paths can fall under different acquiring arrangements and pricing schedules.
Rank #2

- Fully Compliant - Complies With All Major Industry Standards, Including Iso/Iec 7816, Usb Ccid, Pc/Sc, And Microsoft Whql. As Well As, Emv 2011 Ver 4.3 Level 1 And Gsa Fips 201.
- Seamless Integration - With Identiv-Specific Smartos You’Ll Get Easy, Complete Support Of All Major Contact Smart Card Ics And Technologies In One Simple Reader.
- Universal Compatibility - Works With Virtually All Contact Chip Cards And Pc Operating Systems, Including Windows, Macos, Linux And Android.
- Fast And Convenient- Shorten Your Transaction Time With A Reader That’S Optimized For Speed. It’S Ultra-Compact And Robust Design Is Streamlined For Mobile Operation, Making This Reader The Best Choice For Convenience, Security And Reliability.
- Ergonomic and cost efficient design
The official sources reviewed do not publish one current merchant rate that applies to every wallet or gateway. Ask the provider to identify, for each wallet brand or method you enable:
- the underlying instrument and network;
- the MDR or fixed charge for that instrument;
- any gateway, acquiring, platform or risk fee;
- tax applied to service charges;
- refund, dispute and chargeback deductions; and
- the settlement timing and reconciliation fields.
Do not classify a wallet as “free” merely because the customer sees no fee. Customer pricing and merchant acceptance pricing are separate.
Compare methods on the same decision axes
| Axis | Questions to ask | Why it changes the answer |
|---|---|---|
| Rail and instrument | Is it bank-account UPI, RuPay debit, another debit card, credit, prepaid or a wallet balance? | Each category can have a different legal treatment and provider schedule. |
| Merchant eligibility | What annual turnover, merchant category, transaction type or value threshold applies? | Eligibility can determine whether a cap, exemption or proposed select-UPI rule applies. |
| All-in successful-payment cost | What is deducted from a ₹X sale after MDR, service fees and applicable tax? | A headline MDR may omit charges that reduce settlement. |
| Acceptance setup | Do you need a physical terminal, and is it bought, rented or bundled? | Equipment and connectivity can dominate low-volume in-person costs. |
| Settlement and operations | When are funds settled, and what are the refund, reserve and reconciliation terms? | Cash-flow and administration costs are part of operating cost even when MDR is low. |
| Contract duration | Are rates promotional, recurring, volume-tiered or subject to a minimum? | A first-month quote may not represent the recurring cost. |
Calculate your real cost per successful payment
Use a transaction-level worksheet rather than comparing percentages in isolation. Create one row for each instrument your business accepts.
- Record the gross sale value. Use a representative basket size and also test your smallest and largest common transactions.
- Identify the exact instrument. Separate bank-account UPI, RuPay debit, other debit, credit, prepaid and each wallet route.
- Apply the quoted MDR or fixed fee. Preserve the provider’s conditions, such as turnover, transaction type, threshold and volume tier.
- Add separate provider charges. Include gateway, acquiring, platform, risk, reconciliation and per-transaction fees listed in the agreement.
- Add applicable tax on services. Keep tax on a service fee distinct from the transaction amount and verify whether it is recoverable or included in the quote.
- Allocate equipment costs where relevant. For a terminal, divide recurring rental and connectivity charges by expected monthly successful transactions; include purchase cost over the period you use for comparison.
- Subtract refunds or disputes only as your agreement specifies. Do not assume a reversed payment returns every original fee.
- Check the settlement statement. Reconcile the calculated deduction with an actual statement before changing your acceptance mix.
The result is an all-in cost per successful payment and an effective percentage of the sale. Keep the statutory MDR line separate so a later policy change can be modelled without rebuilding the entire worksheet.
In-person merchants: terminal cost is a separate decision
RBI describes acceptance infrastructure as essential for card payments. A shop accepting physical cards may therefore need a point-of-sale terminal, while a QR-only setup may not. Terminal economics include:
Recommended Free Tools
- purchase price or recurring rental;
- installation, replacement and maintenance;
- SIM, data or network connectivity;
- compatibility with the acquiring bank and card categories;
- receipt, reconciliation and integration features; and
- contract minimums or cancellation terms.
Request written confirmation that the terminal supports every card and wallet category you advertise. A terminal that accepts only selected rails can make a nominally cheap MDR irrelevant if customers cannot complete the payment.
Rank #3

- INTEGRATED DESIGN - The integrated-designed BENFEI USB-C/USB 3.0 card reader provide high data speed access to four different card types, the SD(Secure Digital), Micro SD(TF), MS(Memory Stick) and CF(Compact Flash). And with 2in1 USB-C/USB 3.0 design, BENFEI card reader could works with computer or laptop by USB 3.0/2.0 slot or the latest USB Type-C(Thunderbolt 3) slot. A universal card reader solution.
- INCREDIBLE PERFORMANCE - With latest USB Type-C or the USB 3.0 port, fully enjoy the transfer rates in UHS-I mode up to 160MB/sec, backward Compatible with USB 2.0/1.1. Browse and view photos instantly on your USB-C/USB3.0 smartphones/laptops. (NOTE: The final data speed is decided by the card and USB slot Type )
- SUPERIOR STABILITY - Built-in advanced IC chip handle the USB-C/USB high speed data transfer signal, allow HD movies trasfer in just seconds. ✅ It is a simultaneously card reader and can read 4 card at the same moment
- BROAD COMPATIBILITY - Compatible with MacBook Pro 2019/2018/2017/2016, MacBook 2017/2016/2015, iPad Pro 2018, Surface Book 2, Samsung Galaxy S10/S9/S8/Note 8/Note 9, HTC U11/U12, Pixelbook, Dell XPS 15 / XPS 13, Galaxy Book, and many other USB-C Devices. NOTE: SDXC cards (capacity at 64GB or larger) use a special file format "exFAT", which is not supported in Windows XP, Windows Vista before SP1, and Mac OS X before 10.6.6). ❗ Incompatible with Memory Stick (Standard),Memory Stick Micro (M2) and CF Type I
- 18 MONTH WARRANTY - Exclusive BENFEI Unconditional 18-month Warranty ensures long-time satisfaction of your purchase; Friendly and easy-to-reach customer service to solve your problems timely.
Online merchants: separate gateway pricing from the rail
An online checkout can present UPI, cards and wallets through one gateway, but a single dashboard percentage may blend several instruments. Ask for a downloadable schedule with separate rows for each method. Confirm whether the quoted amount includes authentication, fraud screening, retries, refunds, chargebacks, settlement reports and tax.
When a gateway routes a credit instrument through a UPI interface, classify the transaction according to the provider’s documented pricing and the applicable rule—not simply by the appearance of a UPI button. The interface and the underlying funding instrument are not necessarily the same cost category.
How different merchants should choose
Small business below a stated turnover threshold
Do not assume the historical ₹2 million turnover benchmark applies or does not apply without checking the current agreement. Compare the provider’s fixed charges and terminal or gateway costs, because a small number of monthly transactions can make a recurring fee more important than a fraction of a percentage point.
High-volume retail with many card transactions
Insist on unbundled debit, credit and prepaid pricing and calculate the weighted average using your actual transaction mix. A lower debit rate will not compensate for an expensive credit-card share if most customers use credit.
QR-first or mobile merchants
Compare the UPI route’s all-in deductions with any wallet or gateway alternatives, then verify settlement timing and reconciliation. If you accept only bank-account UPI, document that scope; adding another instrument can change the applicable fee schedule.
Businesses that need card acceptance
Include terminal acquisition and operating costs, support and uptime commitments in the decision. A method with a low MDR but unreliable acceptance can create more operational cost through failed sales and manual reconciliation.
Rank #4
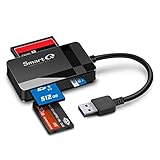
- SmartQ C368 USB 3.0 Card Reader: Four-in-one design, supports Micro SD/SD/MS/CF cards, and reads data independently; ideal for plug and play mobile use during travel.
- High data transfer speed: Supports data transfer speed up to 5GB per second (at USB 3.0 speed), compatible with USB 3.0 and USB 2.0 multi-card readers for CF and MicroSD cards.
- Multi-system compatibility: Compatible with Windows/Mac OS/Linux and other systems, no driver needed, enjoy a plug and play experience.
- Working status: Blue LED light indicator, the indicator LED lights up when powered on, the device status is clearly visible.
- In the Box: SmartQ C368 USB 3.0 Card Reader (memory card not included), Cable organizer, User manual.
Government incentives are not automatically a merchant rebate
The Ministry of Finance release of 19 March 2025 describes an approved incentive scheme for low-value BHIM-UPI person-to-merchant transactions for financial year 2024–25 and reports earlier government payouts of ₹1,389 crore in FY2021–22, ₹2,210 crore in FY2022–23 and ₹3,631 crore in FY2023–24. The release’s table splits amounts between RuPay debit and BHIM-UPI.
Those figures are government payments to acquiring banks and ecosystem participants. They are historical programme payouts, not a fee rate that every merchant can deduct from a settlement. If a provider passes through an incentive, it must appear in your written agreement or statement; do not count it without that evidence.
Common comparison mistakes and fixes
Calling every UPI transaction free
Problem: A consumer-facing no-charge statement is treated as a guarantee of zero merchant cost for every UPI route.
Fix: Separate P2P from person-to-merchant transactions, identify the funding instrument and check the provider’s current contract. Future select-transaction MDR details remain subject to official implementation.
Using the old debit cap as today’s price
Problem: The 0.9% or ₹1,000 benchmark is copied into a current rate card without its date and ₹2 million annual-turnover condition.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Fix: Label it as the RBI report’s historical benchmark and obtain a current written quote.
Best Value

- Advanced Realtek Chipset; PIV, EMS, ISO-7816 & EMV2 2000 Level 1, CE, FCC, VCCI and Microsoft WHQL certifications.
- Supports ActivClient, AKO, OWA, DKO, JKO, NKO, BOL, GKO, Marinenet, AF Portal, Pure Edge Viewer, ApproveIt, DCO, DTS, LPS, Disa Enterprise Email and etc. CAC chip cards
- Sleek ergonomic flat design, precise slot, convenient to horizontally plug card
- Compatible with Windows10/11, Mac OS 10.15 or later. Driver free, plug and play.
- New generation DOD Military CAC USB smart chip card reader, no firmware upgrade requirements
Combining debit, credit and prepaid in one “card” row
Problem: The blended figure hides the expensive category.
Fix: Require unbundled MDR and calculate a weighted average from actual volumes.
Ignoring equipment and settlement deductions
Problem: A zero-MDR method appears cheapest until terminal rental, gateway fees or tax is deducted.
Fix: Reconcile one month of statements and allocate recurring acceptance costs per successful payment.
Relying on a verbal or promotional quote
Problem: The rate changes after a trial period, volume tier or contract renewal.
Fix: Keep the complete rate card, eligibility conditions, tax treatment, settlement schedule and termination terms with your records.
Merchant checklist before switching or adding a method
- List every instrument and wallet route you currently accept.
- Record your annual turnover, merchant category, average ticket and transaction range.
- Obtain separate MDR lines for RuPay debit, other debit, credit, prepaid, bank-account UPI and each wallet route.
- Ask whether any rate is statutory, promotional, volume-tiered or contract-specific.
- Request all gateway, acquiring, platform, refund, dispute, reserve and reconciliation fees.
- Confirm tax on service charges and whether quoted amounts are inclusive or exclusive.
- For physical acceptance, price terminal purchase or rental, connectivity, maintenance and compatibility.
- Check settlement timing and compare a provider statement with your own calculation.
- Verify any claimed select-UPI exemption, threshold or effective date against the complete official notice.
- Recalculate the weighted all-in cost after a material change in your payment mix.
Bottom line for Indian merchants
The policy baseline makes bank-account UPI and RuPay debit attractive on MDR, while other debit, credit, prepaid and wallet routes require category-specific pricing. The RBI’s 0.9% or ₹1,000 debit benchmark is historical and conditional, not a universal 2026 rate. The August 2026 statement points to a possible, limited, threshold-based UPI MDR but supplies no enacted rate or start date, and the exact scope of the September 2026 select-UPI FAQ still needs confirmation.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsChoose the method that produces the lowest all-in cost for your actual transaction mix, not the lowest headline percentage. Compare your current merchant statement with a written, unbundled provider quote, include equipment and service charges, and revisit the calculation whenever policy or contract terms change.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

