For U.S. deposits, neither one bank nor several is automatically safer in every way. The key insurance rule is $250,000 per depositor, per FDIC-insured bank, per ownership category. If your deposits in a category at one bank—including accrued interest—fit within that limit, another bank does not increase your insurance for those funds. A second separately insured institution can add coverage for amounts above the limit and may provide another way to access money, but it also means managing another account.
What “safer” means for emergency savings
There are two different questions: whether deposits are protected if an institution fails, and whether you can reach money if one institution’s services are unavailable. Deposit insurance addresses the first. A separate account at another institution may offer a practical backup access route, but it does not guarantee access during every outage or protect against fraud, theft, account takeover, or all delays.
As an Amazon Associate I earn from qualifying purchases.
The Federal Deposit Insurance Corporation (FDIC) says it acts quickly to ensure access to insured deposits after a bank failure. It also states: “Since 1934, no depositor has lost a penny of their FDIC-insured funds.” That statement applies to FDIC-insured funds, not every balance or financial product a bank customer may hold. FDIC: Deposit Insurance FDIC: Understanding Deposit Insurance
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
How much of your money is insured?
The FDIC’s standard limit is $250,000 per depositor, per insured bank, per ownership category. The FDIC aggregates deposits in the same ownership category at the same bank, rather than applying a fresh limit to each account. For example, a person’s single-owned checking and savings accounts at one insured bank generally count together as single accounts. Moving money between those accounts does not create additional coverage. FDIC: Deposit Insurance
#1 Best Overall
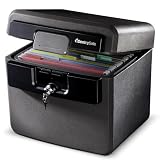
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
- Separate banks: Deposits at separately insured banks are evaluated separately.
- Separate branches: Branches of the same insured bank do not create separate insurance limits.
- Different ownership categories: Some categories may qualify for separate coverage at one bank, but only when their specific requirements are met. Account count or a changed title alone does not establish extra coverage.
- Interest: FDIC coverage includes principal and accrued interest through the date a bank closes. Leave room below the limit if a balance is close to it.
Common FDIC ownership categories include single, joint, certain retirement, trust, employee benefit plan, business, and government accounts. Complicated ownership arrangements should be checked with the FDIC’s estimator or an appropriate professional rather than inferred from a general example. FDIC Electronic Deposit Insurance Estimator (EDIE)
One bank or several: the practical trade-offs
| Approach | Insurance effect | Access and administration |
|---|---|---|
| One insured bank | Coverage depends on the combined balance in each ownership category at that bank; the standard limit is $250,000 per depositor, per bank, per category. | Fewer accounts and relationships to manage, but funds may depend on that institution’s services for access. |
| Several separately insured banks | Each institution is assessed separately, so this can increase coverage for balances above the applicable limit at one bank. | A second relationship may provide another access route. Transfers, statements, passwords, fees, minimums, and contact details require additional attention. |
| Several accounts or branches at the same bank | Accounts in the same ownership category are generally aggregated; separate branches do not count as separate insured banks. | More accounts may mean more administration without increasing coverage in that category. |
There is no official comparative statistic establishing that one-bank or multi-bank emergency savings are safer overall. The insurance rules define coverage; the usefulness of another account for access depends on your circumstances.
Rank #2

- PROTECTS VALUABLES: 1.8-cubic-foot home safe for safeguarding important documents, jewelry, cash, devices, and other precious items
- RELIABLE SAFETY: This safe box features a programmable electronic keypad for secure, easy operation, along with a back-up key for emergency access; requires AA batteries (not included)
- DURABLE CONSTRUCTION: This mini safe is built with heavy-duty steel, including an 8-gauge steel door and 14-gauge steel body, as well as 2 live-door bolts and pry-resistant concealed hinges
- CONVENIENT ORGANIZATION: This safe for home includes an interior shelf to help keep your belongings neatly organized and easily accessible
- EASY INSTALLATION: Comes with pre-drilled mounting holes and hardware, making it simple to securely mount this mini safe box to the floor or wall
Check coverage before moving money
- Group deposits by institution and ownership category. Add relevant checking, savings, money market deposit accounts, and certificates of deposit (CDs). Include accrued interest when a balance is near the limit.
- Confirm the insured institution. Check the legal institution, not only its brand, branch network, or account label. The FDIC’s BankFind tool can help identify insured banks: FDIC BankFind Suite.
- Estimate bank coverage. Use EDIE for an estimate, and seek regulator or qualified professional help if trusts, business accounts, joint ownership, or pass-through arrangements make the calculation complex.
- Consider a separate insured institution if needed. If deposits exceed the applicable insured amount, another separately insured institution may add coverage. Compare access, fees, and account terms before moving funds; the insurance guidance does not establish those terms for a specific account.
- Decide whether backup access is useful. A second account can be a practical alternative route for the household, but should not be treated as protection from every outage, fraud event, or delay.
What deposit insurance does—and does not—cover
FDIC insurance covers qualifying deposits, including savings and checking accounts, money market deposit accounts, and CDs. It does not insure stocks, bonds, mutual funds, annuities, or other investment products simply because they were bought through an insured bank. FDIC: Understanding Deposit Insurance
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Credit unions use a distinct federal system. Federally insured credit-union share accounts are generally covered under National Credit Union Administration (NCUA) rules up to $250,000 per depositor, per insured credit union, for the applicable ownership category. NCUA rules also aggregate single-ownership accounts held by the same person at one insured credit union; joint accounts have requirements, including equal withdrawal rights, and co-owners’ interests are aggregated. Verify the institution’s insurance and applicable category rather than assuming that a bank calculation transfers unchanged. NCUA: Share Insurance FAQs
Quick Recap
Rank #3
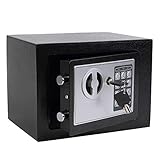
- STRONG & SECURE:Digital Locking- the Electronic Safety Lock Box Is Equipped with an Easy to Program Digital Keypad That Is Simple to Lock and Unlock by Entering Your Security Combination. Two Emergency Keys Are Included for Faster and More Immediate Access.
- SMART CAPACITY:0.2-cubic-feet, Exterior :9.05" x 6.69"x 6.69", Interior size: :6.29" x 8.9" x 5.12" (Pls pay full attention to the dimension for this MINI safe box),It gives you easy personal access to your valuables .
- STRONG & SECURE: The mini safe box is made of reinforced solid steel wall construction. Dual security steel door locking bolts & a corrosion & stain-resistant powder coat finish keeps the drop box safe.
- Durable powder coated finish, Magnetic lock for auto-locking;
- Easy to install: The home safe box has pre-drilled holes for wall or floor mounting, Includes mounting bolts.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

