Recommended Free Tools
For U.S. government bonds, you can buy Treasury securities directly or buy shares in a mutual fund or ETF that holds government debt. Direct ownership lets you choose a security and maturity; a fund offers a managed portfolio but does not promise a particular maturity payment. U.S. Treasury rules below are specific to the United States—other countries use different issuers and purchase channels.
Choose what you want to own
Buying an individual bond means you own a specific security with stated payment terms and a maturity date. Buying a bond fund means you own fund shares; the fund owns and manages a portfolio of bonds. That difference matters most if you need a known cash-flow date or may sell before maturity.


As an Amazon Associate I earn from qualifying purchases.
How to buy individual U.S. Treasury securities
U.S. Treasury marketable securities include bills, notes, bonds, Treasury Inflation-Protected Securities (TIPS), and floating rate notes (FRNs). They are electronic book-entry instruments backed by the full faith and credit of the United States.
- Bills: Short-term securities that mature in one year or less. TreasuryDirect lists terms from four weeks to 52 weeks. Bills do not pay periodic interest; they are sold at face value or at a discount, with the difference paid at maturity.
- Notes: Two-, three-, five-, seven-, or 10-year securities that pay fixed interest every six months.
- Bonds: Long-term securities with 20- or 30-year maturities; they pay interest every six months.
- TIPS and FRNs: These have inflation-adjustment and floating-rate features, respectively. Review their terms before buying because their payment mechanics differ from fixed-rate notes and bonds.
Buy at auction
Individuals can buy new marketable Treasury securities at auction through a TreasuryDirect account or through a bank, broker, or dealer. TreasuryDirect accepts noncompetitive bids: you agree to accept the rate or yield set at auction. A competitive bid, submitted through a financial intermediary, specifies the return you will accept; it may be filled in full, in part, or not at all.
#1 Best Overall
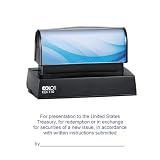
- DESIGNED FOR RESTRICTIVE ENDORSEMENTS – Specifically created for endorsing U.S. Bearer Securities and securities payable to bearer, including U.S. Treasury bonds, Treasury notes, Treasury bills, and certificates of indebtedness. Once applied, the endorsement restricts the instrument to deposit only, supporting proper handling during banking and financial transactions.
- COMPLIES WITH U.S. TREASURY GUIDELINES – Stamp layout, wording, and impression size are designed to align with applicable U.S. Government Code of Federal Regulations, including CFR 328.5 and 328.6. The COLOP pre-inked stamp meets the approximate required impression size of 4 inches in length and 1-1/2 inch in height.
- MULTIPLE LAYOUT VERSIONS AVAILABLE – Offered in five different endorsement versions to meet varying banking requirements. Version 1 is the most commonly used. For Versions 2–5, the applicable Federal Reserve Bank city must be specified so it can be incorporated into the stamp design.
- PRE-INKED COLOP STAMP FOR CLEAN, CONSISTENT IMPRESSIONS – Features a premium COLOP pre-inked mechanism that delivers clear, uniform impressions without the need for a separate ink pad. Ideal for frequent use in banking offices, accounting departments, and financial institutions.
- ESSENTIAL TOOL FOR BANKING & FINANCIAL USE – Restrictive endorsement stamps are widely used for checks, securities, and financial documents to help ensure items are directed only to the intended account. Commonly used by banks, credit unions, treasury departments, and corporate finance teams.
TreasuryDirect currently states a $100 minimum purchase, in $100 increments. It also says a newly purchased marketable security generally must remain in TreasuryDirect for at least 45 calendar days before it can be transferred or sold. The page notes an exception for securities bought using reinvestment of a maturing security. Confirm current service terms before placing an order.
Buy or sell in the secondary market
You can also buy existing marketable Treasuries—or sell a Treasury you own—through a financial institution or broker. A sale before maturity is at the market price, which may be above or below face value. The price depends in part on prevailing rates, the security’s coupon and remaining maturity, and transaction terms.
Rank #2
When a note, bond, TIPS, or FRN is reopened or newly issued, the purchase price may include accrued interest. TreasuryDirect explains that the buyer pays this as part of the price and receives it back in the next regular interest payment. Bills do not pay periodic interest and are treated differently.
Understand the price you pay
A note or bond can trade above or below its face value. If its yield to maturity is higher than its coupon rate, its price is below face value; if the yield is lower than the coupon, its price is above face value. The coupon rate is not the same as your yield when you pay a price other than face value.
How government bond funds work
A bond fund may be a mutual fund, ETF, closed-end fund, or unit investment trust. Some funds focus on government debt; others mix it with corporate, mortgage-backed, municipal, or other securities. The fund’s name alone does not establish its exact government exposure, credit quality, maturity range, duration, or use of derivatives.
With a fund, one investment can provide exposure to a portfolio managed under a stated strategy. The fund may buy and sell securities or replace holdings as bonds mature. Your shares fluctuate in market value or net asset value, and a conventional bond fund does not promise that your investment will reach a particular value on a particular date. You own shares, not a claim to the maturity payment of one underlying bond.
Before investing, review the prospectus, latest shareholder report, current portfolio, and expense information. Compare the fund’s mandate, holdings, maturity profile, duration, distribution policy, fees, and any trading costs with your goal.
Free tools Windows power users keep installed
One-click scans. No signup required.
What can make a government bond investment lose value?
Interest rates and market prices
The U.S. Securities and Exchange Commission’s Office of Investor Education and Advocacy states: “A fundamental principle of bond investing is that market interest rates and bond prices generally move in opposite directions.” When rates rise, an older fixed-rate bond may need to fall in price to compete with newer bonds. Longer maturities generally have greater interest-rate sensitivity than otherwise similar shorter maturities.
An individual Treasury held to maturity can return its face value at maturity, along with its contractual interest, assuming the U.S. government meets its obligations. Its market value can still fall before maturity, and selling then means accepting the current price. A bond fund can also lose value when rates rise, including a fund invested only in government bonds. Longer-duration portfolios generally move more when rates change.
Other risks and purchasing power
Government backing concerns the issuer’s payment obligations; it does not prevent market-price declines on a sale, protect a fund’s share price, or stop inflation from reducing purchasing power. The SEC’s general list of bond risks includes interest-rate, inflation, liquidity, credit, and call risk. U.S. Treasury issuer credit risk is generally viewed as minimal compared with that of many other issuers, but price risk remains. Funds that hold non-Treasury government-related or mortgage securities can have risks that differ from a fund holding only Treasuries. Neither an individual bond sold early nor a government bond fund should be described generally as “risk-free.”
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Compare the two routes against your goal
| Question | Individual Treasury | Government bond fund |
|---|---|---|
| Is there a maturity date for my investment? | The security has a stated maturity and payment terms. | The fund shares do not mature when the fund’s underlying bonds mature. |
| How much control do I have? | You select securities and can coordinate maturities or cash-flow dates with a goal. | The manager follows the fund’s strategy, which may maintain a target duration or maturity range. |
| How do I get diversified exposure? | You select and manage each holding yourself. | One fund holding can provide exposure to a portfolio of bonds. |
| What if I need the money early? | The sale price matters; it may be above or below face value. | Shares remain market-priced investments and can decline in value. |
| What should I check about costs? | Check any brokerage charges, bid-ask spreads, transaction fees, minimums, and account terms. | Check the expense ratio, trading costs, and any applicable brokerage charges or account terms. |
| How do I confirm the exposure? | You select the specific Treasury security. | Check the fund’s holdings and documents; the name alone may not show whether it owns only Treasuries or broader government-related securities. |
Neither route is universally better. The relevant trade-offs are your time horizon, need for predictable cash flows, preference for diversification, willingness to manage maturities, and ability to tolerate interim price changes.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Quick Recap
Sources and scope
- U.S. Treasury: Marketable securities explains Treasury security types and terms.
- U.S. Treasury: Treasury bills provides bill details.
- U.S. Treasury: Treasury notes provides note details.
- U.S. Treasury: Treasury bonds provides bond details.
- U.S. Treasury: Buying a marketable security describes auction and purchase mechanics.
- SEC Investor.gov: Bonds discusses bond features and risks.
- SEC Investor.gov: Mutual funds and ETFs explains fund basics.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

