Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteCompare Titan with other listed jewellery and watch businesses in layers, not by placing one headline revenue or price-to-earnings number beside another. First choose genuinely comparable companies and segments; then align fiscal periods, consolidation scope and accounting definitions; separate jewellery, watches and Titan’s other activities; test growth against margins, cash and capital needs; and only then calculate valuation using share prices and balance-sheet data from the same date.
This method can tell you whether two businesses are economically comparable and what assumptions a market price implies. It cannot, by itself, produce a buy or sell instruction.


As an Amazon Associate I earn from qualifying purchases.
Why a simple Titan-versus-peer comparison fails
Titan Company Limited is a diversified group rather than a pure-play jeweller or watchmaker. Its FY2025–26 annual report covers jewellery, watches, eyewear, fragrances and women’s bags, Indian dress wear, and engineering and automation activities. A jewellery-focused company’s consolidated margin, store count or earnings cannot therefore be compared fairly with Titan’s group total without first isolating the relevant business.
Reporting scope creates a second problem. One issuer may show statutory consolidated revenue, another may highlight an adjusted operating measure, and a quarterly release may exclude categories that appear in the annual accounts. Titan’s Q4FY26 release, for example, says its stated total income excludes bullion and Digi-gold sales and that profit is before exceptional items. Kalyan Jewellers reports one operating segment—jewellery. Those figures answer different questions unless you document the difference.
#1 Best Overall
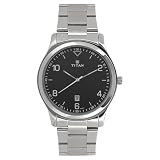
- Dial Color: Black, Case Shape: Round, Dial Glass Material: Mineral
- Band Color: Silver, Band Material: Metal
- Watch Movement Type: Quartz, Watch Display Type: Analog
- Case Material: Brass, Case Diameter: 49.3 millimeters
- Water Resistance Depth: 50 meters, Push Button Clasp
Finally, a fast-growing company is not automatically a high-return stock. Shareholder return depends on the price paid, dilution, cash generation, debt, reinvestment requirements and the expectations already embedded in the multiple.
1. Choose peers that match the question
For jewellery
A listed jewellery-focused issuer such as Kalyan Jewellers is a more direct operating comparison for Titan’s jewellery division than Titan as a whole. It still differs in brand portfolio, geography, store formats, wholesale exposure, international operations and accounting mix. Treat it as a reference point, not a like-for-like twin.
For watches
Use Titan’s watch-division disclosures and compare them with companies that disclose watch-focused economics. A diversified consumer company that happens to sell watches is not automatically a watch peer. If a potential peer does not report watch revenue, margins or capital requirements separately, mark the comparison as limited rather than assigning it a false precision.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchRecord the identity of every peer
Before putting a company into a spreadsheet, create a profile containing:
- Exchange listing and ticker.
- Financial year-end and the date of the latest audited report.
- Operating segments and the segment that actually matches your question.
- Geographic exposure, including domestic and international stores.
- Retail, wholesale, franchise and online mix.
- Whether the figures are standalone or consolidated.
- Acquisitions, demergers or newly consolidated subsidiaries during the comparison period.
The material available here supports Kalyan as a jewellery peer but does not establish a complete current peer universe. Add companies only after they pass the same documentation test.
2. Put every financial number on the same basis
Use the same fiscal period and, wherever possible, the same consolidated or standalone basis for every issuer. Write the basis in each spreadsheet column; do not rely on a note at the top that can be forgotten when the table is updated.
Period and consolidation checklist
- Use financial years ending on the same date, or bridge the periods explicitly when dates differ.
- Use consolidated statements for groups with material subsidiaries. Do not compare one company’s consolidated sales with another’s parent-only sales.
- Check whether an acquisition entered the reported period part-way through the year.
- Separate reported growth from pro-forma growth when a business was not owned for the full prior period.
- Keep quarterly measures separate from annual measures and preserve each release’s definition.
Titan’s FY26 results include Damas consolidation from Q4FY26 according to the issuer release. That can make a year-on-year international jewellery comparison look stronger than the underlying operations if the prior-year base did not contain the same contribution.
Definitions that need a note
Revenue may include or exclude bullion, Digi-gold, inter-segment sales, excise or other pass-through items. Profit may be before or after exceptional items. EBITDA, EBIT and operating profit are not interchangeable when leases, stock-based compensation, inventory revaluation or other adjustments differ. Copy the issuer’s definition beside the number and use a consistent adjustment only when the underlying statements support it.
3. Keep Titan’s businesses separate
Titan’s FY2025–26 annual report reports the following issuer figures for the year ended 31 March 2026:
| Measure | Reported figure | How to use it |
|---|---|---|
| Jewellery revenue | ₹61,148 crore | Excludes ₹9,960 crore of bullion sales; use for jewellery-focused operating analysis, not as Titan’s total revenue. |
| Watches revenue | ₹5,233 crore | Use when comparing the watch division, subject to each peer’s own scope. |
| Total revenue from operations | Grew 41% | Group-level growth across Titan’s businesses; not a jewellery-only or watch-only rate. |
| Net profit | ₹4,630 crore | Group result; do not attribute it entirely to jewellery or watches. |
| Watches revenue growth | 14% year on year | Division-level growth, unlike the group revenue-growth figure. |
These numbers are from Titan’s FY2025–26 Annual Report. The report also covers businesses outside jewellery and watches, so a group price-to-sales or margin comparison with a single-segment jeweller can mislead.
Titan’s separate FY26 results release provides quarterly business information and states that total income excludes bullion and Digi-gold sales and that profit is before exceptional items. Do not merge those quarterly figures into annual statutory totals without carrying those qualifications into the table.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →4. Use Kalyan’s figures as orientation, not a direct scorecard
Kalyan Jewellers India Limited’s FY26 issuer materials report ₹35,743 crore of consolidated revenue and ₹1,350 crore of profit after tax, with reported growth of 43% and 86%, respectively. Kalyan reports jewellery as one segment. Those figures are useful for understanding scale and the pace reported by a jewellery-focused group, but they are not a direct profitability comparison with Titan’s diversified group numbers.
| Issuer figure | Reported FY26 amount | Scope caution |
|---|---|---|
| Kalyan consolidated revenue | ₹35,743 crore | Jewellery-focused group; compare with Titan jewellery on an aligned basis, not Titan total revenue. |
| Kalyan consolidated PAT | ₹1,350 crore | Check accounting policies, exceptional items and minority interests before comparing margins. |
| Reported revenue growth | 43% | Growth can include price, volume, store additions, acquisitions and mix changes. |
| Reported PAT growth | 86% | Investigate operating leverage and one-off effects rather than treating it as a sustainable rate. |
Use Kalyan’s audited consolidated results and its 8 May 2026 FY26 results release for the exact statement labels and notes. The FY2024–25 annual report is particularly relevant when checking prior-year comparability and unusual inventory effects.
5. Compare operating quality, not just sales growth
Build an operating scorecard for each matched segment. Show the reported value, your formula and the period beside every metric.
Growth and margin
- Revenue growth, with price and volume separated where management supplies the split.
- Same-store sales growth, using each issuer’s definition of a comparable store and period.
- Gross margin and the treatment of bullion, making charges, inventory valuation and hedging gains or losses explicit.
- EBITDA or operating margin, followed by EBIT and net margin.
- Profit growth after checking whether the comparison includes exceptional items.
Gold-price inflation can raise reported jewellery sales without a proportionate increase in units sold. Ask whether growth came from higher gold prices, more grams sold, new stores, acquisitions, premiumisation or a change in product mix. If an issuer does not provide a comparable decomposition, say so instead of estimating one.
Cash and working capital
- Cash flow from operations and the conversion of operating profit into cash.
- Inventory days, inventory turnover and the amount of cash tied up before festive selling periods.
- Receivable and payable days, including whether supplier credit funds expansion.
- Capital expenditure, store fit-out spending and maintenance capex.
- Free cash flow after clearly stated capex and working-capital treatment.
A retailer can report rising profit while cash is absorbed by inventory or store construction. Compare at least one full annual cycle and investigate a divergence rather than ranking companies by PAT alone.
Stores and productivity
- Opening and closing store counts, net additions and company-owned versus franchise locations.
- Sales per mature store or per square foot where disclosed.
- Same-store growth for mature locations, not only total network growth.
- Rent and lease liabilities, refurbishment requirements and store payback.
- Online mix and the capital needed to support fulfilment and customer acquisition.
Store additions are expansion, not proof of profitable expansion. A useful comparison asks how quickly new locations mature, what they cost and whether returns exceed the company’s cost of capital.
6. Adjust for gold, inventory and exceptional items
Gold-price movements affect ticket size, customer affordability, demand timing and the rupee value of inventory. Review the gold-price context for each period and distinguish price effects from volume effects wherever disclosures permit.
Rank #4

- BIG FACE MINIMALIST STYLE: This 44mm Fossil watch for men features a cream satin dial with Roman numeral stick indices, three-hand movement plus a leather strap; inspired by mid-century modern design, the slim timepiece honors balance and proportion
- BIG FACE DURABILITY: 44mm case, 22mm band width, hardened mineral crystal lens resists scratches, accurate Quartz movement with 3-hand analog display, imported minimalist watch for men
- SOPHISTICATED DIAL: Round silver stainless steel case, with a cream satin dial and silver accents for a refined men's dress watch
- ADJUSTABLE COMFORT: Brown genuine leather band on this mens leather watch offers a secure adjustable buckle for a customized fit; interchangeable with all 22mm Fossil straps
- SWIM-READY DURABILITY: Water resistant up to 30m (100ft): This Fossil men's watch is suitable for bathing, swimming or snorkeling, but is not resistant enough to withstand scuba diving; 3 ATM
Kalyan’s FY2024–25 annual report identifies a one-time inventory impact of about ₹1,240 million associated with a mid-year reduction in India’s import duty on gold. Treat that as company-reported context, then verify the treatment in the audited notes before making an adjusted-margin calculation. Do not automatically remove every unusual item: document why it is non-recurring and show reported and adjusted results separately.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →For each issuer, inspect:
- Inventory valuation policy and any revaluation or markdown charge.
- Hedging instruments, gains and losses, and whether they are included in operating profit.
- Exceptional items, impairment, restructuring and acquisition costs.
- Changes in import duty, tax or regulation that alter the year’s base.
- Whether bullion or Digi-gold is included in the numerator and denominator of a margin.
7. Measure returns per share and balance-sheet risk
Total-company profit growth can overstate what an individual share earns when the diluted share count rises. Include diluted earnings per share, weighted-average diluted shares and any material employee or acquisition-related issuance.
Pair earnings with the balance sheet:
- Gross debt, cash and net debt.
- Interest expense and coverage.
- Lease liabilities, especially for store-heavy formats.
- Working-capital facilities and undrawn liquidity.
- Return on invested capital or return on capital employed, calculated with the same adjustments for every peer.
State whether lease liabilities are included in invested capital and enterprise value. A company with a higher operating margin may still produce a lower equity return if it requires substantially more inventory, stores or lease commitments to generate each rupee of sales.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.8. Build a same-date valuation comparison
Valuation is only comparable when the market data and accounting period are aligned. The supplied issuer materials do not provide a same-date comparative share-price and multiple dataset, so no current “cheaper stock” conclusion follows from the reported figures above.
Collect the market inputs
- Choose a valuation date, preferably the latest trading close before publication.
- Record each company’s closing share price on that date from an official exchange or issuer source.
- Use diluted shares or a clearly defined share count from the latest filing.
- Capture cash, borrowings and lease liabilities from the latest balance sheet available at that date.
- Note corporate actions, splits, buybacks or rights issues that affect comparability.
Calculate consistent multiples
| Measure | Formula | Use and limitation |
|---|---|---|
| Market capitalisation | Share price × diluted shares | Shows the equity value investors are pricing. |
| Trailing P/E | Market capitalisation ÷ trailing diluted earnings | Use reported earnings for the same trailing period; identify exceptional items. |
| Forward P/E | Share price ÷ forward EPS | Label estimates, their date and their source; never present forecasts as reported facts. |
| EV/EBITDA or EV/EBIT | Enterprise value ÷ comparable operating profit | Align lease, stock compensation and other adjustments before ranking. |
| Price/sales | Market capitalisation ÷ revenue | Secondary for low-margin retail and sensitive to bullion scope. |
| Free-cash-flow yield | Free cash flow ÷ market capitalisation | Define maintenance and growth capex and explain working-capital treatment. |
Enterprise value should be defined consistently as equity value plus debt and lease liabilities, less cash, or according to another stated convention used for every company. Do not compare Titan’s adjusted quarterly EV/EBITDA with a peer’s annual statutory EBITDA.
Recommended Free Tools
Explain what the multiple is paying for
After calculating a multiple, test whether differences reflect growth, margin stability, brand mix, balance-sheet risk, capital intensity, governance and execution. A premium can be rational if the business has more durable growth or better returns; it can also be excessive if the assumptions require perpetual high growth. The multiple is an entry-price observation, not a verdict on management quality.
Best Value

- Blue Dial Style: Blue dial and silver-tone 38mm case pair with an adjustable brown crocodile-grain leather strap for daily wear
- Adjustable Leather Strap: A 20mm genuine leather band fits up to an 8-inch wrist circumference for secure, comfortable everyday wear
- Durable Construction: A 38mm brass case with a mineral glass crystal is built for everyday reliability through years of daily wear
- Indiglo Backlight: A quick push of the button illuminates the dial in the dark, whenever it's needed most, day after day
- Built to Last: A Timex watch is designed for durability and everyday reliability; every piece reflects our commitment to quality without compromise
9. Separate reported history from management outlook
Company forecasts and strategic explanations should be attributed to the issuer. Titan Watches CEO Kuruvilla Markose wrote in the FY2025–26 annual report: “The next phase for the Watches Division is about building on this momentum through innovation, stronger storytelling, specialised retail, and deeper horological expertise, so that India can emerge as a more meaningful voice in the world of watchmaking.” This is management’s outlook, not an independently established forecast.
When incorporating guidance, place it in a separate column from historical results and record the publication date. Later compare guidance with the reported outcome; do not blend an expectation into a historical growth rate.
10. A repeatable worksheet for your comparison
Create one row per company or matched segment and one column per item below:
- Fiscal year, report date and consolidated or standalone basis.
- Business segment and geographic scope.
- Revenue, growth and the issuer’s price-versus-volume explanation.
- Gross margin, operating profit, EBIT and net profit, each with its definition.
- Cash from operations, inventory days, capex and free cash flow.
- Store count, net additions, mature-store productivity and online mix.
- Diluted shares, diluted EPS, net debt and lease liabilities.
- Share price and market capitalisation on one stated date.
- P/E, EV/EBITDA or EV/EBIT, price/sales and cash-flow yield.
- One-off items, acquisitions, accounting qualifications and unresolved comparability issues.
Use a notes column for every number that excludes bullion, Digi-gold, exceptional items or newly consolidated operations. If a value is not disclosed, enter “not stated” and preserve the issuer and report date rather than filling the gap with an estimate.
Common mistakes to avoid
- Comparing Titan’s group revenue with a single-segment jeweller’s revenue.
- Adding bullion or Digi-gold to one company’s sales while excluding it from another’s.
- Mixing quarterly “before exceptional items” profit with annual statutory profit.
- Calling a stock cheap using share prices from different dates.
- Using total PAT growth without checking diluted EPS and share-count changes.
- Treating a gold-price-driven sales increase as equivalent to volume growth.
- Ignoring inventory, lease liabilities and store payback.
- Assuming every unusual charge is removable from earnings.
- Presenting management’s strategic ambition as a proven outcome.
- Ranking peers when the underlying segment, geography or accounting scope is not disclosed consistently.
What a defensible conclusion looks like
A sound comparison ends with a qualified statement such as: Titan’s jewellery or watches segment grew at a stated rate on a defined basis; the selected peer reported a different rate under its own scope; cash conversion, inventory, stores and diluted EPS explain part of the difference; and the valuation comparison uses a specified market date and consistent enterprise-value adjustments. If any of those links is missing, identify the gap instead of forcing a winner.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

