Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallCompare Dangote Cement with BUA Cement and Lafarge Africa using the same financial year, audited group accounts and consistent definitions. Start with earnings and margins, then test how much profit turns into cash, how debt and investment needs affect resilience, and what the shares cost on the same date. Dangote’s wider African operations make it especially important to separate group results from Nigeria-only results. Company size or a sharp one-year profit increase does not, by itself, show which share is the better investment.
Which listed companies belong in the comparison?
The relevant listed Nigerian cement-company peers in this comparison are Dangote Cement Plc, BUA Cement Plc and Lafarge Africa Plc. Compare all three for a listed-company view, but do not assume their reported group totals describe the same geographic business: Dangote Cement operates in multiple African countries, while a Nigeria-only comparison requires Nigerian segment figures where disclosed.
As an Amazon Associate I earn from qualifying purchases.
What the FY2025 announcements show—and do not show
The following is a snapshot of figures highlighted in company FY2025 disclosures, not a complete like-for-like ranking. The figures are company-reported; verify them against each issuer’s full audited accounts and align accounting definitions and reporting scope before calculating ratios.
| Company | FY2025 figures reported | Capacity disclosed | Scope and comparison caution |
|---|---|---|---|
| Dangote Cement Plc | Group revenue: ₦4,306.7 billion; group EBITDA: ₦1,981.3 billion (FY2025, company investor-relations highlights). | Total installed capacity: 55.0 million tonnes per annum; Nigeria capacity: 32.25 million tonnes per annum (company disclosures). | Revenue and EBITDA are group figures; the group operates outside Nigeria. Do not compare group totals with a domestic-only peer figure as though their scope matched. |
| BUA Cement Plc | Revenue: ₦1.2 trillion; gross profit: ₦604.1 billion; profit after tax: ₦356 billion; EPS: ₦10.00 (FY2025 results announcement issued May 2026). The announcement reported revenue growth of 34.5% and PAT growth of 381.7% year on year. | Not stated in the cited FY2025 results announcement. | Growth rates are management-reported comparisons with FY2024, not forecasts. The cited announcement highlights do not provide a complete cash-flow and balance-sheet comparison. |
| Lafarge Africa Plc | Revenue: ₦1.1 trillion; operating profit: ₦392 billion; profit after tax: ₦273 billion; EPS: ₦17 (FY2025 results announcement issued February 2026). The announcement reported revenue growth of 53% and PAT growth of 173% year on year. | Installed cement capacity: 10.5 million tonnes per annum (company investor-relations disclosure). | Use the audited accounts to confirm statement lines, scope and exceptional items before comparing with peers. |
These announcement highlights do not all report the same profit measure: BUA’s cited highlight includes gross profit, Dangote’s includes EBITDA, and Lafarge’s includes operating profit. They also do not establish a complete, comparable set of audited cash flow, debt, volumes or valuation figures. BUA reported the largest headline PAT among these cited announcement figures; Dangote reported substantially larger group revenue and EBITDA. Those facts describe different measures and scopes, not a final performance or investment verdict.
#1 Best Overall

- 【Precision Cube Specimens】This test mold shapes consistent 70.7 x 70.7 x 70.7 mm mortar cubes for reliable laboratory results. The Concrete Compression Test Mold ensures every specimen meets the dimensions required for Compression Testing procedures and quality control protocols.
- 【Quality-Control Ready】Prepare uniform test specimens for cement testing and concrete workability checks in construction projects. This Concrete Compression Test Mold ensures every sample meets industry standards for reliable Cement Testing Equipment results.
- 【Built for Compression & Workability】This Reusable Cube Mold supports both concrete workability checks and concrete compression testing, so one tool covers multiple testing needs. The Square Sample Block Form delivers consistent mortar cubes for Building Inspectors analysis and structural evaluation.
- 【Choose Your Strength】Choose between standard-thick and extra-thick construction to match your testing routine's demands. The Square Sample Block Form is built for repeated use, with walls that maintain 70.7 x 70.7 x 70.7 mm dimensions through countless casting cycles, ensuring consistent Mortar Testing results over time.
- 【Easy Color Identification】The green color option helps you keep mortar and concrete testing organized on the job site. This Reusable Cube Mold makes sample identification quick and effortless, streamlining your Concrete Testing workflow and reducing mix-ups between different test batches.
How to build a fair financial comparison
1. Align period, reporting basis and scope
Begin with FY2025, the common completed financial year in the cited official disclosures. Use each company’s full audited group statements for the group comparison, and label any segment or company-only figure explicitly. Do not combine a full-year result for one issuer with another issuer’s interim period, or combine group totals and Nigeria-only totals without saying so.
Check the accounting line behind every number. An announcement may emphasize adjusted earnings or a particular profit subtotal; compare it with the corresponding audited statement line, not with a differently defined measure. Record units consistently, and note any exceptional items or changes in accounting presentation that affect year-on-year comparisons.
Rank #2

- MEETS GLOBAL TESTING STANDARDS – Engineered to comply with major international concrete testing standards, including ISO/DIS 8045 (International), EN 12504-2 (Europe), ASTM C805 (USA), DIN 1048-2 (Germany), NFP 18-417 (France), and JGJ/T 23-2001 (China). Ensures your on-site and laboratory measurements meet globally recognized requirements for professional structural inspection.
- PROFESSIONAL & VERSATILE – Designed for accurate concrete hardness and strength testing, the GOYOJO Concrete Rebound Hammer is ideal for engineers, construction inspectors, and quality control personnel. Perfect for measuring cement and concrete quality on-site or in lab settings.
- HIGH ACCURACY & RELIABLE – Equipped with precision sensors and durable construction, this concrete testing tool delivers consistent results from 10–60 MPa (1450–8700 psi). Ensure your measurements meet industry standards every time.
- EASY TO USE & PORTABLE – Compact, lightweight, and ready-to-use design allows immediate operation right out of the box on construction sites. Includes carrying case, digital depth gauge, grinding stone, and essential accessories for complete on-site testing.
- WIDE APPLICATION RANGE – Suitable for testing concrete, cement, and other masonry structures in building construction, infrastructure projects, and quality inspections. Provides reliable hardness readings for different surfaces and structures.
2. Compare growth with margins
Put revenue beside gross profit, operating profit, EBITDA and profit after tax wherever the audited accounts disclose comparable figures. Calculate each margin from aligned lines:
- Gross margin = gross profit ÷ revenue.
- Operating margin = operating profit ÷ revenue.
- EBITDA margin = EBITDA ÷ revenue, using a consistent EBITDA definition.
- Net margin = profit after tax ÷ revenue.
A higher revenue growth rate can coexist with weaker margins, while a one-year increase in PAT may reflect a low comparison base or items below operating profit. Check the audited statements and notes for explanations rather than treating a growth headline as a forecast.
Rank #3

- Essential Cement Testing: Specifically designed to determine the Initial Setting Time and Final Setting Time of hydraulic cement pastes, crucial for construction quality control.
- Standard Consistency Determination: Includes the necessary plunger and equipment to accurately find the Standard Consistency of cement samples, conforming to industry standards.
- High Precision Reading: Features a clear, calibrated scale in millimeters (MM) for precise measurement of needle penetration depth during testing.
- Complete Testing Kit: Supplied as a full set, including the main frame, a Brass Vicat Mold (or Mould), a removable Plunger, and both the Initial and Final Setting Needles, along with a Glass Plate.
- Durable & Robust Construction: Built with a sturdy Cast Iron Base and bright metallic moving parts to ensure stability and longevity in a demanding laboratory environment.
3. Test earnings against cash and financing
In each audited report, review cash generated from operating activities, capital expenditure, borrowings, cash balances, net debt, finance costs and foreign-currency exposures. Consider whether operating cash flow supports reported earnings and planned investment, and whether financing costs or currency movements materially affect the result. Use the same definitions and period for all three issuers; headline results alone do not establish which balance sheet is more flexible.
4. Separate capacity from actual output
Installed capacity measures potential production, not cement actually produced or sold. Compare capacity with reported production and sales volumes, checking that the figures cover the same facilities, period and product scope. Calculate or compare utilization only if a consistent definition and matching volume data are available for each company. Capacity alone cannot tell you which producer is using its assets more effectively.
Rank #4
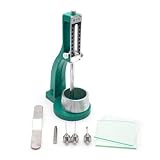
- Simple operation, stable performance
- Clear scale, accurate indication, not easy to deform
- Well-made, thick product, wear-resistant
- Regular size, firm, long service life
- Accurate measurement, accurate parameters, high-cost performance
5. Compare shareholder distributions with reinvestment
Read EPS and dividend per share together with cash generation, capital expenditure and financing needs. Check the proposed or paid dividend and its timing in the audited report and relevant results materials. A payout that looks high relative to earnings may not be sustainable if cash conversion is weak or the business needs substantial reinvestment; do not infer sustainability from dividend size alone.
How to compare the shares’ valuations
Choose one stated date and use NGX closing prices for all three shares on that date. Pair those prices with aligned per-share and balance-sheet data from the same reporting basis. Current prices and comparable multiples are not established by the cited FY2025 disclosures, so a valuation ranking should not be inferred from the announcement figures above.
Best Value

- Formulated for office and school use
- Use for temporary and permanent bonding of paper products
- Perfect for mounting, collage, scrapbooking and more
- Won’t shrink, wrinkle or curl paper
- 4 oz can w/ brush
- Price-to-earnings (P/E): share price ÷ comparable EPS. State whether EPS is reported, adjusted or trailing, and use the same basis across companies.
- Price-to-book: share price ÷ book value per share, using the same balance-sheet date and equity basis.
- Dividend yield: dividend per share ÷ share price. Specify the dividend period and whether the dividend is proposed, declared or paid.
- Enterprise-value multiples: calculate enterprise value consistently from market capitalization, debt and cash, then divide by a matching operating measure such as EBITDA.
Record the price date, statement date and calculation inputs beside the results. Valuation ratios are only comparable when their earnings, debt, cash and share-count bases are also comparable; a lower multiple is not automatically evidence of a better investment.
Account for geography and business mix
Dangote Cement’s group has operations in multiple African countries, so its consolidated revenue, profit, assets and capacity can reflect more than Nigerian cement operations. For a domestic-market comparison, use Nigerian segment disclosures when available and label the result accordingly. For a group-investor comparison, retain group totals for all issuers and explain any differences in geographic reach.
Also check the reports for plant locations, distribution footprint, exports, energy sourcing and any non-cement activities. These details can help explain differences in costs, exposure and investment requirements, but should not be used to make claims the accounts do not establish.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →A practical ranking framework
- Set the comparison: decide whether the question is about the groups or Nigerian operations, and use the same fiscal year.
- Verify inputs: take financial and operating figures from the full audited reports; reconcile announcement highlights to audited statement lines.
- Assess operating performance: compare revenue growth, margins, EPS, production and sales volumes, and explain material differences in scope or exceptional items.
- Assess financial resilience: compare operating cash flow, capital expenditure, borrowings, net debt, finance costs and foreign-currency exposures.
- Assess shareholder returns: compare dividends and payout with earnings, cash generation and reinvestment needs.
- Assess valuation: calculate comparable multiples from same-date share prices and aligned financial inputs.
- State the limits: distinguish reported facts from your calculations, and do not rank a category when comparable data are missing.
The FY2025 highlights establish a useful starting point, not a complete scorecard. The full audited accounts and same-date market prices are necessary to decide how the companies compare on cash conversion, balance-sheet risk, operating utilization and share valuation.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

