Compare credit card offers by matching each card’s APRs, fees, grace-period rules, and rewards to how you expect to use it. A low introductory APR may expire, fees can outweigh benefits, and rewards count only if you can earn and redeem them. Record the same details for every offer, then verify the current terms with the issuer before applying.
Start with how you will use the card
Your likely balance and payment habits determine which terms matter most. If you expect to carry a balance, focus on the ongoing APR for the transactions you make and the fees tied to borrowing. If you pay eligible purchases in full each month, compare the annual and transaction fees, the grace-period conditions, and rewards you can realistically use. This is a comparison framework, not a ranking or personalized financial recommendation.
As an Amazon Associate I earn from qualifying purchases.
Use the same spending assumptions for every offer. For example, compare rewards using the same expected monthly purchases and categories, and assess fees for the same kinds of transactions. Otherwise, you may end up comparing unlike scenarios rather than the offers themselves.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Compare every APR, not just the headline rate
A card can have different APRs for purchases, balance transfers, and cash advances. Promotional APRs are temporary: note the rate, when it ends, and the rate that applies afterward. For an ongoing APR shown as a range, record the range rather than assuming you will receive its lowest figure.
#1 Best Overall
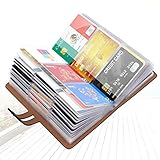
- 【Durable Materials】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【RFID Blocking】The credit card holder has an anti-shield lining, which can effectively block the electronic scanning instrument from illegally scanning the credit card in the card holder to protect the security of your RFID chip card.
- 【Easy to Find & Read】The internal translucent anti-magnetic PVC card page makes it easy for you to find and read card information and quickly find the card you need.
- 【Large capacity / Multipurpose】A total of 32 card slots, each card can hold 3 cards. A total of 96 card slots, fully meet your needs for card storage. You can hold your important customer business cards, credit cards, debit cards, ID cards, membership cards, VIP cards, invoices, receipts, etc. to prevent loss and damage.
- This is the best choice to keep your credit card and business card organized and easy to manage. Can be used to store credit cards or business cards that are important but not commonly used.
The Consumer Financial Protection Bureau describes APR as “the standard way to compare how much loans cost” in its credit card key terms guidance. APR is a useful comparison, but it does not capture every cost: transaction and account fees may also apply.
Purchase APR
Record any introductory purchase APR and its duration, followed by the ongoing rate or range. If you may carry a purchase balance after the promotional period, the rate that follows matters as much as the introductory offer.
Rank #2
- Large capacity business card storage: This book-style business card organizer can hold up to 240 business cards, two cards back-to-back in each pouch. It is very compact & professional. Enough capacity for your different cards: business cards, credit card, social security, gift cards, insurance cards, name cards, personal IDs, mini photos, and more
- Sturdy & Long-lasting card book: Name card holder is made from high-quality pu leather cover and PVC pocket sheets. Long-lasting and sturdy
- Easy to find & read: Card holder book transparent slots are good for reading and finding information on the business card
- Compact size business card folder: The slim profile and lightweight design make carrying a breeze – Carry it in your hand, pocket or handbag when on the go. Dimension: 7.7"x 4.5" x 0.7"
Balance-transfer APR
If you plan to transfer a balance, note the transfer APR, any promotional period and the rate that applies when it ends. Check the balance-transfer fee separately; a low or temporary APR does not make a transfer cost-free.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Cash-advance APR
Record the cash-advance APR and associated fee if you might use the card to obtain cash. Do not assume that the purchase APR applies to cash advances.
Rank #3

- Material: Genuine leather and PVC card slots.
- Size: 4.72"*3.15"*0.7" (12*8*1.8 CM)
- Large Capacity: The card holder has 26 cards slots. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift Idea: Great gift for mother, daughter, grandmother and so on.
Penalty terms
Include penalty APR terms if the issuer discloses them. Check the current agreement for the circumstances in which they may apply and any stated duration or conditions.
Check the grace period and payment conditions
A grace period can affect whether eligible purchases accrue interest when you pay on time, but it is not guaranteed for every card. The CFPB says card companies “are not required to give you a grace period” in its credit card contract definitions. Read the agreement to see which balances qualify and what payment behavior preserves the period. Paying the full covered balance by its due date is central to keeping it.
Rank #4

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
Record whether a grace period applies, which balances it covers, and the payment conditions. Do not assume that a purchase grace period also applies to balance transfers or cash advances; check the agreement’s terms for each transaction type.
Compare fees you are likely to pay
Separate recurring account costs from fees triggered by a transaction or circumstance. Compare the fees that fit your likely use rather than treating every fee as equally relevant.
Best Value
- Material: Genuine Cowhide Leather and PVC card slots.
- Size: 7.48"*3.54"*0.98" (19*9*2.5 CM)
- Large Capacity: The card holder has 60 cards slots and 2 ID Windows. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking Design: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift: Great gift for mother, daughter, grandmother and so on.
- Annual fee: Note the amount and how often it is charged. Weigh it against benefits you expect to use, not the card’s advertised maximum benefits.
- Balance-transfer fee: Include it when comparing cards for a transfer, even if the transfer APR is promotional.
- Cash-advance fee: Include it if cash advances are a possibility, alongside the separate cash-advance APR.
- Foreign-transaction fee: Check this if you travel or buy from merchants outside your country. It may apply to purchases in foreign currency or with a foreign merchant, so consider the issuer’s stated terms for both situations.
Estimate rewards using your real spending and redemption
Record the earn rates and categories, any relevant redemption limitations, and the value you expect to get from rewards based on your planned spending. The CFPB guidance cited here does not establish a universal value for a point or mile, so do not treat one as fixed across cards or redemption options.
Estimate rewards using the purchases you actually expect to make and a redemption method you are likely to use. Then compare that estimate with the annual fee and other costs. A benefit you will not use should not be counted as if it offsets a fee.
Build a side-by-side comparison
Use one row per offer and apply the same assumptions to each. Fill the table from each issuer’s current pricing disclosure and agreement; terms not shown in a disclosure should be checked with the issuer rather than guessed.
| Field | What to record | Why it matters |
|---|---|---|
| Purchase APR | Introductory rate and duration; ongoing rate or range | A temporary rate may be followed by a higher ongoing APR. |
| Other APRs | Balance-transfer and cash-advance APRs; disclosed penalty terms | Rates can differ by transaction type. |
| Annual fee | Amount and how often it is charged | Compare the cost with rewards and benefits you will actually use. |
| Transaction fees | Balance-transfer, cash-advance, and foreign-transaction fees | These can add to borrowing or purchase costs. |
| Grace period | Whether it applies, eligible balances, and payment conditions | Purchase interest can depend on the agreement’s rules and payment behavior. |
| Rewards | Earn rates and categories, redemption limits, and estimated value for your planned spending | Rewards matter only to the extent you can earn and use them. |
Verify the offer’s current terms before applying
The CFPB’s credit card agreement database can help you find and compare issuer-submitted agreements. The Bureau cautions that records can contain discrepancies, omissions, or errors and are not specific to an individual account. Treat the database as a research aid, not a guarantee that a particular live offer or your account will have those exact terms.
Before applying, check the issuer’s current pricing disclosure and agreement for the offer you are considering. Confirm the APRs, promotional end dates, fees, grace-period conditions, rewards rules, and eligibility terms there, since offers and terms can change.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

