Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →To protect your money, first confirm which bank legally holds your deposit and whether that bank is FDIC-insured; then check how much of your balance qualifies for coverage. Capital and liquidity can help you understand a bank’s resilience, but neither makes a bank failure-proof or predicts what will happen to a particular institution.
What FDIC insurance protects—and what it does not
FDIC insurance protects eligible deposits if an FDIC-insured bank fails, subject to the coverage rules. The standard limit is $250,000 per depositor, per insured bank, per ownership category, according to the FDIC’s Deposit Insurance FAQs. It is not a blanket guarantee of every financial product sold by a bank or offered through an app.
As an Amazon Associate I earn from qualifying purchases.
Eligible deposits generally include checking and savings accounts, money market deposit accounts, and certificates of deposit at an insured bank. Stocks, bonds, mutual funds, annuities, crypto assets, and other non-deposit investments are not covered by FDIC deposit insurance, even if a bank or app makes them available.
Accounts at one bank are combined within a category
The limit applies to the combined deposits a person holds in the same ownership category at the same insured bank—not to each account or branch separately. For example, if one person holds $200,000 in an individual checking account and $100,000 in an individual savings account at the same bank, those balances are combined for coverage purposes. The amount above the applicable limit is not insured under that category. Different branches of the same bank do not provide separate limits; deposits at different insured banks are insured separately.
#1 Best Overall
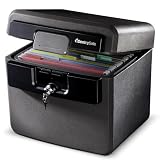
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
Accrued interest through the date of a bank’s failure counts toward the limit. If your balance is close to $250,000, leave room for interest rather than treating the full limit as available for principal.
Ownership categories can have separate limits
Some qualifying account ownership categories are insured separately, but each has its own eligibility and recordkeeping rules. Certain retirement accounts, for example, may qualify under a distinct category. Do not assume that changing an account label or adding an account creates another limit: the ownership must meet the FDIC’s rules. For a combination of accounts, use the FDIC’s Electronic Deposit Insurance Estimator (EDIE) to estimate coverage.
Verify the bank behind your account
A familiar brand, app, or account name does not necessarily identify the bank that holds the deposit. Find the legal name of the bank in your account agreement or deposit disclosures, then confirm that institution’s status with the FDIC’s BankFind tool. Use EDIE to estimate how your accounts at that bank combine under the coverage rules.
- Identify the legal bank. Check your account agreement or deposit disclosures for the institution that actually holds the funds. Do not rely on the app or product brand alone.
- Confirm FDIC status. Search for that bank in FDIC BankFind and verify that the institution is FDIC-insured.
- Group your balances. Add deposits held at that bank under the same ownership category, including principal and accrued interest.
- Estimate coverage. Enter your accounts and ownership details in FDIC EDIE. Review the result against the account records and category rules that apply to you.
Extra care with fintech and banking apps
A nonbank company is not itself an FDIC-insured bank. A fintech or app may arrange for customer funds to be deposited at an insured bank, but pass-through insurance depends on the funds actually being placed there and applicable requirements being met. An app’s statement that funds are “FDIC insured” is not a substitute for identifying the bank and understanding the arrangement.
Deposit insurance protects eligible deposits against the failure of the insured bank. It does not insure you against a nonbank company’s bankruptcy, fraud, service outage, or failure to meet its obligations. The FDIC also cautions that funds held by a nonbank may not be insured until they have been deposited at an insured bank.
Rank #2

- PROTECTS VALUABLES: 1.8-cubic-foot home safe for safeguarding important documents, jewelry, cash, devices, and other precious items
- RELIABLE SAFETY: This safe box features a programmable electronic keypad for secure, easy operation, along with a back-up key for emergency access; requires AA batteries (not included)
- DURABLE CONSTRUCTION: This mini safe is built with heavy-duty steel, including an 8-gauge steel door and 14-gauge steel body, as well as 2 live-door bolts and pry-resistant concealed hinges
- CONVENIENT ORGANIZATION: This safe for home includes an interior shelf to help keep your belongings neatly organized and easily accessible
- EASY INSTALLATION: Comes with pre-drilled mounting holes and hardware, making it simple to securely mount this mini safe box to the floor or wall
Capital and liquidity measure different risks
After confirming deposit coverage, capital and liquidity can help explain how a bank might withstand financial stress. They answer different questions, and neither measure should be read as a promise that a bank will remain open.
Capital: a cushion against losses
Capital is the difference between a firm’s assets and liabilities. It is a loss-absorbing cushion—not simply cash sitting in a vault. When a bank suffers losses, capital helps absorb their impact before those losses are borne by creditors or depositors. Regulatory capital measures account for different risks, and requirements vary by institution.
A ratio such as common equity tier 1 (CET1) is meaningful only with context: its reporting date, the measure being used, and whether it describes the insured bank or its parent holding company. Do not treat a regulatory classification threshold or a ratio from one institution as a universal “safe bank” cutoff.
For context, the Federal Reserve’s large-bank capital requirements page, updated June 24, 2026, lists a 4.5% minimum CET1 component and a stress capital buffer of at least 2.5%; a global systemically important bank (GSIB) surcharge applies where relevant and is at least 1.0%. These are components of a framework for covered large firms, not a consumer rule for choosing a bank.
Liquidity: meeting near-term demands
Liquidity is a bank’s ability to meet withdrawals and other near-term obligations. Cash, central bank reserves, and government bonds can be used or converted relatively quickly, but the timing and value available can depend on market conditions and the institution’s circumstances. A bank can face pressure if withdrawals accelerate or funding proves unstable, even if its longer-term assets have value.
Rank #3
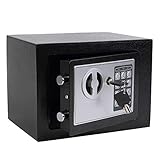
- STRONG & SECURE:Digital Locking- the Electronic Safety Lock Box Is Equipped with an Easy to Program Digital Keypad That Is Simple to Lock and Unlock by Entering Your Security Combination. Two Emergency Keys Are Included for Faster and More Immediate Access.
- SMART CAPACITY:0.2-cubic-feet, Exterior :9.05" x 6.69"x 6.69", Interior size: :6.29" x 8.9" x 5.12" (Pls pay full attention to the dimension for this MINI safe box),It gives you easy personal access to your valuables .
- STRONG & SECURE: The mini safe box is made of reinforced solid steel wall construction. Dual security steel door locking bolts & a corrosion & stain-resistant powder coat finish keeps the drop box safe.
- Durable powder coated finish, Magnetic lock for auto-locking;
- Easy to install: The home safe box has pre-drilled holes for wall or floor mounting, Includes mounting bolts.
As Federal Reserve Vice Chair for Supervision Michael S. Barr explained in a May 20, 2024 speech, “capital absorbs the impact of unanticipated losses; liquidity enables a bank to meet funding withdrawals and provides time to right itself from a bout of stress.” In other words, capital helps absorb losses; liquidity helps meet cash needs. A bank needs both.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Neither is a guarantee. The Federal Reserve also cautions that “no amount of liquidity can fully guarantee that a bank will survive a run.” Liquid assets do not erase losses, and capital does not ensure that cash will be available at the exact moment withdrawals occur.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How to compare bank disclosures responsibly
If you choose to assess a bank’s financial disclosures, compare like with like and note what each figure actually describes. A ratio is evidence about a particular measure at a particular time, not a consumer score or a forecast.
- Insurance and legal structure: Identify the bank holding the deposit, confirm its FDIC status, and determine your ownership category and combined balance there.
- Capital measure and date: Note whether a figure is CET1, leverage, or another measure, and when it was reported. Do not compare unlike ratios as if they were interchangeable.
- Entity being measured: Check whether a disclosure concerns the insured bank or its parent holding company; they are not automatically the same entity.
- Liquidity and funding: Look at what a disclosure says about liquid assets, funding, and withdrawals. Liquidity rules and public measures may apply only to certain larger firms, so the absence of a public liquidity coverage ratio (LCR) figure is not, by itself, evidence of weakness.
- Scope and freshness: Distinguish an institution-specific filing from an industry-wide statistic, and check the date before drawing conclusions.
These checks can clarify what a disclosure supports, but they do not produce a definitive ranking. A reported ratio may not capture every relevant risk, and conditions can change after the reporting date.
What recent industry figures can—and cannot—tell you
The Federal Reserve’s June 2026 Supervision and Regulation Report says that, at year-end 2025, over 99% of banks were well capitalized and aggregate CET1 risk-based capital ratios were about 13% for both large and small banks. Those are dated system-level figures, not the ratio for every bank, a minimum safety threshold, or a guarantee about a named institution.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteUse industry statistics as background, not as a substitute for checking a specific bank’s disclosures and your own deposit coverage. The FDIC’s status information and EDIE estimate address different questions: whether the bank is insured and how your deposits may be covered.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

