Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchNo-cost EMI is usually an interest-bearing loan whose interest is offset by a merchant or brand discount. Your bank still calculates interest, while the seller reduces the financed amount or gives an equivalent discount. The advertised phone price can therefore match the cash price, but processing fees, GST, a forfeited cash discount, and cancellation or pre-closure charges may increase what you pay. The only reliable measure is the total rupee amount shown in the final checkout and loan schedule.
How does no-cost EMI work?
When you select a no-cost EMI offer in India, the card issuer or lending bank generally creates a normal interest-bearing EMI. The interest is not magically removed from the loan calculation. Instead, the merchant, phone brand or platform funds an upfront discount designed to offset that interest.
As an Amazon Associate I earn from qualifying purchases.
The Reserve Bank of India describes the arrangement as follows: “Under no-cost EMIs, the interest charged by the bank is offered as an upfront discount to the customer by the BigTech platforms.” Depending on the promotion, that discount either reduces the financed principal immediately or appears as a deferred cashback. In both cases, the bank’s repayment schedule can still show an interest component.
A simple numerical example
Razorpay’s documentation uses a ₹15,000 phone financed for three months at 15% annual interest. The calculated interest is ₹367.33, and the discounted loan amount is ₹14,632.67. That illustration (from documentation crawled 4.3 years before 14 October 2026) shows the basic accounting: the seller’s discount is intended to cover the ₹367.33 interest, so the advertised phone price and scheduled principal-plus-interest can come out close to ₹15,000.
#1 Best Overall
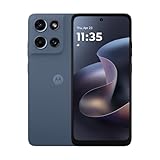
- Universal unlocked. Compatible with all major U.S. carriers, including Verizon, AT&T, T-Mobile and other prepaid carriers.
- Super-bright, super-smooth 6.7" display. See your screen clearly even outdoors in sunlight, and enjoy seamless views with a fast-refreshing 120Hz display.*
- AI-powered camera system. Take stunning photos in any light with the 50MP camera**, look your best with a 32MP selfie cam*****, and capture extreme close-ups.
- Superfast 5G performance. Unleash your entertainment at 5G speed*** with the MediaTek Dimensity 6300 chipset and up to 12GB of RAM with RAM Boost****.
- Long-lasting battery + TurboPower charging. Power through day after day with a 5200mAh battery, then get hours of power in just minutes.****
Your actual EMI can still differ from that headline because the bank may add GST on interest, a processing fee, or other charges. The checkout screen and the lender’s key-facts statement (KFS), when provided, take precedence over a banner that says “no cost.”
Is no-cost EMI really free?
It can be interest-neutral, but it is not automatically charge-free. “No-cost” normally describes only the treatment of the interest rate. It does not promise that every fee, tax or consequence of using credit is zero.
- Processing or convenience fee: The Reserve Bank of India explicitly says, “Processing fee is applicable even if the loan is a no-cost EMI loan.”
- GST: GST may be charged on the bank’s interest and on a one-time processing fee. Croma’s consumer FAQ also warns that GST applies to each EMI and to one-time EMI processing fees.
- Lost cash discount: A phone may have a lower price for an outright payment, bank transfer or other non-EMI method. Choosing EMI can make you give up that discount.
- Deferred benefit: Some offers provide the interest offset as cashback after a stated period rather than as an instant discount. You must carry the billed amount until the cashback arrives.
- Cancellation and pre-closure: Returning the phone or paying the loan early can trigger issuer-specific interest recalculation, foreclosure fees or loss of the merchant subsidy.
The RBI’s 2024 review of a sample of no-cost-EMI offers found processing fees ranging from 0.4% to 3.2% of the product price and 18% GST on the interest charged. These are observed figures from that sample, not a universal tariff for every bank, phone or promotion.
What is the processing fee and GST?
A processing fee is a one-time charge for arranging or converting the EMI. The fee may be a flat rupee amount or a percentage of the purchase. GST is then applied according to the tax treatment shown by the issuer. Ask whether the fee is collected immediately, added to the first instalment or billed separately.
Published issuer examples
| Issuer or offer | Published charge or rate | What the figure means |
|---|---|---|
| HDFC Bank Cardless EASYEMI | ₹299 plus GST processing fee; displayed IRR of 12%–20% for 1 April–30 June 2026 | Applies only where the customer, merchant and transaction are eligible. The displayed range is for that date window and product page. |
| Federal Bank merchant or instant credit-card EMI | 15.99% annual interest plus GST | Published merchant/instant EMI rate; EMI debits include principal, interest and applicable GST. |
| Federal Bank post-purchase conversion | 18% annual interest plus GST | A different rate for converting an already completed purchase. Its terms give a ₹399 plus GST MyEMI processing-fee example. |
| Apple India EMI facilitation | No processing or convenience fee charged by Apple for facilitating EMI or No Cost EMI | Taxes and levies can still apply, and the eligible card issuer may impose cancellation, refund, pre-closure or interest charges. |
These examples demonstrate why a generic “no-cost EMI fee” cannot be quoted. Rates and fees vary by issuer, merchant, phone model, tenure, card type and promotion. Read the exact disclosure attached to your transaction.
Rank #2

- YOUR CONTENT, SUPER SMOOTH: The ultra-clear 6.7" FHD+ Super AMOLED display of Galaxy A17 5G helps bring your content to life, whether you're scrolling through recipes or video chatting with loved ones.¹
- LIVE FAST. CHARGE FASTER: Focus more on the moment and less on your battery percentage with Galaxy A17 5G. Super Fast Charging powers up your battery so you can get back to life sooner.²
- MEMORIES MADE PICTURE PERFECT: Capture every angle in stunning clarity, from wide family photos to close-ups of friends, with the triple-lens camera on Galaxy A17 5G.
- NEED MORE STORAGE? WE HAVE YOU COVERED: With an improved 2TB of expandable storage, Galaxy A17 5G makes it easy to keep cherished photos, videos and important files readily accessible whenever you need them.³
- BUILT TO LAST: With an improved IP54 rating, Galaxy A17 5G is even more durable than before.⁴ It’s built to resist splashes and dust and comes with a stronger yet slimmer Gorilla Glass Victus front and Glass Fiber Reinforced Polymer back.
How much will I actually pay for a phone on EMI?
Calculate the complete outflow rather than multiplying the displayed monthly EMI by the number of months. Use this formula:
Total paid = down payment + all scheduled EMIs + processing/convenience fee + GST and other disclosed charges − any cashback or discount that you actually receive.
Recommended Free Tools
Then compare that total with the phone’s ordinary cash price after every non-EMI discount. A promotion that says “₹2,000 per month” is not enough information unless you know the tenure, first-payment amount, fees and taxes.
Build your own cost sheet
| Item to record | Where to find it | Why it changes the answer |
|---|---|---|
| Ordinary cash price | Product page and cash-payment checkout | Establishes the baseline before any EMI subsidy. |
| Non-EMI discount | Offer terms or payment-method banner | May disappear when you choose EMI. |
| Tenure and rate/IRR | EMI selector and lender disclosure | A longer term can change interest and fees even under a “no-cost” label. |
| Down payment | Final payment summary | Reduces the financed amount but is still part of your total outflow. |
| First and later EMIs | Repayment schedule | The first instalment can be larger when tax or a fee is collected upfront. |
| Processing or convenience fee | Fee line in checkout or KFS | Often remains payable even when interest is offset. |
| GST on interest and fees | Tax lines in the schedule or card statement | Can be charged separately from the advertised EMI. |
| Cashback timing | Offer terms | A deferred cashback is not a discount until it is credited and usable. |
For the ₹15,000, three-month illustration above, the seller’s ₹367.33 discount offsets the stated interest and produces a ₹14,632.67 discounted principal. If the lender adds GST on interest or a separate processing fee, those amounts sit on top of the otherwise interest-neutral calculation.
Rank #3

- Charger NOT Included, 6.7" Super AMOLED FHD+, 90Hz Refresh Rate, 385 ppi, 800 nits (HBM), 1080x2340px, 5000mAh Battery
- 128GB, 4GB RAM, microSDXC, Exynos 1330 (5nm), Octa-Core, Mali-G68 MP2 or Mali-G57 MC2 GPU
- Rear Camera: 50MP, f/1.8 (wide) + 5MP, f/2.2 (ultrawide) + 2MP, f/2.4 (macro), LED flash, panorama, HDR; Front Camera: 13MP, f/2.0, Android 14, up to 6 major Android upgrades, One UI 6.1
- 3G: HSDPA 850/900/1700(AWS)/1900/2100; 4G LTE: 1/2/3/4/5/7/12/13/14/20/25/26/28/29/30/38/39/40/41/48/66/71, 5G: 2/5/25/41/66/71/77/78 SA/NSA/Sub6/mmWave - Nano-SIM + eSIM
- US Model – Global Connectivity – Compatible with Most GSM Carriers like T-Mobile, AT&T, MetroPCS, etc. Will Also work with CDMA Carriers Such as Verizon, Straight Talk.
What should I check at checkout?
- Write down the ordinary cash price. Include coupons or instant discounts that apply only to non-EMI payments.
- Select the exact phone, issuer and tenure. An offer for one storage variant, card network or term may not apply to another.
- Open the detailed cost view. Record the financed principal, stated interest or IRR, down payment, first EMI and later EMIs.
- Find the processing or convenience fee. Confirm whether GST is included or added separately.
- Check GST treatment. Look for tax on interest, the one-time fee and each instalment rather than assuming the monthly figure is all-inclusive.
- Read the discount mechanism. Confirm whether the interest offset is instant or a cashback that arrives after a specified number of business days.
- Read return, cancellation, refund and pre-closure rules. Check what happens to the subsidy if the handset is returned or the loan is closed early.
- Add every rupee. Compare the total EMI outflow with the cash total before placing the order.
Which smartphones and buyers qualify?
No-cost EMI is an offer-level feature, not a guarantee attached to every smartphone. HDFC Bank’s Cardless EASYEMI page lists electronics and smartphone categories, including brands such as Apple, Samsung, Sony, LG, Bosch, Whirlpool and OnePlus, but eligibility depends on the customer and participating merchant. The list does not mean every model or every buyer qualifies.
ICICI states that no-cost EMI is available only on selected products and uses digital approval with flexible tenures. A different issuer may require a particular credit card, available limit, mobile number, or pre-approved loan relationship. A transaction can therefore fail even when the product page displays an EMI badge.
Free tools Windows power users keep installed
One-click scans. No signup required.
Before relying on the offer, verify all of the following in the live checkout:
- the exact handset model, storage variant and seller;
- the eligible card, account or financing product;
- available tenures and any down payment;
- the processing fee, GST and first-EMI amount;
- the date and form of any deferred cashback; and
- the issuer’s return, cancellation and foreclosure treatment.
How do cash and no-cost EMI compare?
| Comparison point | Paying upfront | No-cost EMI |
|---|---|---|
| Total price | Usually the cash price after available non-EMI discounts. | Cash price equivalent only if the interest offset covers the bank’s interest and no extra charges apply. |
| Upfront cash | Entire handset price immediately. | May require only a down payment and the first instalment. |
| Monthly obligation | None after purchase. | Fixed instalments for the selected tenure, plus possible tax or fee lines. |
| Credit usage | No EMI limit consumed. | Uses card limit or creates a loan that can affect available borrowing capacity. |
| Fees and GST | No EMI processing fee; ordinary purchase taxes still apply. | Processing fee and GST may apply even when interest is offset. |
| Returns or early payoff | Refund follows the seller’s return process. | Issuer cancellation, refund and pre-closure rules can add cost or delay. |
Choose EMI for cash-flow flexibility only after confirming that its complete total is acceptable. If the upfront price includes a substantial cash-only discount, that lost discount can outweigh the convenience of spreading payments.
Rank #4

- YOUR CONTENT, SUPER SMOOTH: The ultra-clear 6.7" FHD+ Super AMOLED display of Galaxy A17 5G helps bring your content to life, whether you're scrolling through recipes or video chatting with loved ones.¹
- LIVE FAST. CHARGE FASTER: Focus more on the moment and less on your battery percentage with Galaxy A17 5G. Super Fast Charging powers up your battery so you can get back to life sooner.²
- MEMORIES MADE PICTURE PERFECT: Capture every angle in stunning clarity, from wide family photos to close-ups of friends, with the triple-lens camera on Galaxy A17 5G.
- NEED MORE STORAGE? WE HAVE YOU COVERED: With an improved 2TB of expandable storage, Galaxy A17 5G makes it easy to keep cherished photos, videos and important files readily accessible whenever you need them.³
- BUILT TO LAST: With an improved IP54 rating, Galaxy A17 5G is even more durable than before.⁴ It’s built to resist splashes and dust and comes with a stronger yet slimmer Gorilla Glass Victus front and Glass Fiber Reinforced Polymer back.
What happens if I cancel, return or pre-close?
Do not assume a returned phone automatically cancels the loan. The merchant may process a refund while the issuer separately reverses or closes the EMI. During that period, instalments or interest can continue to appear.
Issuers can also treat the merchant’s interest subsidy differently when you pre-close. The promotional discount may be reversed, or a foreclosure charge may be added. Apple India specifically tells buyers to check their eligible card issuer for cancellation, refunds, pre-closure and interest charges. Obtain the issuer’s written terms before ordering if you may repay early.
If a refund is delayed
- Keep the order cancellation or return confirmation from the merchant.
- Ask the issuer whether the EMI is suspended, reversed or still active.
- Continue paying any amount that remains due to avoid late fees while the dispute is investigated.
- Confirm the final statement shows reversal of principal, interest and any applicable fee.
Common mistakes and how to avoid them
Looking only at the monthly number
A low EMI can simply reflect a longer tenure. Multiply every instalment, then add the down payment, fees and taxes.
Assuming “no-cost” means zero GST
GST on interest and processing fees can remain payable. Check the tax lines in the schedule rather than relying on the promotional headline.
Best Value

- Carrier: This phone is locked to Tracfone, which means this device can only be used on the Tracfone wireless network. Tracfone plan required, activating is easy, just 3 steps.
- DISPLAY: Immersive viewing on a 6.7-inch super-bright 120Hz display with powerful stereo speakers and Bass Boost for cinematic entertainment.
- CAMERA SYSTEM: Advanced 50MP Quad Pixel camera captures sharp, detailed photos and videos in any lighting condition
- PERFORMANCE: Lightning-fast 5G connectivity paired with a powerful processor and RAM Boost for smooth multitasking.
- BATTERY LIFE: Long-lasting 5000mAh battery with TurboPower charging technology delivers hours of power in minutes.
Missing deferred cashback conditions
Cashback may arrive after 120 business days, as Croma describes for some offers, and may require the account to remain active and in good standing. Treat it as uncertain until the terms and credit date are clear.
Ignoring the first instalment
One-time fees or taxes can make the first debit larger than later EMIs. Keep enough funds available for that initial amount.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Confusing post-purchase conversion with merchant EMI
Federal Bank publishes different rates for merchant/instant EMI (15.99% annually) and post-purchase conversion (18% annually), both plus GST. Select the product that matches the transaction you are making.
When is no-cost EMI sensible?
It can be reasonable when you need to preserve cash, the phone’s EMI price equals or nearly equals the best cash price, the processing fee is low, and you can comfortably meet every instalment. It is less attractive when a cash discount is forfeited, the fee is a high percentage of the phone price, cashback is delayed, or the return policy is uncertain.
Make the decision using the total payable amount and the risk of missing a payment, not the “zero-interest” wording. Offer terms, rates, fees, taxes, phone prices and eligibility change by issuer and promotion, so recheck the live checkout and lender terms immediately before purchase.
Bottom line: what does no-cost EMI really cost?
No-cost EMI usually means the merchant subsidises the bank’s calculated interest; it does not mean the credit transaction has no cost. Your real price is the cash price you give up, plus down payment, every EMI, processing fee, GST and any charge caused by cancellation or early closure, minus discounts or cashback that you actually receive. If that total is not shown clearly, ask the issuer or merchant for the complete repayment schedule before committing.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

