Recommended Free Tools
Choose the Google Pay Flex SBI Card if you value managing the card in Google Pay, want eligible RuPay credit payments at merchant QR codes, and can use Stars within the app. Compare its ₹499 joining and annual renewal fees plus applicable taxes with other UPI-linked RuPay cards before applying. The renewal fee is waived when your preceding-year spend reaches ₹1 lakh. Another RuPay card may suit you better if its fees, rewards, app support, or broader card benefits fit your needs more closely.
What does “Flex SBI” add to a UPI-linked RuPay card?
Google Pay Flex is offered with SBI Card and Axis Bank, on RuPay and Visa networks. The network matters: Google’s instructions for paying UPI QR codes apply to Flex cards on RuPay. A Visa Flex card can be used for ordinary online or in-store card payments where Visa is accepted, but that does not make it a Visa-on-UPI card. Check Google Pay’s current Flex card help for the operational details.

As an Amazon Associate I earn from qualifying purchases.
The SBI version combines card management in Google Pay with RuPay merchant QR payments and Stars rewards. Google announced the product as built on RuPay, but that product positioning is not a guarantee that every merchant QR code or transaction will accept it. The issuer assesses applications and handles credit-specific matters such as approval and interest rates.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Can you use a RuPay credit card for UPI payments?
Yes, if the card issuer and UPI app support linking that card, and the payment is an eligible merchant transaction. NPCI says customers can link an eligible RuPay credit card account to a UPI ID in an enabled app, scan a merchant’s UPI QR code, and authenticate with a UPI PIN. This is credit payment to a merchant—not a way to send borrowed money to another person. See NPCI’s RuPay credit card on UPI guidance for supported issuers, apps, and restrictions.
#1 Best Overall

- SECURE YOUR WALLET FROM e-PICKPOCKETING: Prevent potential identity and financial theft through your contactless cards. Don’t become a victim e-theft in our growing contactless society. This is the simplest and most effective prevention solution! Block all RFID and NFC signal to secure your details and have peace of mind.
- JAMMING CHIP: An antenna and jamming chip makes up the main components of the card. The antenna will sense incoming radio waves and draw power for the chip to create a jamming signal. Lifetime usage as the card does not require battery.
- BROAD WORKING DISTANCE: A large working distance of 2.4” provides complete protection for your whole wallet. Cards 1.2” either side of the card will be fully secure from e-pickpocketing.
- ULTRA-THIN & COMPACT: At the size of a standard credit card and at only 0.03” thick, the card will fit into any wallet, purse or card case. Keep your wallet compact with no added bulk from this card.
- TEST THE CARD: Test the card is working at your local supermarket. At the self-service checkout machines, combine the card and a contactless card on the payment reader. Payment with the contactless card will be blocked and an error message should occur on the reader.
- Do not assume every RuPay card, UPI app, QR code, or merchant is eligible. Check the current NPCI list and the issuer’s terms for the exact card.
- Person-to-person transfers and cash withdrawals are among the prohibited or restricted categories. NPCI also lists other restricted transaction types, including card-to-card payments, certain investment and lending transactions, and merchant or ATM cash withdrawal. Issuers or RBI rules may impose further restrictions.
- A UPI PIN authenticates the payment; it does not turn the credit card into a general-purpose UPI balance.
Compare the costs and reward usability
| Factor | Google Pay Flex SBI | Other UPI-linked RuPay cards |
|---|---|---|
| Joining and renewal fees | ₹499 plus applicable taxes for joining and renewal. Renewal is waived after at least ₹1 lakh in preceding-year annual spend, according to SBI Card’s MITC and Google’s Flex help. | Depends on issuer and card; compare each issuer’s current fee and waiver terms. |
| UPI QR use | RuPay version supports eligible UPI merchant QR payments through a supported app; the Visa version is not described as supporting UPI QR payments. | Requires an eligible RuPay card, supported issuer and UPI app, and an eligible merchant transaction. |
| Rewards | Stars have a stated ₹1 value each when applied to eligible payment cashback or voucher discounts in Google Pay. They cannot be cashed out or redeemed outside the app. | Reward rates, exclusions, reward form, and redemption options vary by card; check the issuer’s terms. |
| Beyond UPI | Can be used for ordinary online or in-store card payments where the relevant network is accepted. | Depends on the card network and issuer terms. |
For Flex rewards, the ₹1-per-Star figure is an in-app redemption value, not cash value. Google’s Flex rewards help lists exclusions from earning Stars, including insurance, cash withdrawals, rent, wallet loads, education, government services, jewellery, and transactions converted to EMI. It also describes issuer-specific differences in welcome rewards and boosters, so check the offer that applies to the SBI card rather than assuming another Flex card’s offer applies.
When Flex SBI is the better fit—and when to compare alternatives
Consider Flex SBI if
- You want card controls and rewards available inside Google Pay.
- You make eligible merchant QR payments and specifically want to use a RuPay credit card for them.
- You can realistically use Stars toward eligible in-app payments or vouchers.
- Your expected annual spend makes the ₹1 lakh renewal-fee waiver attainable, or the fee is worthwhile to you even without the waiver.
Compare other UPI-linked RuPay cards if
- You want lower fees or a different renewal-waiver threshold.
- You prefer rewards that are easier for you to redeem or that are not confined to Google Pay.
- You need benefits or issuer service features that matter more than Flex’s app integration.
- Your preferred UPI app or card issuer does not currently support the specific combination you need.
There is no single best choice across all RuPay cards: fees, rewards, exclusions, support, and benefits vary, and current terms must be compared issuer by issuer. NPCI’s issuer and app lists are operational lists that can change, so verify them before applying or switching.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How to assess EMI and total cost
SBI’s Pay in EMI feature is available through Google Pay to select eligible primary Flex SBI cardholders and charges interest. SBI’s published terms effective 11 September 2026 state interest rates from 10% to 26% per annum depending on bureau-score band. Those terms describe a promotional processing-fee waiver for 24- and 36-month bookings from that date, with fees for other tenures; offers and fees can change. Review SBI’s EMI terms and the actual offer in the app, then compare total interest and fees with paying in full before treating EMI as a benefit.
Quick Recap
Rank #4

- SECURE YOUR WALLET FROM e-PICKPOCKETING: Prevent potential identity and financial theft through your contactless cards. Don’t become a victim e-theft in our growing contactless society. This is the simplest and most effective prevention solution! Block all RFID and NFC signal to secure your details and have peace of mind.
- JAMMING CHIP: An antenna and jamming chip makes up the main components of the card. The antenna will sense incoming radio waves and draw power for the chip to create a jamming signal. Lifetime usage as the card does not require battery.
- BROAD WORKING DISTANCE: A large working distance of 2.4” provides complete protection for your whole wallet. Cards 1.2” either side of the card will be fully secure from e-pickpocketing.
- ULTRA-THIN & COMPACT: At the size of a standard credit card and at only 0.03” thick, the card will fit into any wallet, purse or card case. Keep your wallet compact with no added bulk from this card.
- TEST THE CARD: Test the card is working at your local supermarket. At the self-service checkout machines, combine the blocking card and a contactless card on the payment reader. Payment with the contactless card will be blocked and an error message should occur on the reader.
Rank #3
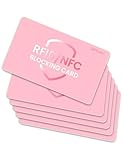
- Complete Protection: Blocks RFID signals within 2.4 inches (1.2 inches per side) to safeguard credit cards, IDs, passports, and driver's licenses from wireless scanning. Just insert into your wallet for instant security.
- Active Signal Jamming Technology: Built-in microchip and antenna detect and disrupt unauthorized scans with real-time interference signals, ensuring your financial and identity data stays secure.
- Sleek & Portable: Ultra-thin 0.03 inches design (credit card-sized) fits seamlessly into wallets, pockets, or cardholders. Effortless protection wherever you go.
- Easy to Use: No battery required, lifetime usage; Won't degauss other cards; Doesn't affect your phone signal, WIFI or Bluetooth
- Tested & Verified: Confirm its effectiveness: Place the RFID blocking card over your contactless card at a self-checkout—if the reader fails, your data is protected.
What to check before applying
- Confirm the network and UPI eligibility. For QR payments, choose a RuPay version and verify that the issuer, specific card, and intended UPI app are supported.
- Calculate the recurring cost. Include the joining and renewal fee, applicable taxes, and whether your likely preceding-year spend reaches any waiver threshold.
- Value rewards by how you will actually redeem them. Check earning exclusions and redemption limits; do not treat app-bound Stars as cash.
- Review non-UPI use and credit terms. Check ordinary card acceptance, issuer controls, billing and support, and any interest or EMI charges relevant to you.
- Confirm approval requirements with the issuer. Google says applications are assessed by the issuing bank; approval is not guaranteed by having a compatible app or network.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

