Homeowners insurance often covers sudden, accidental water damage from inside the home, such as a burst pipe or appliance leak. It generally excludes flood damage from water that rises or flows over normally dry land, which usually requires separate flood insurance. The cause and path of the water—and the wording, exclusions and endorsements in your policy—determine how a specific loss is handled.
How homeowners and flood insurance differ
| Coverage | Usually applies to | Important limits |
|---|---|---|
| Homeowners insurance | Sudden, accidental water damage from sources such as plumbing, household appliances or a roof leak. Some policy forms also cover freezing, rupture or sudden overflow of plumbing, heating, air-conditioning or fire-sprinkler systems. | These are common examples, not a guarantee. The policy’s exclusions, maintenance requirements and facts of the loss matter. NAIC homeowners guidance and its consumer policy guide describe these coverages. |
| Flood insurance | Direct physical damage from a flood, including water that inundates normally dry land from an overflowing body of water or storm surge. | Standard homeowners coverage usually excludes flood damage. FloodSmart describes a flood as excess water on normally dry land affecting at least two acres or two properties. FloodSmart’s flood definition gives more detail. |
Which kinds of water damage may be covered?
Burst pipes and appliance leaks
A sudden, accidental discharge from a pipe or household appliance is often covered by homeowners insurance, subject to the contract. Frozen-pipe damage may also be covered when the homeowner took reasonable steps to maintain heat or protect the pipes; neglect can affect coverage. See the NAIC guidance on burst pipes. Do not assume the same result for long-term seepage, repeated leakage, mold or wear and tear: the policy and circumstances control.
As an Amazon Associate I earn from qualifying purchases.
Roof leaks
Water damage from a roof leak is typically covered under homeowners insurance, according to the NAIC. A leak associated with a flood or another excluded cause may be treated differently, so the source and route of the water matter.
Floodwater entering from outside
Water that accumulates or flows over normally dry land is generally a flood loss, not ordinary homeowners water damage. Standard homeowners policies usually exclude it; separate flood insurance is typically needed. The applicable flood policy’s definition and exclusions still determine whether a particular loss qualifies.
#1 Best Overall

- Breakthrough 1804 ft Connectivity: Engineered with advanced Sub-1G long-range wireless tech, our leak detector maintains robust signals over unprecedented distances—reaching up to 1804 feet even through 5 dense walls. Secure every critical space in expansive properties, from deep basements to detached garages and distant outbuildings.
- Multiple Reminder Methods: Our water leak sensor supports multiple remote alarm. It can instantly send SMS, APP, and Email notifications to your phone (no matter how many times the SMS is used, it's free). Also, the water leak sensor flashes red and sounds a 105 dB alarm. Perfect for the basement, kitchen, or vacation home!
- Feature-Rich App: Receive instant push notifications. Use the “Find Device” feature to quickly trigger audible beeps to retrieve misplaced sensors. Add multiple email addresses through the APP, and your family and friends can also receive reminders when there is a water leak at home.
- Industry Leading IP67 Waterproof: Its IP67 waterproof rating ensures durability against spills, humidity, and accidental submersion.It can be used multiple times after wiping dry.
- Four-level volume adjustment: Customize your own alarm to fit your life! Use the app to adjust the volume in 4 levels, with a maximum alarm volume of 105 decibels. Whether it's day or night, whether it's in the bedroom or the basement, you can find the right volume.
Sewer backups and sump-pump overflows
These losses are not automatically treated as floods. A homeowners policy may offer sewer or drain backup coverage through a separate endorsement. FloodSmart says a sewer backup caused directly by flooding may be covered by an NFIP policy, while a backup caused by a clogged pipe is not covered under its example. Ask the insurer to establish the cause and apply the relevant policy terms. See FloodSmart policy terms and the NAIC homeowners overview.
What NFIP flood insurance covers—and its limits
For a typical residential National Flood Insurance Program (NFIP) policy, FloodSmart lists maximum coverage of $250,000 for building property and $100,000 for contents. Building and contents coverage are typically purchased separately and have separate deductibles. These are maximums, not a promise that every loss or item is covered.
Rank #2
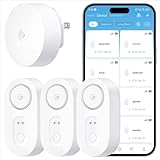
- Breakthrough 1804 ft Connectivity: Engineered with advanced Sub-1G long-range wireless tech, our leak detector maintains robust signals over unprecedented distances—reaching up to 1804 feet even through 5 dense walls. Secure every critical space in expansive properties, from deep basements to detached garages and distant outbuildings.
- Multiple Reminder Methods: Our water leak sensor supports multiple remote alarm. It can instantly send SMS, APP, and Email notifications to your phone (no matter how many times the SMS is used, it's free). Also, the water leak sensor flashes red and sounds a 105 dB alarm. Perfect for the basement, kitchen, or vacation home!
- Feature-Rich App: Receive instant push notifications. Use the “Find Device” feature to quickly trigger audible beeps to retrieve misplaced sensors. Add multiple email addresses through the APP, and your family and friends can also receive reminders when there is a water leak at home.
- Industry Leading IP67 Waterproof: Its IP67 waterproof rating ensures durability against spills, humidity, and accidental submersion.It can be used multiple times after wiping dry.
- Four-level volume adjustment: Customize your own alarm to fit your life! Use the app to adjust the volume in 4 levels, with a maximum alarm volume of 105 decibels. Whether it's day or night, whether it's in the bedroom or the basement, you can find the right volume.
- NFIP coverage is for direct physical flood damage; some property and expenses are excluded or limited.
- FloodSmart lists vehicles, outdoor property, temporary housing and additional living expenses among exclusions or limitations.
- Basement coverage has specific exceptions for certain installed or powered items. Check the policy rather than assuming all basement property is covered—or all of it is excluded.
See FloodSmart’s policy terms and claims guidance for policy details.
Buying flood coverage: timing and policy choice
Eligibility and waiting periods
NFIP availability depends on whether the community participates in the program. Flood insurance is generally required for a home in a Special Flood Hazard Area when its mortgage is government-backed, and lenders may set additional requirements. FloodSmart lists a normal NFIP waiting period of 30 days, with exceptions that include certain mortgage transactions, renewal changes, newly designated high-risk areas and qualifying wildfire-related floods. Check timing with the insurer; private flood policies can have different terms. See FloodSmart eligibility information and NAIC flood insurance guidance.
Rank #3

- Leaking & Dripping: 2 water sensitive probes on the front for monitoring pipe/drain drip and 4 rear probes for detection water leak & floor moisture/flood. Both are work simultaneously, whatever leak sensors contact water, it will warning you in time.
- Loud & Mute: Our water leak alarm have loud and Mute Mode. It can emit 100 dB audio and loud enough to be heard even if leaks happened in basement. Press the button to mute the Water Detector Alarm when you arrived the flooded place.
- Tiny & Wireless: No Wire, Installation Required. Mini size allows you to put water leak alarms on any places, where the water leak may be happened. Such as house, underground, Pool, under Washing Machine, or unexpected disasters that may burst pipes, etc..
- Ultra Lifespan: Due to built-in 2*AAA Battery and energy-efficient circuit, our Floor Water Sensor Moisture Alarm has over 2 years standby time with Low Battery Alert, which reminds you to replace battery in time via flashing red light.
- Real IP66 Waterproof: The Water Alarm Detector is made of ABS & Stainless Steel, helps water sensor keep sensibility during the long time used without rust. Mounting Battery from the front to protect battery from getting wet and safer.
Compare NFIP and private policies
Private flood policies may offer higher limits or broader coverage than NFIP, but there is no universal best choice. Ask an insurer or licensed agent to compare the actual policies on these points:
- Building and contents limits, and whether coverage is purchased separately
- Deductibles and how they apply
- Covered property, exclusions and valuation basis
- Waiting period and eligibility
- Basement coverage and any additional living expense coverage
- Premium and renewal terms
What to do after water damage
- Put safety first. Do not enter a damaged building until it is safe.
- Report the loss promptly. Contact your insurer or agent and ask how to proceed.
- Identify the source and path of the water. Note whether it came from plumbing or an appliance, entered through the roof, backed up from a sewer or drain, or flowed in from outside.
- Review your coverage. Check the declarations page for homeowners, flood, building, contents and sewer-backup coverage, along with applicable limits and deductibles.
- Document the damage. Take photos or video, make an inventory, and keep receipts and records. The NFIP claims checklist recommends documenting flood damage and discussing coverage, limits and deductibles with your provider.
Why flood coverage can matter outside obvious flood zones
FloodSmart reports that 99% of U.S. counties experienced a flood event in the previous 20 years; the page does not state a publication year for that figure. The same source reports an average NFIP claim payment of $68,000 from 2016–2021. That is a historical average for the stated period, not a current estimate. See FloodSmart’s flood insurance basics.
Quick Recap
Best Value

- Complete plug-and-play kit: hub plus Leak Sensor 1 units for whole-home coverage at toilets, sinks, water heaters, laundry, dishwashers, and sump areas.
- Long-range LoRa: reliable coverage where Wi-Fi struggles (up to 2,034 feet open air); get app, email, and SMS/text alerts and name sensors by location.
- Works even without internet: with YoLink Control-D2D, sensors can directly trigger YoLink sirens or shutoff valves for local protection during outages.
- Silent design: Leak Sensor 1 has no built-in siren; add SpeakerHub or a YoLink siren for audible or spoken alerts if desired.
- Scalable IoT platform: one hub supports 300+ YoLink devices; part of a whole smart home/building ecosystem; hub options include standard Hub, SpeakerHub, and Cellular Hub.
Rank #4

- Complete plug-and-play kit: hub plus Leak Sensor 4 units, each with a built-in 105 dB audible alarm for instant on-site alerts.
- Long-range LoRa: reliable coverage where Wi-Fi struggles (up to 2,034 ft. open-air); get app, email, and SMS/text alerts and name sensors by location.
- Works even without internet: with YoLink Control-D2D, sensors can directly trigger YoLink sirens or shutoff valves for local protection during outages.
- Low-maintenance power: each sensor uses 2 AAA batteries with up to 5 years typical battery life; easy replacement.
- Scalable IoT platform: one hub supports 300+ YoLink devices; part of a whole smart home/building ecosystem; hub options include standard Hub, SpeakerHub, and Cellular Hub.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →
