Commercial satellite services for defence and security could generate more than $22.6 billion by 2035, according to Novaspace’s September 2026 forecast—about $23 billion when rounded. That is a projection for purchased satellite services, not a tally of military budgets, satellite hardware, contract backlogs or the value of government-owned spacecraft.
The same forecast puts global defence satcom demand above 7.5 Tbps in 2035. Non-geostationary-orbit (NGSO) constellations and multi-orbit networks provide most of the growth, while geostationary-orbit (GEO) capacity remains important even as GEO service revenue declines.


As an Amazon Associate I earn from qualifying purchases.
What the $23 billion defence satcom figure actually measures
Novaspace’s Satellite Communications for Defense and Security, 2nd Edition, published in September 2026, forecasts more than $22.6 billion in commercial satellite-service revenue for defence and security applications by 2035. The headline “$23 billion” is therefore a rounded presentation of a more precise forecast.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware match“Commercial satellite-service revenue” is the key qualifier. It describes money paid for connectivity and related satellite capacity by defence and security users. It does not equal total military communications expenditure. The figure also does not include every satellite manufactured for a government, the full cost of launch and ground infrastructure, personnel, classified systems, or the notional value of dedicated military constellations that are not sold as commercial services.
#1 Best Overall
Novaspace separately forecasts global defence satcom demand above 7.5 terabits per second (Tbps) in 2035. Revenue and capacity are different measurements: a market can require more throughput without spending the same proportion on services, because pricing, orbit mix, contract structures and mission requirements vary.
| Forecast item | Novaspace figure | How to interpret it |
|---|---|---|
| Commercial defence and security satellite-service revenue | More than $22.6 billion by 2035 | A forecast of service revenue, not all military satcom spending |
| Global defence satcom demand | More than 7.5 Tbps by 2035 | A forecast of required capacity, not a dollar value |
| NGSO service revenue | $21.3 billion by 2035 | Revenue forecast for non-geostationary-orbit services, supported by a 34% CAGR |
| GEO service revenue | $2.3 billion in 2025, falling to $1.3 billion in 2035 | A projected decline in GEO service revenue despite rising capacity use |
Because these are forecasts, none of the values should be described as realised 2035 revenue, an approved government appropriation or a confirmed order book. They represent Novaspace’s view of how the market could develop from the information available in 2026.
Why military and security users are buying more satellite capacity
The growth case is built around a change in network architecture rather than simply an increase in the number of terminals. Novaspace identifies next-generation NGSO constellations and multi-orbit connectivity as the principal drivers. These systems can combine satellites in different orbital regimes, terrestrial links and gateways so that a user is not dependent on one path through space.
Free tools Windows power users keep installed
One-click scans. No signup required.
Resilience in contested environments
Defence networks have to keep operating when links are jammed, obstructed, attacked or unavailable for operational reasons. A distributed architecture can provide alternative satellites, beams, routes and orbits. It does not make a network invulnerable, but it can reduce the consequences of losing one asset or one frequency path.
Santiago Perez, senior manager at Novaspace, described the trend this way: “The growing adoption of distributed satcom architectures is rapidly enhancing military satcom resilience against disruption, jamming, and kinetic attacks.” The statement is about architectural direction, not a guarantee that any particular constellation will withstand a specific attack.
Rank #2

- Reliable Intersystem Bonding Performance – Mengfan GB5-1 intersystem zinc grounding bridge ensures stable connection between power and communication grounding systems, supporting multiple hookups for telephone, CATV, or satellite dish systems.
- Durable Zinc Construction & Protective Cover – The intersystem bonding bridge features a robust zinc body with a white paintable plastic cover, offering corrosion resistance and easy maintenance for long-term use.
- Wide Compatibility with Conductors – This GB5-1 zinc grounding bridge fits #14 to #4 copper/aluminum solid/stranded wires for intersystem bonding, and #6 to #2 wires for grounding electrode connection.
- Easy Installation – 4-terminal design enables fast, tool-friendly mounting on grounding conductors, with easy access for inspections.
- Versatile Application Scenarios – Mengfan intersystem grounding bridge is ideal for residential, commercial, and industrial electrical projects, ensuring safe and code-compliant grounding solutions.
Mobile and time-sensitive operations
Military users increasingly need connectivity while forces, ships, aircraft and remote platforms are moving. The strategic case for NGSO and multi-orbit services includes lower-latency links for real-time data, tactical command networks and remote uncrewed platforms. Those applications can be sensitive to delay, intermittent coverage and the time needed to establish a connection.
Connectivity demand also rises when more sensors and platforms share data. Video, telemetry, targeting information, logistics updates and command traffic all compete for capacity. The 7.5-Tbps projection reflects this aggregate requirement across defence and security missions; it is not the bandwidth of one network or one country.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Commercial networks alongside military systems
SatNews’ description of the Novaspace report says it covers both commercial operator networks and dedicated military satellite systems. This matters because the market is not a simple replacement of government spacecraft with commercial constellations. Defence organisations can use commercial capacity for scale and flexibility, dedicated systems for assured access and control, or both through a multi-orbit, multi-provider design.
Perez also said: “What we’re witnessing is not simply a shift in satellite capacity demand. This is a fundamental evolution in military communications.” In practical terms, that evolution is the move from a single-orbit or single-provider assumption toward networks designed to select among several paths.
NGSO versus GEO: what changes and what does not
NGSO includes low-Earth-orbit and other non-geostationary constellations whose satellites move relative to a ground location. GEO satellites orbit above the equator at a speed matching Earth’s rotation, appearing fixed in the sky. The two approaches have different operating characteristics and are increasingly used together.
| Comparison point | NGSO services | GEO services |
|---|---|---|
| Revenue outlook in the Novaspace forecast | $21.3 billion in service revenue by 2035, with a 34% CAGR | Service revenue projected to fall from $2.3 billion in 2025 to $1.3 billion in 2035 |
| Capacity demand | Principal source of market growth in the forecast | Capacity demand is still expected to triple by 2035 |
| Latency | Generally lower latency because many NGSO satellites operate closer to Earth | Longer signal path than low-orbit systems, which can affect interactive applications |
| Mobility and coverage | Constellations can provide frequent satellite handovers and broad moving coverage | A fixed orbital position simplifies pointing and can provide continuous coverage over a defined region |
| Resilience | Many satellites and routes can distribute risk, although gateways, terminals and spectrum remain potential failure points | Fewer spacecraft can mean simpler architecture, while a GEO link can remain a valuable independent path |
| Likely role | High-growth layer for mobile, data-intensive and lower-latency missions | Persistent wide-area capacity and an important component of hybrid architectures |
Why NGSO is the growth engine
The forecast assigns $21.3 billion in 2035 service revenue to NGSO and associates that outlook with a 34% compound annual growth rate (CAGR). CAGR is a rate used to describe the constant annual pace that would connect a starting value with an ending value; actual yearly growth can be uneven. The figure should therefore not be read as a promise that revenue will rise by exactly 34% every year.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →NGSO’s appeal is the combination of lower latency, mobility and the ability to add satellites and beams as demand expands. For a force operating across multiple theatres, a constellation can support users who cannot rely on a fixed terrestrial network. The trade-offs include frequent handovers, dependence on gateways and terminals, spectrum coordination and the need to manage a larger constellation.
Why GEO remains relevant even with falling revenue
Novaspace projects GEO service revenue to decline from $2.3 billion in 2025 to $1.3 billion in 2035, yet expects GEO capacity demand to triple. Those statements are not contradictory. Capacity demand measures how much throughput users seek; revenue depends on the price of that capacity, the mix of services and how much demand migrates to other orbital systems.
GEO satellites can still offer persistent coverage from a stable orbital position, mature ground equipment and useful wide-area beams. A defence network may retain GEO capacity for missions that value continuity, broadcast reach or an independent path, even when newer NGSO services capture a larger share of incremental spending.
Why a hybrid architecture is the practical outcome
A multi-orbit design can assign traffic to the path that best fits the mission. An NGSO link may carry interactive data or a moving platform’s connection, while GEO provides a persistent overlay, backup route or regional broadcast. The correct mix depends on terminal capability, coverage, threat conditions, security requirements and the availability of gateways.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
The forecast’s combination of rising total demand, strong NGSO growth and continuing GEO capacity use points to coexistence rather than an immediate one-for-one replacement. Procurement teams should evaluate how terminals, network management and encryption work across orbits instead of treating each constellation as a standalone purchase.
Commercial operator networks and dedicated military systems
Commercial and dedicated systems solve different parts of the assurance problem. A commercial operator can offer capacity at scale, geographic reach and a service model that lets a government add or reduce usage. A dedicated military system can be designed around government-controlled coverage, protected payloads, sovereign operations or mission-specific requirements.
| Attribute | Commercial operator network | Dedicated military system |
|---|---|---|
| Primary arrangement | Government buys satellite capacity or managed connectivity as a service | Government owns or controls the spacecraft, payload, network or contracted dedicated capacity |
| Scaling | Can draw on a larger constellation and commercial investment cycle | Expansion follows public procurement, programme schedules and available launch capacity |
| Control | Service terms, operator policies and shared infrastructure shape access | Greater control over design, tasking and assurance, subject to programme constraints |
| Resilience approach | Leverages distributed commercial assets and multiple providers where available | Can build protected, sovereign or mission-specific features into the system |
| Accounting in the $22.6 billion forecast | Directly represented by the commercial service-revenue measure | Not equivalent to the value of government-owned systems; the public forecast does not state a total valuation for them |
In reality, a defence network can combine both categories. A government might use dedicated links for the most sensitive traffic and commercial services for routine data, surge capacity or operations in areas where government-owned coverage is limited. Interoperability, identity management and traffic prioritisation become as important as the satellite orbit itself.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Which countries dominate projected demand?
The United States is forecast to account for more than 50% of global defence satcom demand and 48% of revenues through 2035. China is projected to represent roughly 30% of both demand and revenues. These shares make the two countries the dominant markets in Novaspace’s outlook.
The wording matters: “more than 50%” is not an exact point estimate, while “roughly 30%” signals an approximation. The figures also refer to Novaspace’s global forecast through 2035, not to every national military communications budget or to a ranking of satellite ownership.
Best Value
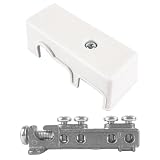
- Connect Communication Systems to Electrical Ground: For cable TV, satellite dishes, phone lines, and internet service, this GB5-1 bonding bridge provides a central termination point. The grounding bridge ties external utility lines to your building's existing grounding electrode system.
- Four Terminals for Multiple Connections: Stop daisy-chaining ground wires. This ground bridge electrical has four separate terminal lugs, each accepting a copper bonding conductor. The white grounding bridge lets you connect phone, cable, satellite, and data lines all in one UL-listed block.
- Die-Cast Zinc with Protective Plastic Cover: Weather exposure can corrode exposed terminals. This GB5-1 grounding bridge comes with a white plastic cover that snaps over the terminals. The zinc grounding bridge stays clean and dry behind the cover while the die-cast body provides strength.
- UL Listed for Residential and Commercial Use: Local codes often require a listed grounding bridge for service entrances. This white intersystem bonding bridge is UL listed, so it meets code requirements for new construction and service upgrades. The 4-1/2-inch grounding block fits standard installations.
- Surface Mounts with Built-In Holes: No special bracket needed. This GB5-1 grounding bridge mounts directly to any flat surface using the pre-drilled mounting holes. Install near your electrical panel or meter base, strip your bonding wires, insert into the four terminals, and tighten the set screws.
Combining the two shares would leave the remainder distributed among other countries and regions, but the public figures do not provide a complete country-by-country breakdown. It would therefore be misleading to assign precise percentages to the rest of the world or to infer that a smaller share means no demand; the overall market is forecast to exceed 7.5 Tbps.
How to use the forecast when assessing the market
Separate three different questions
- How much service revenue? Use the more-than-$22.6-billion commercial revenue forecast.
- How much connectivity? Use the above-7.5-Tbps demand forecast.
- How much government spending? The cited public release does not provide a consolidated figure for procurement, operations, hardware and personnel.
These measures should not be substituted for one another. A procurement plan can increase throughput through a lower-priced service, shift traffic from GEO to NGSO, or invest in government-owned infrastructure that does not appear as commercial service revenue.
Understand what the CAGR does and does not tell you
The 34% CAGR is attached to the NGSO service-revenue outlook ending at $21.3 billion in 2035. It communicates the implied pace over the forecast period, not a guaranteed annual result. Actual adoption could be affected by launch schedules, terminal availability, spectrum decisions, security accreditation, budgets, export controls, competition and operational performance.
Keep the uncertainty visible
Novaspace’s public release does not provide a full model appendix or scenario sensitivity in the available material. Readers should treat the numbers as a base forecast rather than as a range with published high and low cases. The safest use is directional: NGSO and multi-orbit services are expected to expand rapidly, GEO remains strategically useful, and defence organisations will need more resilient capacity.
What the 2035 outlook means for network planners
- Plan for multiple orbits. Specify how traffic moves between NGSO and GEO and what happens when one path is degraded.
- Measure capacity and service cost separately. A Tbps requirement is not a budget, and a revenue forecast is not a throughput guarantee.
- Design for mobility. Terminals, handovers, beam changes and network management must support moving users and remote platforms.
- Build resilience beyond the spacecraft. Assess gateways, terrestrial backhaul, power, spectrum, encryption and operations centres as potential points of disruption.
- Clarify ownership and assurance. Decide which missions require dedicated government control and which can use commercial capacity under service-level agreements.
- Track regional concentration. The United States and China account for most projected demand and revenue, so supplier availability, policy and geopolitical conditions in those markets can influence the wider ecosystem.
The central conclusion is not that GEO disappears or that every military user moves to a commercial constellation. It is that defence communications are becoming distributed, multi-orbit and more dependent on resilient service layers. Novaspace’s forecast quantifies that shift with a commercial-revenue outlook above $22.6 billion, NGSO service revenue of $21.3 billion and global demand above 7.5 Tbps by 2035.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

