What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Yes, but the payment is usually a platform reward rather than native interest from USDC. Coinbase says eligible customers can earn rewards for holding USDC and states, “Coinbase does not use or lend your USDC without your instruction.” That is the clearest example of a strict no-lending arrangement. Rates, eligibility, balances, and countries vary, so check the live terms on your account before moving funds.
What “earning interest without lending” really means
USDC itself does not have a built-in interest rate that accrues merely because tokens sit in a wallet. A holder can receive money only if another party funds a payment. In a no-lending product, that payer is typically a custodian or exchange operating a rewards program, not a borrower using your coins.
As an Amazon Associate I earn from qualifying purchases.
This distinction matters because the word yield covers very different arrangements. A holding reward may be calculated from your USDC balance, while a lending product pays you for supplying assets to borrowers. Both can display an annual percentage rate, but they carry different legal, operational, and financial risks.
Recommended Free Tools
- Holding reward: the platform pays under its own program and says your USDC is not lent without your instruction.
- Lending yield: your USDC is lent directly or through an intermediary to borrowers.
- DeFi liquidity yield: your tokens are supplied to a protocol, liquidity pool, or other smart-contract strategy.
- Issuer economics: the stablecoin issuer earns income on reserve assets; that income is not automatically passed to holders.
Calling every one of these “USDC interest” hides the decision you need to make: whether your assets are being deployed to someone else and what claim you have if that deployment fails.
#1 Best Overall

- Effortlessly build your crypto portfolio via the all in one Ledger Wallet app: buy, sell, send, receive, swap, stake and more across popular blockchains. 15,000+ coins & tokens in a single dashboard. Keep a close eye on the market. Compare service providers. Track performance. Get timely alerts. Build your portfolio with confidence.
- Enjoy Bluetooth connectivity, iOS access, and hours of battery use with this mobile-first, secure backup signer. Freedom you can depend on.
- Genuine Check: confirm your signer is authentic during setup with the Ledger Wallet app.
- Protect your signer: keep it in mint condition at all times with a bespoke Pod or Case to avoid scratches and everyday wear and tear.
Available routes compared
| Route | Are your USDC lent or deployed? | Who controls custody and withdrawals? | Rate behavior | Main additional exposures | Fit for a strict no-lending requirement |
|---|---|---|---|---|---|
| Custodial USDC holding rewards | The program may state that the platform does not use or lend the balance without your instruction. | The platform controls the account and applies its terms. | Variable; account, balance, geography, and eligibility can affect the amount. A universal APY is not established. | Platform access, program changes, regulatory changes, and stablecoin risks. | Best fit when the current terms expressly prohibit use or lending without your instruction. |
| USDC held in a normal wallet | No lending occurs simply from holding the token. | You control the wallet keys, or a custodian does if it is hosted. | No native holding rate. | Wallet security, custody, network fees, and USDC market or redemption risks. | Yes, but there is no automatic income. |
| Crypto lending account | Yes. Assets are lent to borrowers or routed through a lending intermediary. | Usually the provider controls the account and lending process. | Quoted APY can change with demand and provider policy. | Borrower default, rehypothecation, liquidity limits, provider insolvency, and regulatory risk. | No. |
| DeFi lending or liquidity pool | Yes. Smart contracts supply funds, make markets, or issue loans. | You may control the wallet, but the contract controls deposited assets while supplied. | Often variable and dependent on utilization, fees, incentives, and token prices. | Smart-contract bugs, oracle failures, liquidation, impermanent loss, bridge risk, and liquidity constraints. | No. |
| Issuer reserve income | Your coins are not individually lent; the issuer manages reserve assets. | The issuer and your custodian control redemption access. | Reserve income belongs to the issuer unless a separate program passes some through. | Issuer, reserve, banking, regulatory, and redemption risks. | It does not create a holder yield stream by itself. |
How custodial holding rewards work
Coinbase’s stated no-lending model
Coinbase documents a USDC Rewards program for eligible customers and says, “Coinbase does not use or lend your USDC without your instruction.” If the terms on your account contain that same limitation, the arrangement is a platform-funded reward for holding a balance rather than a loan you make to a borrower.
That statement does not make the reward equivalent to bank deposit interest. The platform can set eligibility rules, calculate rewards, change rates, impose balance limits, suspend the program, or end it under its terms. Availability can differ by country, account status, and regulatory requirements. The quoted rate in an advertisement is not a universal rate for every customer.
Is it staking?
USDC is a dollar-linked token, not a proof-of-stake network token that must be delegated to validators. A custodial USDC reward should therefore not be described as native USDC staking. If a service uses the word “staking” for a USDC balance, read the product agreement to identify whether it is actually lending, liquidity provision, or a separate promotional payment.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsWhat to verify before depositing
- Open the current product terms from your logged-in account. Confirm the exact country, account type, minimum or maximum balance, payment schedule, and rate formula that apply to you.
- Search for asset-use language. Look for “lend,” “borrow,” “rehypothecate,” “collateral,” “liquidity,” “investment,” or permission to use assets. A promise not to lend without your instruction is materially different from a broad right to use your balance.
- Identify the payer. Determine whether the reward is paid by the exchange, an affiliated entity, a protocol, or a borrower. The payer determines much of your counterparty risk.
- Check withdrawal mechanics. Note whether rewards and principal can be withdrawn immediately, whether there are queues or minimums, and whether network or conversion fees apply.
- Save the terms and statements. Rates and rules can change. Keep dated copies of the agreement, reward history, transaction records, and any tax forms.
Does USDC pay interest just by sitting in a wallet?
No. Holding USDC in a self-custodied or ordinary hosted wallet does not create an automatic yield. You receive value only if you opt into a separate service that pays it.
Why reserve backing is not holder interest
Circle describes USDC as designed to maintain a stable value relative to the U.S. dollar, redeemable 1:1, and backed by highly liquid cash and cash-equivalent assets. Income generated by those reserve assets is issuer economics. Holders should not assume that reserve income is distributed to them.
Circle reported support for 38 blockchain networks as of September 16, 2026. The network on which you hold USDC affects transfer compatibility, fees, and operational choices, but network support does not create a native interest rate.
What 1:1 redemption does and does not promise
A 1:1 redemption design is intended to support a dollar value; it is not a guarantee that every venue will provide instant liquidity in every circumstance. Temporary trading discounts, network outages, banking interruptions, custody failures, or a loss of confidence can still affect access and market price.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Rank #2
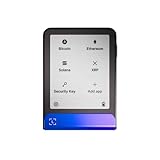
- Simply & securely take control of your digital assets and identity with the all-in-one Ledger Wallet crypto app and Ledger Flex touchscreen signer.
- Digital asset control at your fingertips: manage 15,000+ crypto across multiple chains. Earn rewards. Top up & share with ease. Explore DeFi with confidence. Collect and showcase NFTs. Make informed choices with clarity.
- Connect effortlessly with Ledger Wallet: pair your secure Ledger signer with the all in one Ledger Wallet crypto app to manage thousands of digital assets across multiple devices and accounts with Ledger Sync from a single, secure dashboard.
- Cutting-edge design: monitor the market, compare rates, and Clear Sign transactions on the secure, high resolution, 2.8'' E Ink touchscreen.
- This is what security feels like: Ledger touchscreen signers all come with a private, offline, PIN-protected backup, Ledger Recovery Key, to never lose access to your assets.
Why lending and DeFi yields are different
Lending products pay because your assets are put to work. A borrower may use the USDC for trading, working capital, or collateral. In DeFi, a smart contract may match lenders and borrowers or combine deposits in a liquidity pool. You may retain a wallet key, but the deposited tokens are still committed to a strategy controlled by code and its governing rules.
- Borrower and credit risk: a borrower may default or collateral may fall faster than it can be liquidated.
- Protocol and smart-contract risk: coding errors, exploits, oracle failures, or governance actions can impair withdrawals.
- Liquidity risk: a quoted balance may not be immediately redeemable when many users exit.
- Counterparty and rehypothecation risk: an intermediary may reuse assets or have obligations that rank ahead of yours.
- Price and pool risk: incentives can be paid in volatile tokens, and liquidity pools can produce losses relative to simply holding USDC.
These products can be appropriate for a user who knowingly accepts deployment risk, but they do not satisfy a strict “without lending” requirement.
What the GENIUS Act changes—and what it does not
The GENIUS Act was enacted on July 18, 2025. Its payment-stablecoin provisions state: “No permitted payment stablecoin issuer or foreign payment stablecoin issuer shall pay the holder of any payment stablecoin any form of interest or yield … solely in connection with the holding, use, or retention of such payment stablecoin.”
The wording addresses payments by a permitted payment-stablecoin issuer that are solely tied to holding, using, or retaining the stablecoin. It does not automatically answer whether every reward paid by an exchange, broker, wallet provider, or other third party has the same legal characterization. Product structure, licensing, disclosures, and future implementing rules matter.
Do not infer from the statute that a particular reward is approved, insured, or permanently available. Read the provider’s current terms and treat legal classification as product-specific.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.U.S. tax treatment of USDC rewards
Income when the reward arrives
Coinbase’s stablecoin tax guidance says rewards, staking rewards, yield, card rewards, referral bonuses, and similar stablecoin payments are typically income when received, measured in fiat currency. In a simple illustration, receiving 25 USDC when each token is worth $1.00 would generally produce $25 of income at receipt if the product is classified that way.
You can owe tax even if you leave the reward in USDC and never convert it to dollars. The exact result can depend on the product contract, how and when you gain control of the tokens, your taxpayer status, jurisdiction, and later IRS guidance.
Rank #3

- Simply & securely take control of your digital assets and identity with the all-in-one Ledger Wallet crypto app and Ledger Flex touchscreen signer.
- Digital asset control at your fingertips: manage 15,000+ crypto across multiple chains. Earn rewards. Top up & share with ease. Explore DeFi with confidence. Collect and showcase NFTs. Make informed choices with clarity.
- Connect effortlessly with Ledger Wallet: pair your secure Ledger signer with the all in one Ledger Wallet crypto app to manage thousands of digital assets across multiple devices and accounts with Ledger Sync from a single, secure dashboard.
- Cutting-edge design: monitor the market, compare rates, and Clear Sign transactions on the secure, high resolution, 2.8'' E Ink touchscreen.
- This is what security feels like: Ledger touchscreen signers all come with a private, offline, PIN-protected backup, Ledger Recovery Key, to never lose access to your assets.
Later sales or exchanges are separate events
Once reward income is included, that included dollar value generally becomes the starting basis for the received tokens. A later sale, exchange, or other disposal can create a separate gain or loss based on proceeds and basis. For example, if the 25 USDC in the illustration is later disposed of for $1.03 each, the subsequent calculation would consider the $0.03-per-token change after receipt.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallMerely holding USDC is not a sale. Moving it between wallets that you control is generally not a disposal either, although fees, transfers to another taxpayer, or a change in beneficial ownership can alter the analysis. Keep records that show receipt time, dollar value, wallet or account, basis, fees, and every later disposition.
Practical recordkeeping checklist
- Download monthly account statements and reward histories.
- Record the date, time, quantity, and dollar value of every reward.
- Track fees separately; they may affect basis or proceeds.
- Reconcile on-chain transfers with custodian records so a wallet move is not mistaken for a sale.
- Ask a qualified tax professional how federal, state, and non-U.S. rules apply to your facts.
Risk checklist for “safe” no-lending yield
Eliminating lending risk does not eliminate risk. Evaluate the arrangement across these separate categories:
- Platform and custody: the provider can restrict access, change terms, suffer an outage, or become insolvent. You may not control the private keys.
- Program: rates, caps, eligibility, payment timing, and geographic availability can change or disappear.
- Regulatory: stablecoin legislation and implementing rules can force a product to change or stop.
- Stablecoin: reserve and redemption design reduce some structural concerns but do not guarantee uninterrupted liquidity or prevent a temporary depeg.
- Tax: income may arise before conversion to cash, followed by separate gain or loss reporting on disposal.
- Operational: sending USDC on an unsupported network, losing wallet credentials, or overlooking a withdrawal hold can cause permanent loss.
There is no basis for assuming FDIC or SIPC insurance applies to a particular USDC rewards balance unless the exact product documentation and an authoritative insurance source say so.
A decision framework
Choose a holding reward only if all of these are true
- You accept platform custody and can tolerate a changed or canceled program.
- The current terms clearly state that your USDC is not lent or otherwise deployed without your instruction.
- You have confirmed withdrawal timing, geographic eligibility, and tax reporting expectations.
- You understand that the reward is not guaranteed bank interest and that USDC itself has no native holding yield.
Do not use a no-lending label as a substitute for due diligence
A marketing phrase can omit important details. Ask what happens to the principal if the provider fails, whether the provider may pledge or commingle assets, which entity owes the reward, and whether the program is available in your jurisdiction. If the answers are unclear, treat the product as an unverified counterparty exposure rather than as cash with interest.
Free tools Windows power users keep installed
One-click scans. No signup required.
Bottom line
You can earn a USDC-denominated reward without authorizing a loan, with Coinbase’s documented holding-rewards program providing the clearest cited example. That payment is a platform benefit, not proof that USDC natively earns interest. Lending, liquidity pools, and DeFi strategies are different because they deploy your assets and add borrower, smart-contract, and liquidity risks. In the United States, rewards are generally income when received and later disposals can create additional gain or loss, so verify the live terms, preserve records, and obtain tax advice for your situation.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

