Short answer: American Express, Visa and Mastercard all describe protections against unauthorized transactions, but none of the three brands guarantees identical coverage or service for every card. American Express combines the card network and (for its own cards) the issuing relationship, while Visa and Mastercard publish network policies that are delivered through the bank or other financial institution that issued your card. Your cardmember agreement, transaction type and reporting speed ultimately control the result.
American Express emphasizes account monitoring, alerts and direct reporting tools. Visa’s Zero Liability policy covers most of its consumer credit and debit cards, with stated exclusions and a policy statement about provisional replacement funds. Mastercard’s U.S. Zero Liability terms require reasonable care and prompt reporting, exclude commercial and unregistered prepaid cards, and display an effective date of October 17, 2014. These are policy descriptions, not a cross-brand ranking of claim outcomes.
As an Amazon Associate I earn from qualifying purchases.
What the three fraud-protection promises actually cover
“Unauthorized transaction” means a purchase, withdrawal or other transaction you did not approve. It is different from a purchase you made but later disliked, a billing error, a canceled order, a missing delivery or a dispute over a merchant’s service. Zero-liability language is aimed at unauthorized use; it does not automatically decide ordinary merchant disputes in your favor.
| Brand | Who handles the response? | Core policy description | Important eligibility or condition | Where to report |
|---|---|---|---|---|
| American Express | American Express can be both the network and the issuer for its cards. | Its U.S. Security Center describes monitoring, fraud alerts, online-shopping authentication, account reporting and emergency replacement. | Services and benefits can vary by account; the company does not promise that every suspicious transaction will be caught. | Use the phone number on the card, the logged-in account or account chat. The Security Center also lists 1-800-528-4800, but contact details can change. |
| Visa | The issuing bank or other financial institution normally investigates and credits the account under Visa’s network policy. | Visa says its Zero Liability Policy is a guarantee that eligible cardholders will not be held responsible for unauthorized charges. | Most Visa credit and debit cards are covered, but certain commercial and anonymous prepaid transactions and transactions not processed by Visa are excluded. Prompt reporting and reasonable care are required. | Notify the issuing financial institution immediately. |
| Mastercard | The issuing financial institution administers the claim under Mastercard’s terms. | Mastercard’s U.S. Zero Liability promise says eligible cardholders are not responsible for unauthorized transactions. | Cardholders must use reasonable care to protect the card and promptly report loss or theft. Commercial cards and unregistered prepaid cards, such as gift cards, are excluded in the cited terms. | Contact the issuing financial institution immediately. |
The policies use similar consumer-friendly language, but the documents are not identical. A network logo alone does not establish that every card, payment channel or issuer procedure has the same protection.
#1 Best Overall

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
American Express: integrated tools and direct account reporting
Monitoring and alerts
American Express’s U.S. Security Center says its systems monitor account activity and can notify cardmembers when something unusual is detected. It also describes fraud alerts, SafeKey for online shopping, suspected-fraud reporting through the phone or a logged-in account, and emergency card replacement. Those are descriptions of available services, not a guarantee that every fraudulent transaction will be identified before it posts or that every card has identical features.
How to report a suspicious American Express charge
- Sign in to the American Express website or app and review the transaction details, or call the number printed on the card.
- If you do not recognize the charge, use the account’s fraud-reporting path or account chat. The Security Center lists 1-800-528-4800 on the page accessed for this article; verify the current contact option on the live Security Center before calling.
- Follow instructions for replacing the card if the account number may be exposed. Ask whether additional cards or digital-wallet tokens also need to be replaced.
- Save the transaction date, amount, merchant descriptor, case number and any messages from American Express.
American Express also has a separate dispute workflow. Its U.S. dispute FAQ tells cardmembers to contact the merchant before opening a dispute when appropriate. To start an online dispute, select the transaction in the account and choose “Dispute this Charge.” That process covers a range of billing and merchant problems; selecting it does not mean the transaction was unauthorized or guarantee a favorable decision.
Visa: broad stated coverage, issuer-led claims and provisional funds
Who is covered
Visa’s U.S. Zero Liability page says the policy applies to most Visa credit and debit cards. It specifically excludes certain commercial cards, anonymous prepaid cards and transactions that were not processed by Visa. “Most” is important: confirm the product’s account agreement and ask the issuer whether your card and transaction qualify.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Visa’s reporting and replacement-funds language
Visa directs cardholders to take reasonable care protecting the card and to notify the issuing financial institution immediately. Visa’s page says the transaction must be posted before replacement funds may be issued. It also says the issuer is required under the policy to replace funds taken from the account because of an unauthorized credit or debit transaction within five business days of notification.
Visa describes those funds as provisional. The page says they may be withheld, delayed, limited or rescinded when circumstances include gross negligence or fraud, delayed reporting, investigation and verification, or the account’s standing and history. Treat the five-business-day statement as Visa’s policy language, not as a universal legal deadline for every account or as a promise that an investigation will be finished in five days.
Rank #2
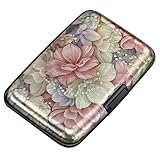
- This Credit Card Holder is made of aluminum shells, ABS plastic frame and clasp closure, RFID-blocking will protect your card data from RFID scanners and readers.
- The Size is 4.33 x 2.95 x 0.73 inches, Slim and small exterior design, are fit in your front pocket,suitable for travel and business carrying.
- Latches Safely and Securely when not in use. Rounded corner wouldn't damage on your clothes. With 7 accordion Slots, Capacity for up to more than 9 credit cards or more than 21 business cards.
- There are various patterns to choose from on the aluminum shell, including flowers, animals, and landscapes, to match your versatile style.
- This is an ideal gift that can express your thoughtfulness and kindness. Suitable for any day you want to express love on, such as Valentine's Day, birthdays, Mother's Day, etc.
What Visa’s promise says—and does not say
Visa’s official wording states: “Visa Zero Liability Policy is our guarantee that you won’t be held responsible for unauthorized charges made with your account or account information.” The same page’s exclusions and issuer-reporting directions qualify that sentence. It does not eliminate the need to protect the card, report promptly or cooperate with the issuer’s investigation.
Mastercard: reasonable-care and prompt-reporting conditions
Terms and exclusions
Mastercard’s U.S. Zero Liability terms say the issuing financial institution will not hold a cardholder responsible for “unauthorized transactions” when the cardholder used reasonable care to protect the card from loss or theft and promptly reported loss or theft to the financial institution. The cited U.S. page excludes commercial cards and unregistered prepaid cards, including gift cards, and tells cardholders to contact the financial institution immediately.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →The page identifies the terms as effective October 17, 2014. Because that date is old, check the current Mastercard terms and your issuer’s agreement before relying on the wording. Mastercard’s page states: “If you believe there has been unauthorized use of your account and you meet the conditions above, rest easy knowing that you have the protection of Mastercard’s Zero Liability promise.” The conditions above—not the slogan alone—determine whether the promise applies.
What “reasonable care” means in practice
The cited terms do not turn reasonable care into a single checklist for every situation. In practical terms, protect the physical card and account credentials, do not share passwords or one-time codes, secure a lost card quickly, and report suspected loss or theft without waiting for a statement cycle. Your issuer may ask when you first noticed the problem and what steps you took.
Network protection versus the issuer that actually fixes the account
American Express can combine network and issuer functions on its own cards, so a cardmember often starts and finishes the report inside one American Express support system. Visa and Mastercard are primarily network brands in this comparison. The bank or other financial institution that issued the card normally verifies the transaction, opens the claim, supplies any credit and decides account-specific questions.
Rank #3

- QUICK CARDS ACCESS: This minimalist wallet for men features a smooth pop-up mechanism. Just press the side button, and the cards slide out in a stepped layout for easy access.
- SLIM BODY WITH LARGE CAPACITY: Despite being slim at only 0.6 inches thick, this card wallet for men can hold 10-12 cards. The aluminum chamber holds 6-8 and the leather flap holds 4 (2 ID windows included). The money clip on the back holds 10+ bills.
- DOUBLE ID WINDOWS: KAFELLON designed the first pop up wallet on the market with 2 ID windows, based on real user needs. It's perfect for holding your ID and driver's license for quick access and quick view.
- RFID BLOCKING: This rfid blocking wallet features a built-in RFID-blocking layer that blocks unauthorized scans, protecting your finances and personal information.
- PERFECT GIFT IDEA: This money clip wallet combines a modern design with great practicality and comes with an elegant gift box. It's the perfect gift for men on Christmas, Valentine’s Day, Father’s Day, and other special occasions.
That difference explains why two cards carrying the same network logo can have different phone menus, app options, investigation letters, temporary-credit timing or documentation requests. The network policy sets a framework; the issuer’s agreement and procedures govern the account-level experience. If your card is issued by a bank, use the number on that card or the bank’s official app rather than searching for a generic network contact.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteUnauthorized use, merchant disputes and billing errors are separate tracks
Use the fraud route when you did not authorize the transaction
Examples include a purchase made after your card was stolen, an online order placed by someone using your account number, or a cash withdrawal you did not make. Report these promptly as unauthorized use. Do not wait for the merchant to respond if the account may still be compromised.
Use a merchant-dispute route when you recognize the transaction
If the descriptor belongs to a merchant you used but the amount is wrong, the item never arrived, a subscription was canceled but billed, or the service was defective, explain that problem to the issuer as a merchant or billing dispute. American Express recommends contacting the merchant before opening its dispute process. Zero-liability wording does not guarantee a favorable result for these disagreements because the cardholder did authorize the original transaction.
Check the descriptor before declaring fraud
Payment descriptors can show a parent company, payment processor, hotel group or abbreviated trading name instead of the storefront name. Check receipts, subscriptions, household-authorized users and digital-wallet history first. If the charge remains unexplained, report it as suspected unauthorized use and let the issuer investigate; do not delay a report merely because the descriptor is confusing.
What to do when you see a charge you did not make
- Secure the account immediately. Use the issuer’s official app or the number on the card. If the card is missing, ask the issuer to lock or replace it and to disable exposed digital-wallet tokens.
- Capture the facts. Record whether the transaction is pending or posted, the amount, date, merchant descriptor, currency and any authorized-user information. Keep screenshots and confirmation numbers.
- Report to the correct party. For Visa or Mastercard, start with the issuing bank or financial institution, as both network policies direct. For an American Express card, use the account’s fraud-reporting tools, chat or phone support.
- Ask about temporary credit and deadlines. Confirm whether the issuer requires a posted transaction, what provisional-credit rules apply, and when additional documents are due. Visa’s policy page specifically discusses posted transactions and provisional replacement funds.
- Change exposed credentials. Update the card-account password and any reused password, and tell the issuer if a phishing message or one-time code was involved. Never give a caller a verification code unless you initiated the call through an official channel.
- Monitor after the report. Review new authorizations, statements and replacement-card activity. A fraudulent merchant may retry a declined number, and an account takeover can affect more than one transaction.
- Keep the case record. Store the claim number, dates, names or department identifiers, promised follow-up date and copies of documents until the issuer closes the matter.
Lost or stolen card: act before a charge appears
All three sets of guidance place importance on prompt reporting. Lock the card in the issuer’s app if that feature is available, then contact the issuer to report loss or theft and request a replacement. Review pending authorizations as well as posted charges. A card that is physically recovered may still need replacement if its number was copied.
Free tools Windows power users keep installed
One-click scans. No signup required.
Rank #4
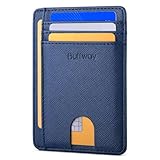
- STYLISHLY SMALL, SLIM & DISCREET: Measuring just 3 1/8" x 4 7/16", our RFID front pocket wallet is designed to be super thin and exceptionally slim. Its modern, minimalist profile fits perfectly in your pocket, purse, or travel pack without adding bulk.
- SURPRISINGLY SPACIOUS: Though slim, it features 8 slots to easily organize your essentials. Comfortably holds your driver's license, credit cards, debit cards, and membership cards, keeping everything you need right at your fingertips.
- ADVANCED RFID BLOCKING: Our slim wallets for men and women are outfitted with advanced RFID SECURE Technology. They block electronic signals to keep your identity protected while you travel, shop, or explore, safeguarding you from digital theft.
- DURABLE & STYLISH FAUX LEATHER: Crafted from premium synthetic leather, this minimalist wallet sleeve combines a luxurious look and feel with everyday functionality. Its durable construction is designed to withstand the rigors of daily use, travel, and shopping.
- THE PERFECT UNISEX GIFT: With its sleek design and practical security features, this wallet is a popular choice for both men and women. It arrives ready for gifting, making it an ideal present for the frequent traveler, minimalist, or anyone in your life!
Mastercard’s cited terms expressly condition Zero Liability on reasonable care and prompt reporting of loss or theft. Visa likewise tells cardholders to protect the card and notify the issuer immediately. American Express describes emergency replacement through its Security Center. None of these statements means you should wait to see whether a transaction appears.
Online authentication is not the same as liability protection
Visa Secure is an authentication layer used for online transactions at participating merchants. Visa says the issuer may request an additional verification step when needed, that the service is not used for every transaction, and that not all fraud can be prevented. A successful authentication does not replace the need to report an unauthorized charge, and the absence of an authentication prompt does not by itself prove that a transaction was fraudulent.
American Express describes SafeKey as an online-shopping security feature. As with Visa Secure, treat it as a prevention or verification measure, not as a promise that every transaction will be blocked or that an eventual dispute will automatically be decided for you.
Which policy is better for a particular cardholder?
| Your priority | What the published policies indicate | What you still need to verify |
|---|---|---|
| One company for network and issuer support | An American Express-issued card can provide direct American Express account reporting, alerts and replacement support. | Whether your specific card includes each listed service and how its agreement handles disputed transactions. |
| Broad stated coverage on a mainstream credit or debit card | Visa says Zero Liability covers most Visa credit and debit cards. | Commercial, anonymous-prepaid and non-Visa-processed exclusions; issuer-specific procedures and account standing. |
| Protection on a Mastercard consumer card | Mastercard’s terms promise no responsibility for eligible unauthorized transactions when reasonable care and prompt reporting conditions are met. | Current terms, the issuer’s agreement, and exclusions for commercial and unregistered prepaid cards. |
| Fast access to provisional money | Visa describes replacement funds within five business days after notification when its conditions are met and the transaction has posted. | The credit is provisional and can be delayed, limited, withheld or rescinded under the circumstances Visa lists; other brands’ timing is not established here. |
| Online purchase verification | Visa Secure and American Express SafeKey add authentication at participating online merchants. | Participation is not universal, authentication is not used on every transaction, and neither feature prevents all fraud. |
There is no evidence in these policy pages to rank the brands by fraud rate, claim-success rate, average reimbursement speed or consumer losses. A more useful comparison is the exact card agreement, the issuer’s responsiveness, the transaction type and how quickly you report.
Questions to ask before choosing or relying on a card
- Who is the issuer, and where will I report a suspicious transaction at 2 a.m.?
- Does the account agreement include commercial, prepaid, debit and digital-wallet transactions in the same way as ordinary consumer credit purchases?
- What is the issuer’s process for pending versus posted transactions?
- When is temporary credit issued, and under what conditions can it be reversed?
- How are authorized users, recurring payments and replacement-card tokens handled after a suspected compromise?
- What alerts, transaction controls and online-authentication options can I turn on?
Bottom line for U.S. consumers
American Express offers an integrated support experience with monitoring, alerts, online-shopping authentication and direct account reporting on its cards. Visa publishes a broad Zero Liability statement for most credit and debit cards, plus detailed exclusions and provisional-fund conditions administered through the issuer. Mastercard’s cited terms offer a similar promise for eligible transactions when the cardholder uses reasonable care and reports promptly, while excluding commercial and unregistered prepaid cards and carrying an October 17, 2014 effective date.
Choose based on the complete cardmember agreement and the issuer’s support process, not the logo alone. When a charge is truly unauthorized, report it immediately through the issuer’s official channel, preserve records and follow the investigation instructions. When you authorized the purchase but have a merchant problem, use the separate dispute route.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

