Free tools Windows power users keep installed
One-click scans. No signup required.
An AI system can approve a card transaction in milliseconds while failing to give a useful answer to “Why did the AI approve this payment?” That is not necessarily a contradiction. Producing an outcome and explaining that outcome are different technical and legal tasks.
A payment decision may be a fraud-screening or authorization action, while a lending decision may be a credit decision with specific disclosure duties. The explanation that satisfies a cardholder, a fraud analyst, a compliance officer, and an auditor will not be the same. A credible explanation must identify the factors that actually influenced the result, fit its audience and purpose, and remain reliable as data and model behavior change.


As an Amazon Associate I earn from qualifying purchases.
What the title really means
“AI knows how to approve a payment but not explain one” is a useful warning about explainability, not a claim about one named bank or payment processor. A model can calculate a probability, apply a threshold, and return approve without producing a faithful account of the calculation in language a person can use.
An explanation is more than a list of data the system had available. It should connect the result to the factors that actually mattered. If a transaction was approved because the amount, merchant, device, location, and recent account history fit a learned pattern, those factors should be identified accurately. Saying only “the transaction met internal standards” does not tell the recipient what drove the result.
#1 Best Overall
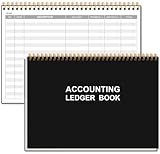
- EASY TO MANAGE - Use this accounting ledger book to track your payments, deposits, and balances, and develop good bookkeeping habits to meet your financial goals.
- UNDATED ACCOUNT TRACK - Use a ledger book to record every expense you make no matter what day it starts. The accounting book is plenty of space to record each transaction you make, and state its number, date, description, account, payment or deposit amount, and total balance.
- MANAGE YOUR FINANCES & SUCCEED - Use this business expense tracker notebook, You will be able to easily analyze your financial activities and quickly prepare accurate financial statements. Use your records to regularly assess your spending and income and find any unnecessary expenses you can cut to improve your financial performance.
- HIGH QUALITY - The A5 expense tracker notebook is used to high quality 100gsm pure white paper, pink elastic band and a back pocket for extra space. A total of 64 sheets(128 pages), it comes with 3480 entry lines (29 lines per page, 60sheets/120pages), 1 page Year Overview, 7 lined notes pages. The accounting book is plenty of space to record each transaction you make, and state its number, date, description, account, payment or deposit amount, and total balance.
- THE PERFECT GIFT - Use account ledger book for your personal or business finances, give it to your friends, colleagues as a gift for Birthday| Easter|Children's Day|Halloween|Thanksgiving|Christmas|Back to school and New Year's Day.
The explanation also has a job to do. A customer may need reassurance or a way to correct bad information. An analyst may need to decide whether to release a hold. A model validator may need to reproduce the result. A regulator may need evidence that the process is controlled and lawful. One technically correct output can therefore be inadequate for every audience except the system that generated it.
Payment authorization, fraud screening, and credit underwriting are different decisions
People often use “approved” to describe several financial events. The legal and technical consequences depend on which event occurred.
| Decision | What the system is deciding | Typical evidence used | Explanation boundary |
|---|---|---|---|
| Payment authorization | Whether a presented transaction should be accepted, declined, or sent for another check. | Transaction amount, merchant, time, device, location, account status, and real-time risk signals. | Usually an operational fraud or authorization decision; it is not automatically a credit decision covered by U.S. adverse-action notice rules. |
| Fraud screening | Whether activity resembles unauthorized, abusive, or suspicious behavior. | Behavioral patterns, identity signals, velocity, network relationships, and historical claims or disputes. | A customer-facing message may need to avoid revealing controls that would make evasion easier, while still giving a truthful reason for a hold or decline where required. |
| Credit underwriting | Whether to extend, continue, or change credit and on what terms. | Application information, credit history, income or affordability information, existing obligations, and model scores. | In the United States, covered adverse actions require specific and accurate principal reasons under the Equal Credit Opportunity Act and Regulation B. |
The Consumer Financial Protection Bureau’s Circular 2022-03 addresses the third category. It says a creditor using a complex or opaque algorithm still has to provide an accurate statement of the principal reasons for an adverse credit action. The circular states: “Creditors must be able to provide applicants against whom adverse action is taken with an accurate statement of reasons.” That requirement applies when a credit application is denied, an existing credit account is terminated, account terms become less favorable, or a credit-limit increase is refused. It does not turn every card-payment authorization into a regulated credit adverse-action notice.
A bank can therefore have a valid reason to give a short fraud-screening message for a declined purchase while being unable to use a generic “failed score” explanation for a denied credit application. For credit, the stated reasons must be specific and must describe factors actually considered or scored; model opacity is not a defense.
Why an AI can produce a result without a faithful explanation
Prediction is optimized separately from communication
Most decision models are trained to rank risk or estimate a probability. Their objective may reward accurate classification, low fraud losses, or fast processing. It does not automatically reward an explanation that a person can understand. A post-hoc explanation layer can generate plausible-sounding reasons after the score is produced, but plausibility is not proof that those reasons caused the score.
Many signals interact
A model may combine dozens or thousands of variables, including interactions that are difficult to summarize. A single transaction amount might be harmless on its own but risky when paired with an unusual device, a new location, and a burst of recent attempts. Removing one signal may not change the result because another correlated signal carries similar information. A short message can hide that structure, while a complete technical trace can overwhelm a customer.
The data may be wrong or stale
An incorrect address, duplicated device identifier, delayed account update, or mislabeled prior dispute can influence a decision. An explanation that says the system used the data is not useful unless the recipient can identify which data mattered and correct it. Data quality is therefore part of explainability, not a separate housekeeping task.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Model behavior changes over time
Fraud patterns, merchants, devices, and customer behavior change. A reason that was faithful when a model was validated may become misleading after a data distribution shift, a feature pipeline change, or a threshold adjustment. Explanations need their own monitoring and validation rather than being treated as permanent labels attached to a model.
What a useful explanation should contain
The right level of detail depends on the recipient and purpose, but a robust explanation normally answers five questions.
- What decision was made? State whether the transaction was approved, declined, delayed, or routed to manual review, and identify the relevant event and time.
- Which principal factors influenced it? Name the few factors that materially affected the outcome, such as an unusual device or a mismatch in account information. Do not substitute a generic label for the actual drivers.
- Were those factors actually used? The explanation must be faithful to the features, rules, or scores that influenced the decision. A reason selected for convenience or public relations is not an explanation.
- What can the person do next? Give a safe remedy: verify identity, update incorrect information, contact the issuer, wait for a review, or use another payment method. Do not promise that one action will guarantee approval.
- What are the limits? Explain when the message is a preliminary fraud signal, when human review is required, and which details cannot be disclosed because they would expose security controls.
For internal users, the record should go further: model and version, input values or feature snapshots, threshold and policy path, timestamps, human interventions, and the evidence used to reproduce the outcome. Sensitive details should be access-controlled rather than omitted from the audit trail.
What the FCA found about explanation formats
A Financial Conduct Authority research note, first published on 24 February 2025 and updated on 28 July 2026, tested whether people could identify decisions containing incorrect input data or flaws in the decision logic. It reported that explanation format significantly affected participants’ ability to judge decisions, and that the effect depended on the type of error.
An overview of the data available to the algorithm made it harder for participants to detect an input-data error in some settings. The same kind of overview helped them challenge a logic error, such as a system failing to use relevant consumer information. Additional information about the algorithm’s inner workings was well received and increased confidence in disagreeing with a decision, yet could still make error detection harder in certain situations.
Rank #3
The practical lesson is not “show everything” or “show as little as possible.” Test an explanation with the people who must use it and with the errors they are expected to find. The FCA note’s authors caution that the research contributes evidence and may not represent the FCA’s position. No universal percentage or effect size should be inferred from the summary; the direction of the findings is context-dependent.
U.S. credit law: specificity matters even with complex algorithms
Under the CFPB’s Circular 2022-03, a creditor cannot avoid the adverse-action explanation requirement by saying that a machine-learning model is too complex to interpret. The creditor must identify the principal reasons that actually led to the adverse action. “Internal standards,” “did not meet criteria,” and “failed the score” are not substitutes for those reasons when more specific reasons can be stated.
For example, if a credit-limit increase was denied because a high existing debt obligation and a recent delinquency were the principal scored factors, those factors must be identified accurately. The creditor should not name an income field that was never used merely because it sounds understandable. Nor should it list every variable in the model when the rule calls for principal reasons. This is a U.S. rule for covered credit actions, not a general legal mandate that every payment decline disclose a complete fraud model.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
How European transparency rules fit the picture
The European Commission identifies fraud detection and prevention as a financial-sector use of AI and highlights data quality, bias, and explainability as concerns. Its example of explainability focuses on why a person was or was not granted a loan, reinforcing the distinction between a credit decision and a point-of-sale authorization.
The Commission’s Article 50 guidelines, published on 20 July 2026, say that the relevant transparency obligations apply from 2 August 2026 to certain AI systems. The scope depends on the system and its use case. The date does not mean that every payment decision, bank fraud filter, or card authorization automatically falls under Article 50. Providers and deployers must determine whether their particular system meets the defined conditions and then apply the obligations that correspond to that category.
A governance framework for explainable financial AI
The French financial supervisor ACPR’s discussion document, updated on 24 September 2026, treats explainability as one part of a broader control system. It identifies four interdependent evaluation criteria.
| Criterion | Questions to answer | Evidence to retain |
|---|---|---|
| Data management | Are inputs accurate, relevant, timely, authorized, and tested for bias or leakage? | Lineage, quality checks, feature definitions, access controls, and correction records. |
| Performance | Does the model meet its intended objective without unacceptable false positives or false negatives? | Validation results, thresholds, error analysis, and performance by relevant population or scenario. |
| Stability | Does behavior generalize to production data, and can drift be detected before decisions degrade? | Monitoring dashboards, drift alerts, retraining triggers, rollback plans, and post-change tests. |
| Explainability in context | Is the explanation fit for its audience, purpose, risk, and decision type? | Customer messages, operator views, model-validation artifacts, user testing, and audit logs. |
ACPR describes four explanation levels: observation, which reports what happened; justification, which gives reasons for the outcome; approximation, which uses a simpler representation of a complex model; and replication, which enables another party to reproduce the decision. These are levels in the ACPR framework, not a universal legal taxonomy. A customer may need observation plus a safe next step, while a validator may need replication.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchThe framework also calls for review of human interaction with the algorithm, lifecycle governance, and both analytical and empirical audits. An explanation should be checked for faithfulness and usefulness in operation, not approved once in a design document and forgotten.
What financial institutions should do in practice
- Classify the decision. Record whether the system authorizes a payment, screens for fraud, services an account, or makes a credit decision. Map the classification to the laws and policies that apply in each jurisdiction.
- Define audiences and purposes. Write separate requirements for customers, frontline staff, fraud specialists, compliance reviewers, model validators, and auditors.
- Map the decision path. Identify inputs, transformations, rules, model scores, thresholds, overrides, and human actions. Keep a timestamped snapshot so the result can be reconstructed.
- Choose explanation content deliberately. Select principal factors, confidence or uncertainty information where appropriate, remediation steps, and security limits. Avoid exposing sensitive controls that would facilitate evasion.
- Test for faithfulness. Perturb or remove candidate factors and verify that the explanation changes when the underlying decision changes. Compare the message with the features and rules that actually drove the result.
- Test people, not just models. Give representative users realistic cases containing bad data and logic errors. Measure whether they can identify the problem and take the correct next action.
- Monitor after deployment. Track data quality, performance, drift, explanation stability, override rates, complaints, and escalation outcomes. Revalidate explanations after model, feature, threshold, or policy changes.
- Provide human recourse. A person should be able to correct inaccurate information, request review where appropriate, and understand what evidence will be considered. Record the review and its outcome.
Common explanation failures and their fixes
“The algorithm said no”
This is a conclusion, not a reason. Replace it with the principal factors that led to the result and identify the decision type. For covered U.S. credit actions, ensure the factors are specific and accurate.
A list of every available data field
Availability is not influence. A long inventory can distract users from a bad input and may make it harder to diagnose an error. Show the factors relevant to the decision and provide deeper technical detail to authorized reviewers.
A persuasive but unfaithful story
An explanation chosen because it sounds reassuring can mislead the recipient if the model used different variables. Generate reasons from the recorded decision path and test them against controlled changes.
One message for every audience
Customers need a safe next step; analysts need actionable signals; auditors need reproducibility. Use layered views with consistent underlying facts rather than forcing all users to read the same screen.
Best Value
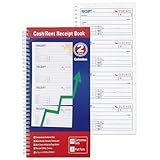
- 200 Carbonless 2-Part Sets: Each receipt includes a white original and a yellow canary duplicate-no carbon paper needed, ensuring clean, legible copies every time.
- Spiral-Bound for Easy Organization: Durable spiral binding keeps all 200 sets securely in place and allows pages to lay flat for quick, hassle-free writing and reference.
- Comprehensive Payment Details: Each form captures essential transaction info-payer's name, amount paid, purpose, time period, balance due, and recipient signature-for complete record-keeping.
- Easy Payment Method Selection: Preprinted checkboxes let you quickly mark the payment type-cash, check, credit card, or money order-for added clarity and professionalism.
- Consecutively Numbered Forms: Each receipt is clearly numbered to help you stay organized and track all transactions accurately for business or personal use.
Explanations that never change
Stale reason codes can survive a model update and become inaccurate. Version the explanation logic, monitor its relationship to model outputs, and retire messages that no longer describe production behavior.
What a customer can do after an unexplained decision
- Check whether the event was a payment authorization, a fraud hold, or a credit decision; the remedy and legal rights differ.
- Review the transaction details for amount, merchant, device, location, and timing errors. Secure the account immediately if the activity is unauthorized.
- Ask the provider which principal factor caused the decline or review and what information can be corrected.
- If the event concerns credit in the United States, request the adverse-action reasons and compare them with the information in your application or account file.
- Use the stated appeal, identity-verification, or human-review channel. Keep the case number, dates, messages, and documents supplied.
- Ask whether the decision was automated, whether a human reviewed it, and whether a corrected record will trigger a new decision.
A provider may legitimately withhold tactical fraud-detection details, but that does not justify inventing a reason or using a vague explanation where a specific, safe, and accurate one is available.
Why explainability matters beyond customer service
The U.S. Government Accountability Office reported on 19 May 2025 that financial institutions were using AI in credit decisions, customer service, and other activities. It noted potential benefits such as efficiency and lower costs alongside risks involving lending bias, data quality, privacy, and cybersecurity. U.S. regulators generally use existing laws, regulations, guidance, and risk-based examinations, with AI-specific guidance in some areas.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Explainability helps connect those controls. A reproducible record can reveal a corrupted input, a biased proxy, a threshold that drifted, or an operator who overrode a warning without justification. It can also show when a model is performing well but its customer message is causing people to miss errors. In that sense, explanation is not merely a nicer interface; it is evidence that the institution understands and governs the decision it is asking people to trust.
The practical answer to the title
AI can approve a payment without explaining it because authorization is an output-optimization problem, while explanation is a faithfulness, communication, governance, and sometimes legal-compliance problem. The remedy is not to reveal every internal calculation or to replace the model with a slogan. It is to classify the decision correctly, identify the factors that actually mattered, tailor the explanation to its audience, test whether people can detect errors, and monitor the explanation throughout the model’s life.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

